
 Newsletter

We’ve written about compound interest on this blog many times. But in conversations we keep noticing the same thing: even very smart people can barely imagine the power behind it. We catch ourselves thinking linearly too – exponential growth stays abstract.
High time to take a closer look: why do most people never experience the “8th wonder of the world” – as Albert Einstein supposedly called it? And what can you do about it? Or, to put it more bluntly: if the effect is so simple, why do so many people fail to turn it into real wealth?

In a nutshell
- Compound interest is the foundation of building wealth over the long term.
- Many people barely feel it because they give up too early or think linearly instead of exponentially.
- The first 10 years often feel sobering – after that, the turbo kicks in.
- Practical tip: the rule of 72 shows how quickly compound interest doubles your capital (72 ÷ return in % = years until it doubles).
- If you’re aiming for financial freedom, you have to make consistent use of compound interest.
- Your monthly contribution is the biggest lever: the higher it is and the earlier you start, the bigger the absolute effect.
- The easiest way to do this is with regular, automatic savings plans into broadly diversified equity ETFs – at low fees and without unnecessary withdrawals.
Contents
- What does compound interest actually mean?
- Compound interest held back: 6 typical pitfalls
- Financial freedom needs compounding
- Investment vehicles for compound interest
- Try it yourself: our compound interest calculator
- The ingredients have to work together
- And what happens once you’ve reached your goal?
- Updates
- Disclaimer
What does compound interest actually mean?
The term “compound interest” is easily misleading: “interest” here does not just mean classic bank interest – which hardly plays a role these days anyway. What matters is the principle of reinvesting returns. That covers everything an investment generates: interest, dividends and price gains too. The word compounding makes this clearer: it describes the interplay of all these returns. It’s exactly this principle that allows wealth to grow over time not linearly, but exponentially.
Think of it like a worker you initially have to pay all by yourself. But as soon as the first returns come in and are reinvested, you hire more “workers”. Each of them earns money for you without you having to lift a finger. With patience, this “team” keeps growing – and at some point the passive income it generates clearly exceeds your regular earned income.
A quick calculation
If you invest CHF 10,000 for 40 years at an annual return of 8% and consistently reinvest all returns, compound interest will grow it to around CHF 243,000.
If, on the other hand, you paid out the annual 8% like a coupon into a separate account that earns no interest, you’d end up with only about CHF 42,000 after 40 years.
In the first few years, the difference hardly seems worth mentioning – after 10 years, the compound interest version is only slightly ahead at CHF 22,196 versus CHF 18,000 for the coupon.
But from that point on, the gap keeps widening: the longer you stay invested, the faster growth accelerates.
After 40 years, the difference is already more than CHF 200,000 – which is what makes compound interest the legendary “8th wonder of the world”!

The rule of 72: compound interest for practical people
If you want to grasp compound interest without a calculator, you can use a simple rule of thumb – the rule of 72. It tells you roughly how many years it takes for your capital to double if you know the annual return:
72 ÷ return in % = years until your money doubles
Example:
- At a 6% return, it takes about 12 years,
- at 8%, just 9 years.
This simple back-of-the-envelope calculation instantly shows how big an impact even small differences in return have – and why investing for the long term pays off. The higher the return or the longer the investment horizon, the more powerful compound interest becomes.
If you want the exact figures, use our interactive compound interest calculator below.
Compound interest held back: 6 typical pitfalls
Pitfall no. 1: Our brain thinks linearly
Evolution has trained us to understand linear developments: step by step, year by year. A lot of everyday life works linearly – if I drive for an hour at 60 km/h, I cover 60 km; if I work twice as many hours, I earn roughly twice as much; if I run 10 km every week, I’ve covered 100 km after 10 weeks.
Exponential growth, on the other hand, remains hard to grasp. A classic example is the rice on the chessboard: the first square gets one grain, the second two, the third four – and so on. Halfway across the board, it still looks harmless, but by the end there are over 18 quintillion grains (18,000,000,000,000,000,000) on it – an almost unimaginable number.
That’s exactly why, in our article Behavioral finance: how to avoid the 13 biggest thinking errors when investing, we concluded that underestimating compound interest is probably the biggest investment mistake of all.
Pitfall no. 2: Too little patience
The first ten years can be frustrating. Example: if you invest CHF 10,000 at an 8% return, after 10 years you’ll only have around CHF 22,000 – a gain of CHF 12,000. After 20 years it’s CHF 49,000, after 30 years CHF 109,000, and after 40 years already CHF 243,000.
The key point: the big leverage only comes late. Many people give up before then and would rather spend the money on consumption – and never tap the full potential.
| Year | Value (CHF) | Increase per 10 years (CHF) |
| 0 | 10’000 | 0 |
| 10 | 22’196 | +12’196 |
| 20 | 49’268 | +27’072 |
| 30 | 109’357 | +60’089 |
| 40 | 242’734 | +133’377 |
Pitfall no. 3: Amounts that are too small
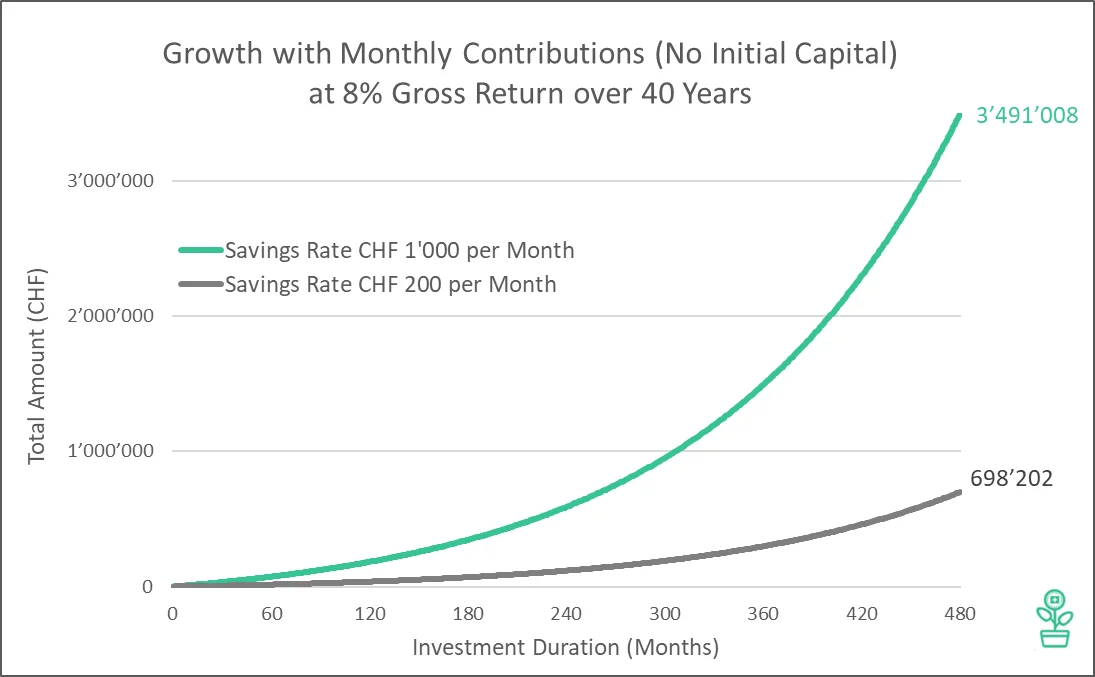
If you regularly invest small amounts, you also benefit from compound interest – but the “wow moment” only comes with higher monthly contributions.
The mechanism is identical – but in absolute terms it makes a huge difference whether you end up with a six-figure sum for a bit more security or a seven-figure sum as the basis for financial freedom.
– P a r t n e r o f f e r –
Regularly investing smaller or larger amounts is the be-all and end-all of building wealth systematically. The easiest way to do this is with an automatic savings plan. Saxo now offers all of its more than 100 savings-plan-eligible ETFs with no purchase commission.
– – – – –
Pitfall no. 4: Interruptions
If you pull out capital after a few years, you destroy the compound interest effect. Compounding only works if you make no withdrawals over a long period.
At an 8% return, CHF 10,000 grows to around CHF 243,000 in 40 years. A single withdrawal of CHF 5,000 after 10 years, however, cuts the final value to just CHF 188,000 – a loss of CHF 55,000, caused by an early withdrawal of a mere CHF 5,000.

Pitfall no. 5: Emotions & volatility
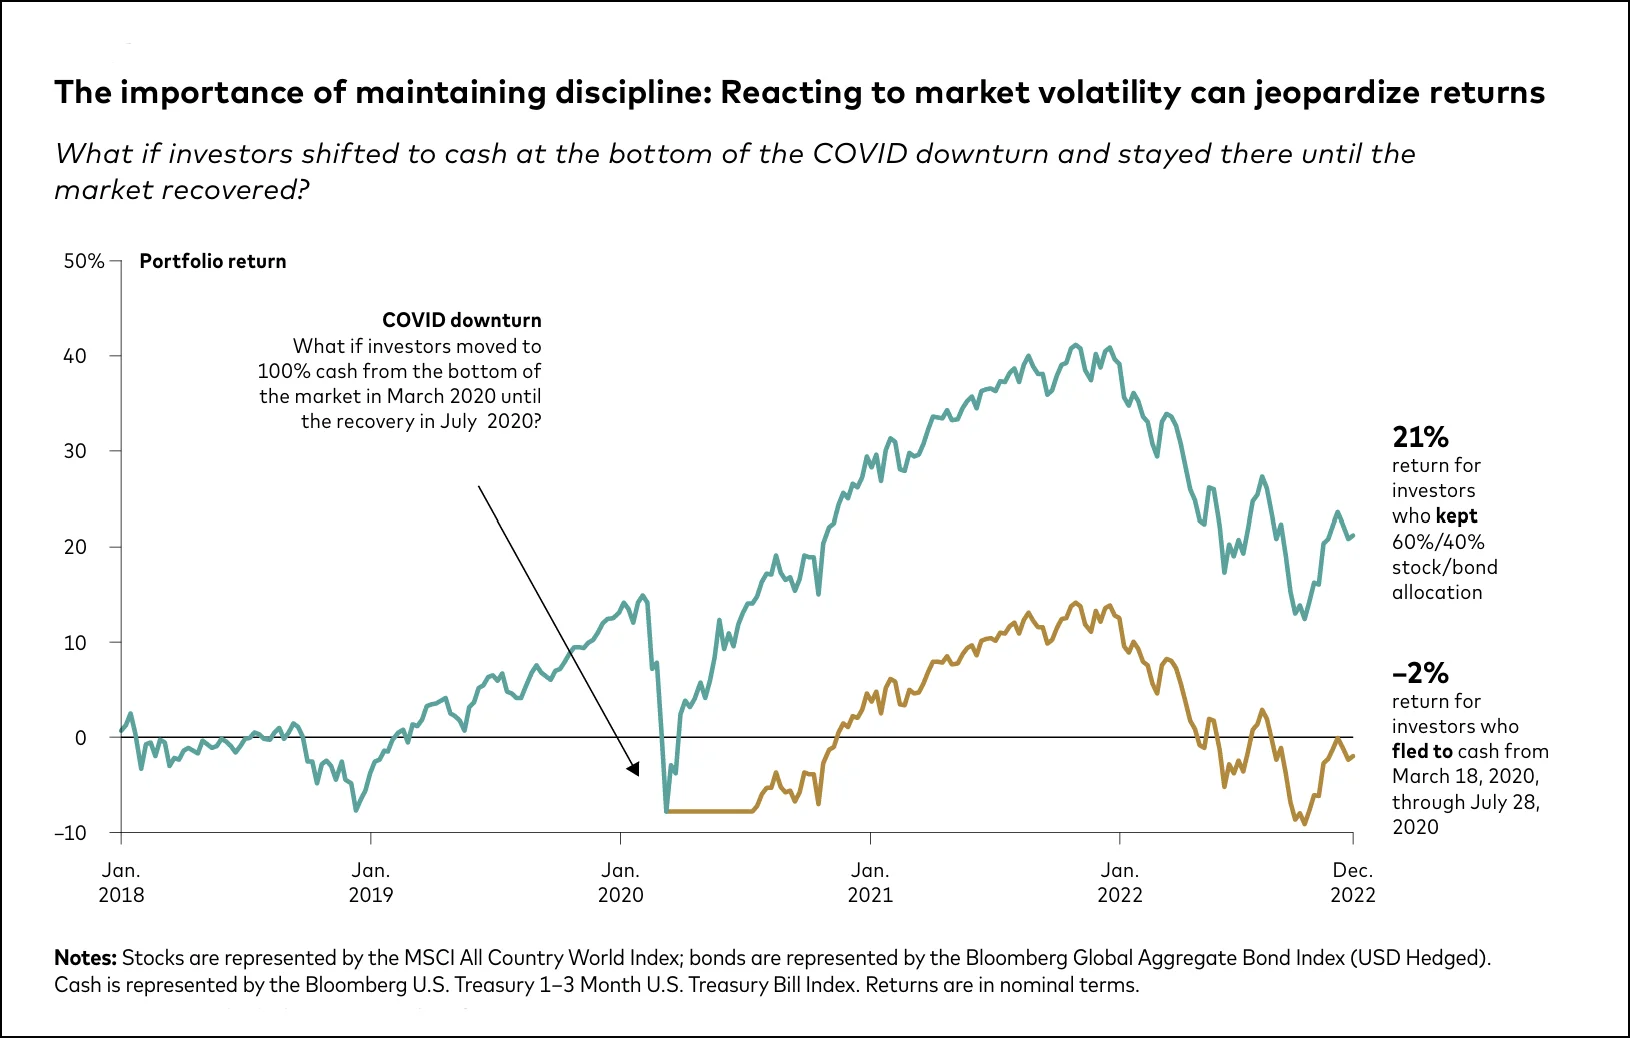
Market swings are unsettling. If you sell in a panic, you rob yourself of the chance of decades of growth.
One example: in the coronavirus crash of March 2020, the MSCI World lost around –30% within a few weeks. Many investors sold out of fear – only to watch the markets climb to new record highs a few months later. Those who got out missed exactly the phase in which the biggest gains were made.
So emotions can destroy the compound interest effect in two ways:
- Panic in a crisis: capital is sold at a loss and is missing when the recovery comes.
- Euphoria in boom times: investors buy in at high prices, when the market is already overheated.
The stock market doesn’t reward the smartest or the fastest, but the disciplined who stay the course. Investing legend Warren Buffett sums it up: “The stock market is a device for transferring money from the impatient to the patient.”
For concrete tips on keeping a cool head in turbulent times, see the article: Stock market crash guide: how to handle market crises with confidence and profit in the long run.
Digression: Lombard loans – double the upside, double the risk
Investors with a bigger appetite for risk, like Toni, have also used Lombard loans as a compound interest booster. They let you amplify returns in upswings – and buy more at lower prices after market dips. In return, though, the risks are higher: margin calls or even forced sales can turn the effect into its opposite.
More on this in the article: Lombard loans for buying ETFs: a booster for your return on equity or playing with fire?
Pitfall no. 6: Costs, taxes, inflation & currency risks
Compound interest only unfolds its full power if it isn’t held back by costs, taxes, inflation or currency risks. We take a closer look at these four factors below.
- Fees: an ETF with a 0.1% expense ratio (TER) is vastly superior over the long term to a fund with a 1.5% TER. Over 40 years, this can easily add up to a difference of several hundred thousand francs (see chart below).
- Taxes: investors in Switzerland are in a privileged position because capital gains are tax-free. Only dividends and wealth itself are taxed. Find out more about possible tax savings on your investments in the article ETF taxes in Switzerland: optimise your portfolio with these 5 tax-saving tips.
- Inflation: it eats away at purchasing power, but you can’t control it. In Switzerland, it has historically been much lower than in the US or the eurozone – usually only around 1% p.a. That’s an advantage: nominal returns of 6–8% often still mean 5–7% real returns here. Even so, over decades even moderate inflation can noticeably reduce purchasing power.
- Currency risks: Swiss investors often invest in globally diversified ETFs. This broad diversification pays off in the long run because you benefit from the growth of the global economy. At the same time, however, the strong Swiss franc can eat into part of the return, because foreign income is worth less when converted into CHF. This dampens the compound interest effect and should be factored into your planning.
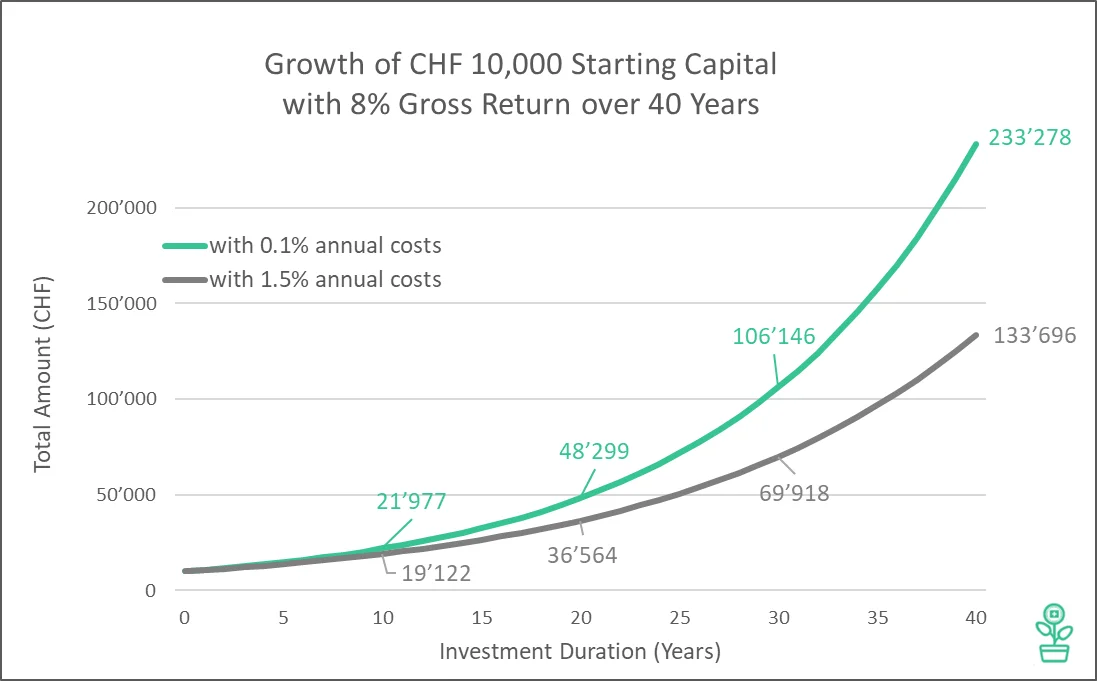
Conclusion: if you really want to make compound interest work for you, go for low-cost ETFs, optimise for taxes where possible – and always keep an eye on inflation and currency risks.
Financial freedom needs compounding
If you want to achieve financial freedom, there’s no way around compound interest. Alternatives such as inheritances or lottery wins depend on luck – you can neither plan for them nor rely on them.
If you want to take matters into your own hands, you need to harness the power of compound interest. You’ll find more on this in our article Financial freedom – hype or a goal worth pursuing?
Albert Einstein is said to have once called compound interest the “eighth wonder of the world”: “He who understands it, earns it… he who doesn’t, pays it.”
But watch out: reality isn’t linear
The charts in this article are based on a constant average return – 8% p.a. in our example. In practice, of course, things don’t run that smoothly:
- Some years bring +20% or more.
- Other years end at -10% or even -30%.
- Only over longer periods does the effect smooth out.
Is 8% even realistic?
The figure isn’t pulled out of thin air:
- Over the last 100 years, the S&P 500 has returned around 10% a year nominally on average. After inflation, that leaves around 6–7% in real terms.
- In recent decades, the MSCI World has delivered around 7–9% nominally, i.e. 4–6% in real terms.
- The SPI (Swiss stock market) is also in this range over the long term, albeit slightly lower.
Important: our example calculations at 8% are nominal – taxes, fees and inflation are not taken into account.
Investment vehicles for compound interest
Compound interest relies on returns not being spent but consistently reinvested. Only then can the snowball effect build up over the long term. The following overview shows which types of investment are particularly well suited for this – and which are less so.
Investments with (+) and without (-) a compound interest effect
 Accumulating equity ETFs or index funds: dividends are reinvested automatically – ideal for compounding. Distributing equity ETFs or index funds: compound interest always works on price gains. Dividends only boost it if you reinvest them manually. Individual stocks: compounding through price gains. Dividends only count if reinvested, plus concentration risk up to and including a total loss. Real estate funds: rental income is reinvested or distributed. Reinvesting increases the effect. Bonds: interest coupons can be reinvested, but the effect remains much weaker because of low yields. P2P loans / crowdinvesting (platform-based lending and equity models): compound interest arises when repayments are reinvested. Strong in theory, but risky in practice due to defaults, illiquidity and platform risks.
 Bank account / savings account: little or no interest, effect practically negligible Gold: no ongoing income, only price movements. Since no value is created, there’s no compound interest effect. Bitcoin & crypto: no income either, only price movements. Unlike with stocks, price increases don’t automatically raise the basis for future income – they remain pure paper gains. That’s why there’s no real compound interest effect here. Collectibles (e.g. art, classic cars, watches, wine): no ongoing income either; gains in value can only be realised by selling. Markets are often illiquid and transaction costs high – no real compound interest effect. Consumer goods: loss of value instead of return, negative compounding effect
For more on particularly convincing equity ETFs, see our big comparison Best ETFs in Switzerland and worldwide 2025: And the winner is…
Try it yourself: our compound interest calculator
Theory is one thing – it gets even more exciting when you can plug in your own numbers: starting capital, monthly contribution, expected return, investment horizon.
That’s exactly why we built our compound interest calculator. It shows you instantly:
- how much your capital can grow to in 10, 20 or 40 years,
- how strongly even small changes in return or monthly contribution make a difference,
- and how much patience really matters.
Here’s the compound interest calculator:
Compound interest calculator
Calculation
If you have 10 years, monthly 100CHF to 5% invest, your Final capital 23.763CHF. This is made up of 17.000CHF Deposits and 6.763CHF Interest or investment income.
Diagram
The ingredients have to work together
Compound interest is powerful – but only if several factors work together. A single ingredient isn’t enough:
- Lots of patience: the effect takes time to become visible. Only with an investment horizon of more than 10 years does the snowball start rolling, picking up speed with every year.
- A meaningful savings rate: as a rule of thumb, at least 10% of your income. If your income rises, you should let your monthly contribution grow in absolute terms too – or, even more effectively, raise the savings rate itself, e.g. to 15% or more.
- A high-return investment: historically, equities have proven to be by far the most attractive asset class. Best suited are low-cost equity ETFs on global indices such as MSCI World or FTSE All-World.
A prime example is Warren Buffett: he bought his first stock at the tender age of 11. Today he is one of the richest people in the world. The remarkable thing: around 99% of his current wealth (over USD 100 billion) was created only after his 50th birthday – thanks to lots of patience, steady investing and compounding, i.e. the compound interest effect.
Important for anyone who doesn’t want to or can’t spend 40 years building wealth before (early) retirement: compound interest also works over shorter periods. From around 10 years on, things pick up speed. With a horizon of 10 or 20 years, you can also reach considerable sums with high starting capital and/or high monthly contributions.
An example with an 8% return over 15 years:
- Starting with CHF 200,000 leads to a final value of approx. CHF 661,000
- Starting with CHF 100,000 + CHF 1,000/month leads to a final value of approx. CHF 676,000
And what happens once you’ve reached your goal?
Compound interest shows its full strength while you’re building up your wealth. But at some point you reach the stage where it’s no longer about saving and investing, but about living off the capital you’ve built.
A frequently cited rule of thumb is the 4% rule: if you withdraw 4% of your invested assets each year, statistically you shouldn’t run the risk of running out of money early, even over 30 years. It’s a useful starting point, but no substitute for individual planning.
Because reality is more complex:
- Market phases never run in a straight line. A stock market crash can be especially dangerous in the first years of the withdrawal phase (known as sequence-of-returns risk).
- Your personal situation matters. Taxes, living costs or additional income such as AHV and BVG pensions have a major influence.
- Flexibility increases security. If you reduce or postpone your withdrawals in bad stock market years, you lower the risk of using up your capital too early.
Find out more in our article Withdrawal plans: how to retire early and stress-free.
Updates
2025-11-06: added an explanation of the rule of 72 as an easy way to calculate the compound interest effect.
Disclaimer
Disclaimer: investing involves the risk of loss. You have to decide for yourself whether or not you want to take on these risks.
Errors excepted: we have written this article on the magical power of compound interest to the best of our knowledge and belief. Our goal is to give you, as a private investor, information on finance that is as objective and meaningful as possible. If we have nevertheless made mistakes, or if important aspects have been forgotten and/or are no longer up to date, we would be grateful if you let us know.
About the authors

Stefan Huser
Stefan has been investing in the stock market himself since 2015. He has been shaped by Markowitz’s portfolio theory and Gerd Kommer’s book “Souverän investieren”. He follows a core-satellite strategy: a global equity portfolio of ETFs forms the core, complemented by alternative investments. At the blog, he mainly takes care of the writing. Stefan lives with his family in Zurich and is interested in literature, photography and financial freedom.

Antun Brcina
Antun (“Toni”) has been investing in the stock market since 2015. Financially, he has been particularly inspired by Gerd Kommer’s book “Souverän investieren” and the Fama-French five-factor model. His money is invested in a broadly diversified, long-term global equity portfolio of ETFs. At the blog, he mainly works on the calculators and the code. Toni lives with his family in the Zurich area and is interested in sports, technology and entrepreneurship.








1 Comments
“Steuern: In der Schweiz sind Anleger:innen privilegiert, da Kapitalgewinne steuerfrei sind. Versteuert werden lediglich die Dividenden sowie das Vermögen als solches.”
“Nur” das Vermögen? Im Ausland wird man üblicherweise nicht dafür bestraft, dass man spart, dort bezahlt man die Steuer auf dem Einkommen (realisierte Kursgewinne), nicht noch zusätzlich auf dem Vermögen und üblicherweise auch keine Finanztransaktions-Steuer (unsere Stempelsteuer) …