 Newsletter
Dry January, Veganuary, more exercise or all of the above? As sensible as these and other resolutions may be, sadly they rarely last long. We want to change that, at least when it comes to your money. Because once your finances are properly set up, they will run like clockwork for decades.
In this article, we show you how to build your wealth steadily and on autopilot while keeping full track of your spending. You will also learn why the right money mindset is a key success factor on your path to financial freedom.

In a nutshell
Money is not the centre of our lives; it should help us live the way we want to. These five financial resolutions will help you reach that goal:
- Build financial literacy
Without a basic understanding of return, risk and compound interest, you lack the foundation for everything else. - Know your own finances
Your net worth and savings rate are your starting point. Measure first, then optimise. - Pay off debt & build an emergency fund
Security before returns. Without a buffer for unexpected events, any strategy becomes fragile. - Increase your savings rate
The most important lever for building wealth and achieving financial freedom. - Invest regularly
Passively, automatically, with fixed amounts – this is where the system is put into practice.
Why financial freedom is about more than money
Building wealth is not an end in itself. With these financial resolutions, we neither want to encourage petty penny-pinching nor take a red pen to worthwhile spending such as donations. Because for us, one thing is clear: Money is not the centre of our lives; it should help us live our lives the way we want to. A goal we find worthwhile is a self-determined life outside the rat race.
Whatever goals you pursue: if you are financially secure, life is a lot more carefree – whether at work, on your travels or when you once again feel like speaking your mind freely.
These five financial resolutions, which we explore in depth in this article, are designed to pave your way to financial freedom and a self-determined life:
- Financial resolution no. 1: Build financial literacy
- Financial resolution no. 2: Know your finances
- Financial resolution no. 3: Pay off debt & build an emergency fund
- Financial resolution no. 4: Increase your savings rate
- Financial resolution no. 5: Invest regularly
Financial resolution no. 1: Build financial literacy
Why should I do this?
We start with the most general of all financial resolutions: your financial education. The main motivation is that financial security is a decisive factor for a carefree, free life. On the “operational level”, solid financial knowledge gives you stability in your investment decisions and keeps you from acting rashly.
In concrete terms: once you have internalised the most important financial basics, you will not sell all your securities at a loss in a panic during the first major market slump.
The challenge is therefore mainly a mental one and is closely linked to the “right” money mindset – correct practical implementation only comes second.
How do I put it into practice?
The passive investment strategy with broadly diversified equity ETFs that we prefer is scientifically sound and easy to implement. But it does not work without any financial literacy at all. At the very least, you should internalise these three “financial truths”:
Understand the interplay between return and risk
There is no return without risk. And without a return, your wealth steadily loses purchasing power to inflation. In 2025, inflation in Switzerland was 0.2%. To preserve the real value of your money, you would need to earn at least that much interest on it. That is hardly possible with safe investments such as a bank account covered by deposit insurance, as savings rates are likely to remain at zero across the board in 2026 as well.
For your emergency fund and day-to-day expenses, such safe and liquid investments are still ideal. What counts here is security and immediate availability, not returns.
With long-term wealth building – including the 3rd pillar – it is the other way round: short-term fluctuations are normal and necessary. Without equities, preserving your wealth in real terms is hardly possible. Broadly diversified equity ETFs significantly reduce concentration risk compared with individual stocks.
In short: any investment can only ever meet two of the three goals of return, security and availability – never all three at the same time.
You can find out more in our article The magic triangle of investing.
Understand the powerful effect of compound interest
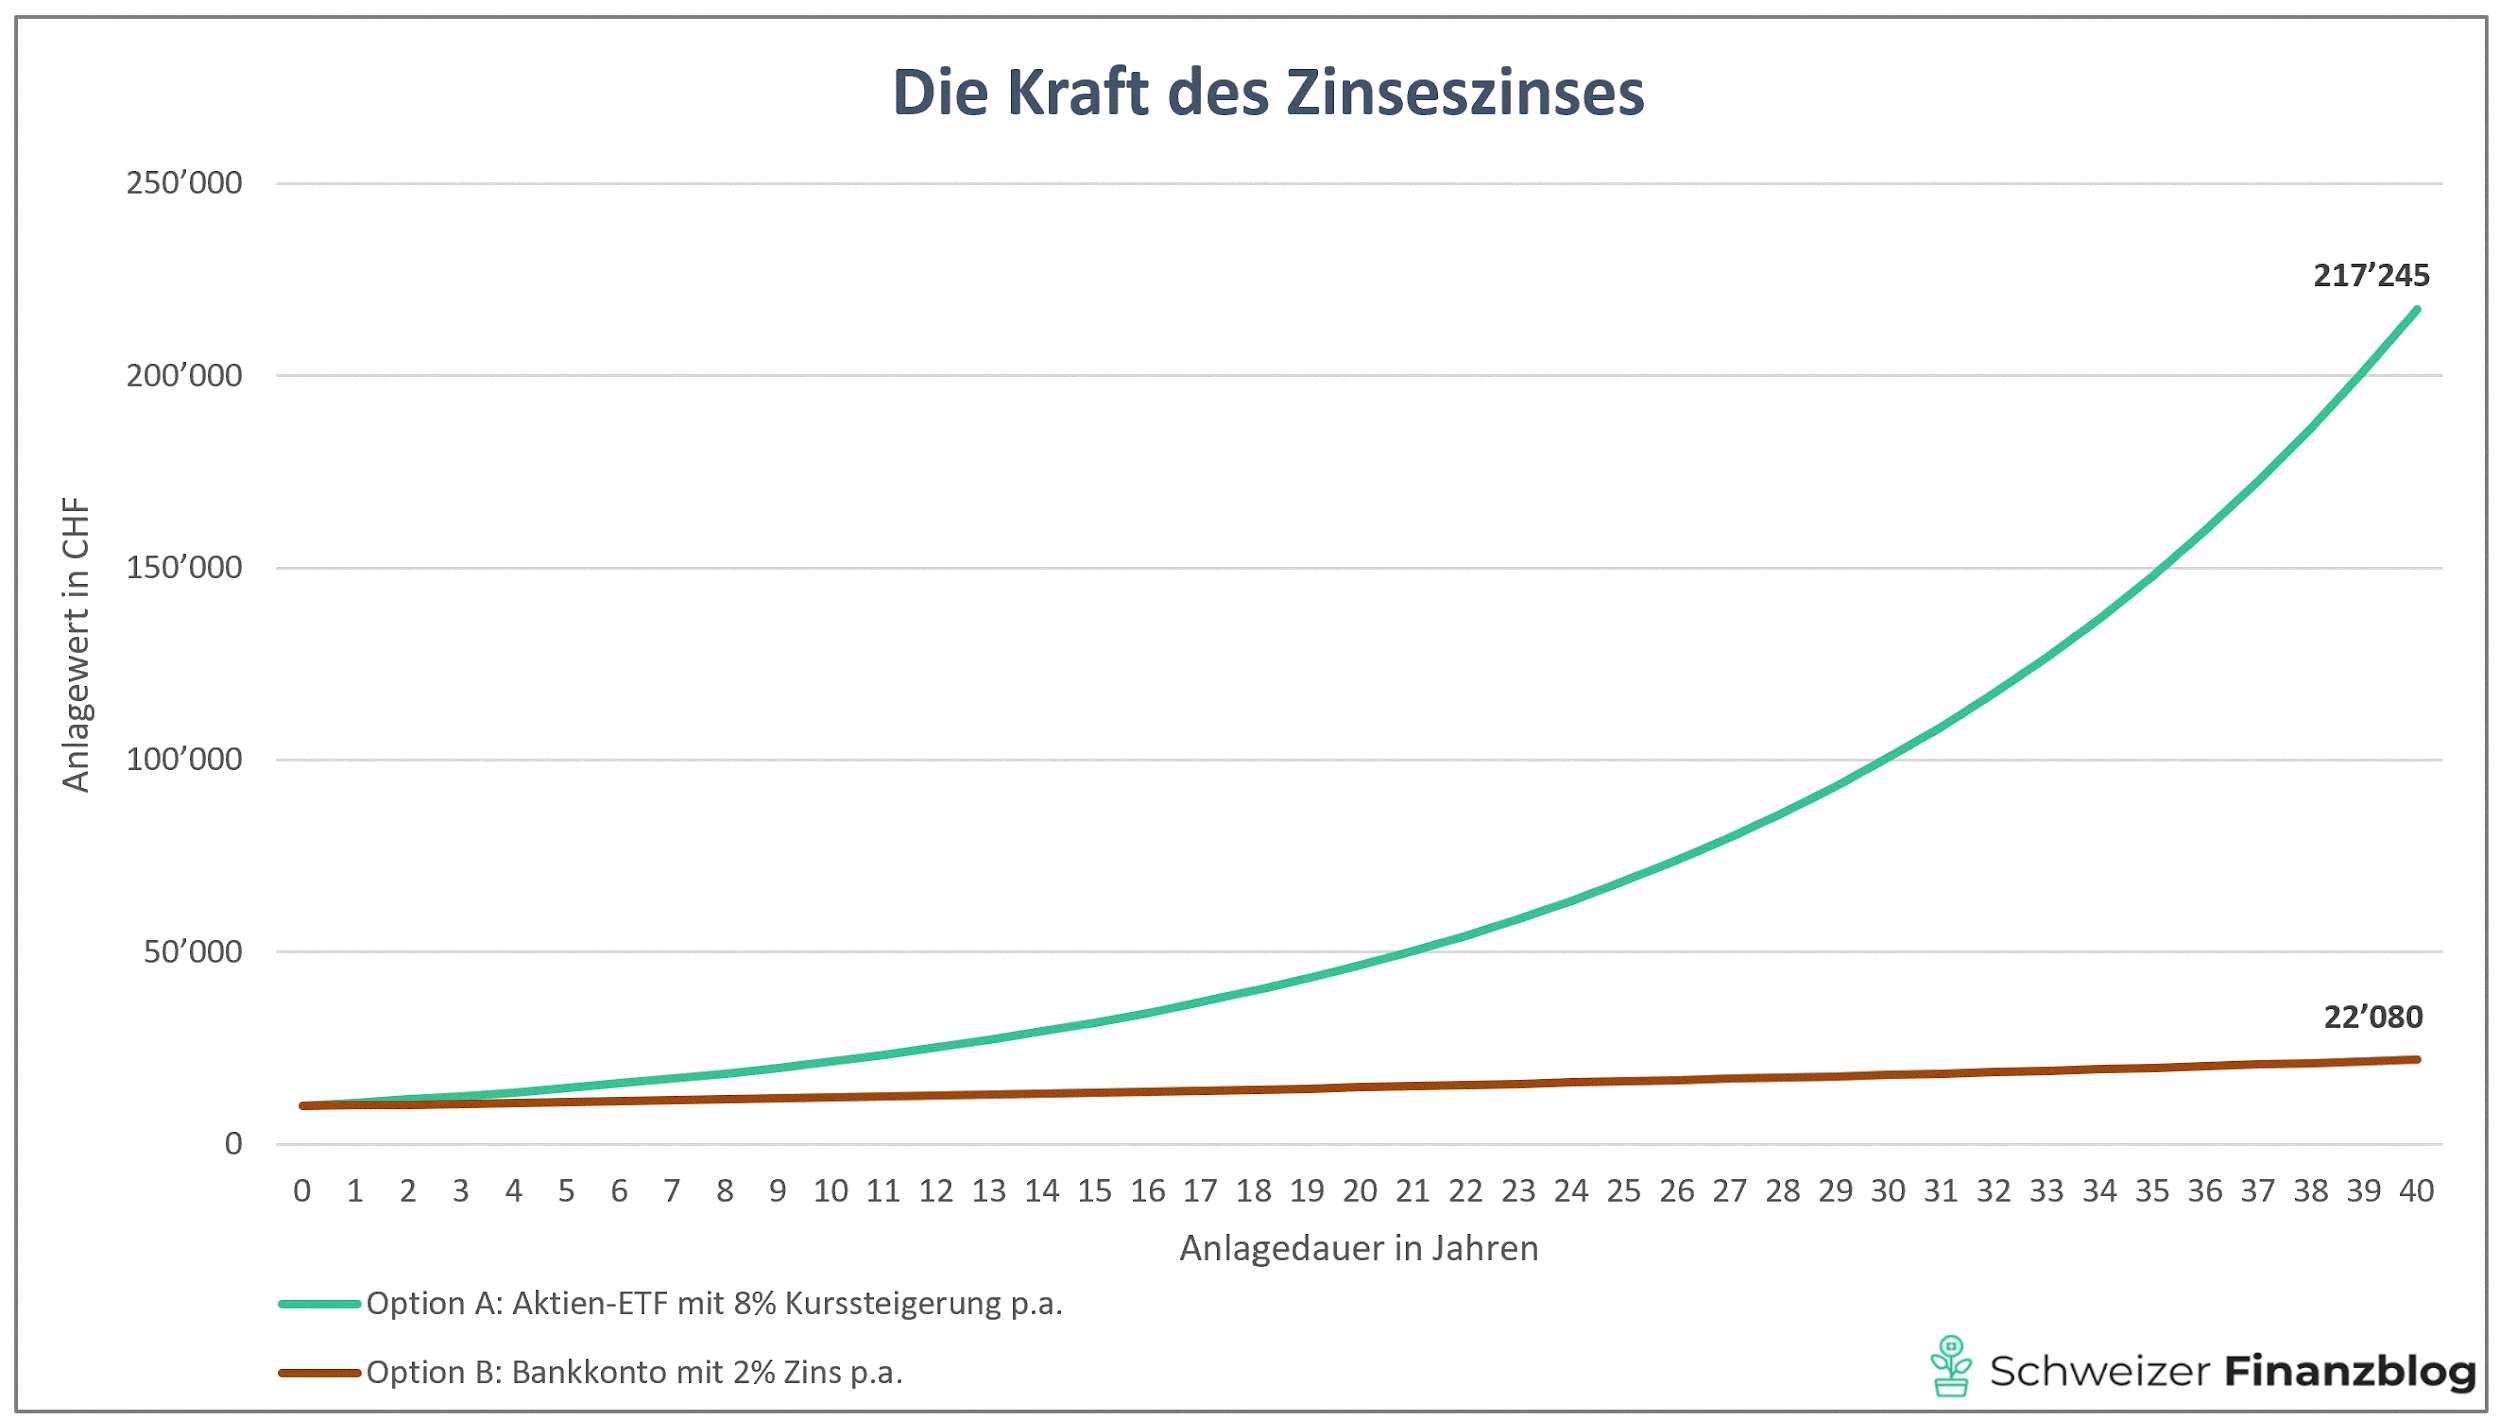
Albert Einstein is said to have once remarked: “Compound interest is the eighth wonder of the world. He who understands it, earns it; he who doesn’t, pays it.” In fact, compound interest is one of the most powerful levers for building wealth. Two factors are decisive: return and time. The higher the return and the longer the investment horizon, the stronger the effect.
Compound interest calculator
Calculation
If you have 10 years, monthly 100CHF to 5% invest, your Final capital 23.763CHF. This is made up of 17.000CHF Deposits and 6.763CHF Interest or investment income.
Diagram
Understand the advantages of passive investing
Passive investing means investing on an index basis and being content with the market return. You will not beat the market this way – but you do not have to. Historically, the long-term average return on equities has been around 8% a year.
If you assume that company values will keep growing over the long term thanks to innovation and productivity (with setbacks along the way), broadly diversified equity ETFs are the obvious choice. They are the simplest and cheapest way to invest passively.
Active investing, on the other hand, is above all lucrative for asset managers. For you, however, it means significantly higher costs: 1–2% a year compared with often less than 20 basis points (<0.20%) for ETFs. No wonder hardly anyone manages to beat the market over the long term after costs.
Every beginning is hard – but with financial literacy, your finances become manageable instead of a burden.
You can find out why we are so convinced of ETFs in the article ETFs: the revolution in investing.
To dig deeper, we also recommend our article series Learn to invest – in 8 lessons.
Financial resolution no. 2: Know your finances
Why should I do this?
A thorough assessment of where you stand will give you clarity about your financial situation. But that is not all: you will also find out what your biggest expense items are – which is naturally also where the greatest savings potential lies dormant.
How do I put it into practice?
Taking stock of your finances means determining your income streams (active ones such as employment income and passive ones such as dividends), your main expense items and, as the difference, your monthly savings. With a monthly disposable household income of CHF 10,000 and expenses of CHF 8,000, your monthly savings amount to CHF 2,000 and your savings rate is 20% (=2,000/10,000).
You also calculate your assets (essentially your cash, securities and real estate), any debts (e.g. student and consumer loans, mortgages) and, as the difference, your net worth. We consider net worth to be the most important and meaningful financial metric on the path to financial freedom. Because unlike a high income, a high net worth brings financial security, often combined with passive income streams such as dividends.
So to achieve financial freedom, what matters is not so much how much money you earn, but how much of it you save – and invest profitably. Before we get there, however, we still need to take care of financial protection. That brings us to the next resolution.
Financial resolution no. 3: Pay off debt & build an emergency fund
Why should I do this?
If you live free of (consumer) debt, have insured existential risks and always have a sufficiently large emergency fund at hand for uninsured, unforeseen events, the foundation for a carefree life is laid. You can then enjoy the pleasant sides of life and focus on non-financial challenges.
How do I put it into practice?
Before you start building wealth, you should first pay off any debts. The focus is on high-interest consumer debt, whose interest rates are usually much higher than the expected gains in value of equity ETFs. In concrete terms:
-
deactivate instalment payment options on credit cards (the popular Certo!, for example, charges 12% p.a. for this) and switch to free direct debit (LSV), or
-
use only debit cards without an overdraft function instead of credit cards.
Once your consumer debt is paid off, it is essential to build up a so-called emergency fund for unforeseen events such as a hefty dentist’s bill or an unexpected replacement of your washing machine. Depending on your income and personal risk assessment, it should amount to around two to three months’ salary.
Important: In Switzerland, you are protected by law against many events that threaten your livelihood, such as job loss, illness or accident. In addition to the compulsory insurance policies, private liability insurance is worthwhile, as it can also protect you from financial ruin.
On the other hand, other insurance policies that only cover relatively small financial risks (e.g. the “all-round protection for your mobile phone”) should be cancelled. If the worst happens, such damage is better covered by your emergency fund.
In our experience, the smartphone bank Yuh is particularly well suited for keeping your emergency fund: safe, separated from your day-to-day payments in a dedicated savings pot, yet available at any time and – apart from historically low interest rate phases like the current one – paying good interest. On top of that, the account is free of charge. With our promo code YUHSFB, you get a welcome bonus and support our blog at the same time.
Exception: mortgage debt
An important exception is mortgage debt. It does not necessarily have to be paid off quickly – especially when interest rates are historically low. Owner-occupied property is primarily a consumer good with the character of an asset, not a classic asset class. Nevertheless, it ties up a great deal of capital in a single, not very flexible property. Paying it off in full therefore increases concentration risk, because a large part of your wealth is “set in stone”.
In many cases, it therefore makes more sense to leave part of your wealth invested and benefit from long-term return opportunities instead of paying down the mortgage as much as possible.
Financial resolution no. 4: Increase your savings rate
Why should I do this?
If you want to become financially free, there is no way around an ambitious savings rate . It is your central lever: the higher you set it, the sooner you will achieve financial freedom, i.e. independence from the income you actively earn from work. How fast this can happen is described in our article Financial freedom – hype or a goal worth pursuing?
How do I put it into practice?
As a reminder: the savings rate is expressed as a percentage and puts your monthly savings (in CHF) in relation to your total income.
But how are you supposed to simply increase your savings rate? Admittedly, that is easier said than done. And yet we are convinced that anyone can raise their savings rate. You have two levers at your disposal: first, increasing your income and second, reducing your expenses.
The easiest and most effective way to increase your savings rate in special life situations is by not joining in with so-called lifestyle inflation (income-driven growth in consumption). This describes the phenomenon whereby, as income rises, your standard of living and thus your consumption usually rise too – and the savings rate falls by the wayside. This link is well documented scientifically and applies to most people.
That is precisely why there is a huge opportunity here: in hardly any other phase do you have a better chance of getting significantly closer to financial freedom within your lifetime than in exactly these situations with noticeable pay rises.
An example from our own experience
During our studies, a modest lifestyle was a must for us. With our tight finances at the time, there was simply no alternative. After graduating, we earned “real” money for the first time, but hardly raised our standard of living for years. (Decades later, Stefan still does not own a car.) The reason: during our studies, we had got used to a frugal lifestyle.
After such changes in life stage, it is often surprisingly easy to increase your savings rate massively from one day to the next – in extreme cases from 0 to 50% or more. The reverse, i.e. a deliberate downgrade of your standard of living, is much harder. Savings are then quickly felt as painful restrictions.
As mentioned, these are selected and rather rare, sometimes even one-off opportunities. Let us now turn to the more frequent situations in which you can increase your savings rate or your investments step by step.
When it comes to your employment income, in the short term you depend on your boss’s goodwill and your negotiating skills. In the longer term, however, you can deliberately increase your income – for example through further training and by taking on more responsibility or better-paid tasks.
The spending lever as an instant savings rate booster
The spending lever has the big advantage that it works immediately. Every franc you save directly increases your savings rate. So go through the expense items you identified earlier and focus on the big ones – that is exactly where the greatest savings potential lies.
With contracts for mobile phones and the like, it is often worth cancelling them as a precaution. This gives you a strong negotiating position and at the same time keeps the option of switching providers open.
A real no-brainer in Switzerland is switching health insurer. As the benefits of basic insurance are set by the state, you can switch to the cheapest insurer every year without losing any benefits. In addition, the maximum deductible of CHF 2,500 is worthwhile for most people – provided you have an emergency fund in case the worst happens. That brings us to the next financial resolution.
Financial resolution no. 5: Invest regularly
Why should I do this?
At last we come to the most important part of a financially carefree life: investing. It is not only the most important part, but also the one with the highest priority. The fitting motto is: Invest today, consume tomorrow. Because the earlier you start, the more the compound interest effect helps you build wealth.
If you do not prioritise investing, there will be a thousand reasons to spend your savings on consumption. This behaviour is scientifically proven, by the way, and is often explained by Parkinson’s law. According to it, we tend to use up the resources available to us in full. Applied to money, this means: regardless of how much we earn, we tend to spend it all – unless we follow a clear, well-thought-out plan.
How do I put it into practice?
Based on your monthly savings, the next step is to invest the money you have saved sensibly and profitably.
With an investment horizon of at least 10 years, you can use your monthly savings – or part of them – to build a global equity portfolio with ETFs month after month.
How high your equity allocation should be depends on your risk profile. It consists of two parts:
your risk capacity and your risk tolerance.
Risk capacity can be determined objectively and depends on your assets, income, expenses and investment horizon.
Risk tolerance is subjective and describes how well you can cope with price fluctuations. In concrete terms: how does it feel for you when your portfolio is temporarily down 10, 20 or even 50%? The better you can handle it, the higher your equity allocation can be.
Important: Even broadly diversified equity portfolios can suffer temporary losses of up to 50% in extreme phases.
Regardless of your equity allocation, you should build your wealth as rule-based and automated as possible through an ETF savings plan.
In practice, you set up a standing order with your bank that tops up your securities portfolio – with an online broker or robo-advisor – at the start of every month. In addition, you activate another standing order for your securities-based Pillar 3a.
You can find out more about the advantages of savings plans in the article Swiss ETF savings plan: 3 strong reasons for the autopilot strategy.
– Partner offer –
Saxo Bank now offers all savings plans without purchase fees – and you can also invest in several ETFs at the same time. You can find out more in our detailed review.
– – – – –
Conclusion on the financial resolutions
In our view, implementing these five financial resolutions lays the foundation for your financial freedom. Success depends on two factors: your money mindset and how well you organise your finances. You develop the former through financial education and practical experience as an investor. You achieve the latter through clarity about your financial situation, consistently automating your investments via an ETF savings plan and – last but not least – the smart choice of suitable financial partners and solutions.
As mentioned at the beginning, our financial resolutions are not about piling up as much money as possible for its own sake. Rather, a high net worth should give you financial independence and genuine self-determination outside the rat race. A goal that enriches not only your account, but your life.
You might also be interested in
Updates
2026-01-22: Article comprehensively updated.
2025-03-11: Inflation rates and other data updated. 5th financial resolution expanded to include knowing your own risk profile, consisting of risk capacity and risk tolerance.
Disclaimer
Disclaimer: Investing involves the risk of loss. You must decide for yourself whether or not you want to take these risks.
Errors excepted: We have written this article on five financial resolutions for the new year to the best of our knowledge and belief. Our aim is to provide you as a private investor with information on finance that is as objective and meaningful as possible. Should we nevertheless have made mistakes, forgotten important aspects and/or if information is no longer up to date, we would be grateful if you let us know.
About the authors

Stefan Huser
Stefan has been investing in the stock market himself since 2015. He has been shaped by Markowitz’s portfolio theory and Gerd Kommer’s book “Souverän investieren”. He follows a core-satellite strategy: a global equity portfolio of ETFs forms the core, complemented by alternative investments. At the blog, he mainly takes care of the writing. Stefan lives with his family in Zurich and is interested in literature, photography and financial freedom.

Antun Brcina
Antun (“Toni”) has been investing in the stock market since 2015. Financially, he has been particularly inspired by Gerd Kommer’s book “Souverän investieren” and the Fama-French five-factor model. His money is invested in a broadly diversified, long-term global equity portfolio of ETFs. At the blog, he mainly works on the calculators and the code. Toni lives with his family in the Zurich area and is interested in sports, technology and entrepreneurship.









2 Comments
Interessante Tipps. Tatsächlich finde ich beim Thema sparen sollten wir von unseren Großeltern lernen. meine Oma hat mir beigebracht zu gärtnern, zu nähen, Hausmittel herzustellen und Kleinigkeiten im haus zu reparieren. So zahle ich zwar z.B. für Schrebergarten und gute Werkzeuge, sowohl für den Garten als auch für meine Wohnung, aber ich spare mir meistens einen Handwerker zu holen, Gemüse/Gewürze/Putzmittel einzulaufen, ich muss nicht immer Hose oder Shirt wegschmeißen uns neu kaufen und so weiter. Das Geld kann ich dann investieren, ist mehr als man denkt, wenn ich so die Ausgaben von Freunden betrachte.
Mal ehrlich, beim Thema Finanzen denken viele von uns doch zuerst ans Sparen, weniger ans Ausgeben, oder? Der Abschnitt über die Erhöhung der Sparquote im Artikel hat mich schon zum Nachdenken gebracht. Sicher, sparen ist wichtig, aber manchmal könnte ein bisschen mehr Ausgeben, gerade in Richtung Weiterbildung oder Qualitätsprodukte, die einem lange erhalten bleiben, nicht auch eine Art von Investition sein?
Vielleicht ist es ja ein Balanceakt – nicht nur die Sparquote erhöhen, sondern auch gezielt in Dinge investieren, die uns auf lange Sicht weiterbringen.