
 Newsletter
Why does a broadly diversified portfolio beat the supposedly smartest stock tip? The answer lies in one of the most powerful concepts of modern finance theory – and in the only genuine “free lunch” in investing. In this third lesson of our financial guide, you will learn how to use diversification effectively in two stages, where its limits lie and what this means for building your wealth.
< Lesson 2 | Overview | Lesson 4 >

In a nutshell
- Diversification is the only “free lunch” in investing: you get the same return potential with less risk.
- Before you invest, you should meet two basic requirements: an emergency fund covering three to six months of expenses and no outstanding consumer loans.
- Stage 1: Spread your equities globally and across sectors – this eliminates company-specific risk.
- Stage 2: If you want to go one step further, combine different asset classes – bonds and alternative investments such as real estate can reduce fluctuations or open up additional return opportunities.
- With the core-satellite approach, you keep discipline in the foundation and leeway for targeted positions in the satellite.
- Stock picking can boost returns – but can also lead to a total loss. That is why diversification is generally the more promising path – and it is scientifically sound.
Contents
- Resisting the temptation of stock picking
- What is behind diversification? The theory in a nutshell
- Diversification in practice – two stages
- The pragmatic middle way: the core-satellite approach
- The honest downside: diversification vs. concentration
- Conclusion
- You might also be interested in
- Updates
- Disclaimer
Resisting the temptation of stock picking
Admittedly, it is not easy to resist the supposedly safe stock tip with rosy profit prospects from your circle of friends. But it is necessary all the same!
“Hunting for individual stocks, also known as stock picking, can backfire badly.”
If you invest in an individual stock, substantial price losses with no prospect of a lasting recovery are unfortunately an all too realistic scenario. And this affects not only exotic stocks, but also well-known and established Swiss companies.
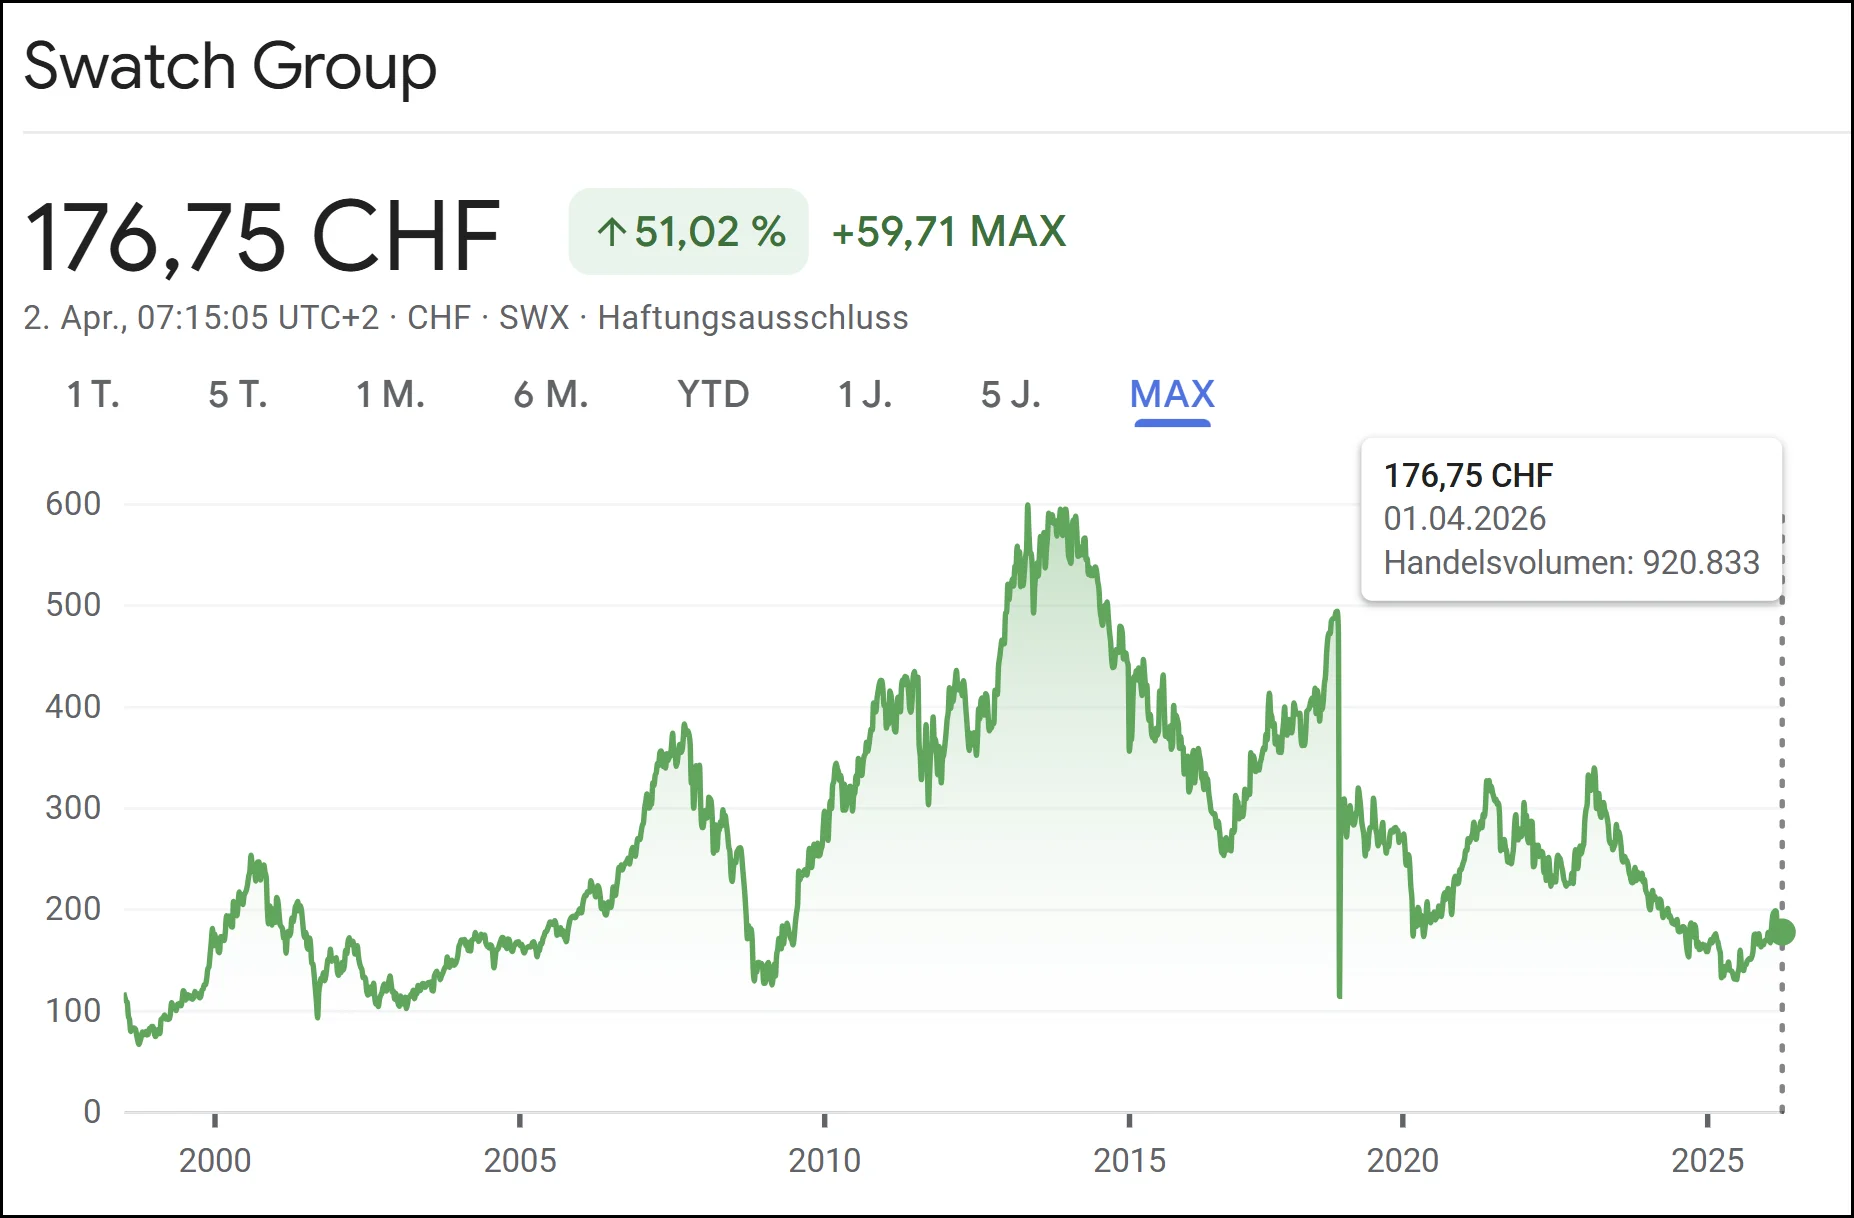
The Swatch Group, once a popular stock on the Swiss stock exchange, has lost around 70% of its value since its peak in November 2013 – as the chart impressively shows.
The worst case is even more drastic: bankruptcy. Swissair, once the nation’s proud airline, was grounded in October 2001 – shareholders lost everything. Investors in Credit Suissefared little better: once one of the largest banks in the world, it was taken over by UBS in an emergency deal for very little money in March 2023 after a crisis of confidence. Shareholders lost practically everything.
By the way, the opposite of stock picking is not necessarily passive investing – actively managed funds also often hold hundreds of stocks and are therefore broadly diversified. The real counter-concept is concentration on a few stocks. And it is precisely this concentration that increases risk – without increasing returns.
But concentration does not only show up in stock picking. If you keep all your wealth in a savings account, you are also concentrating on a single type of investment – with the difference that the threat here is not price losses but a gradual loss of purchasing power due to inflation. And the compound interest effect, which makes the decisive difference in the long run, remains practically ineffective. We showed how big this difference is over decades in Lesson 1 .
You will find out in the next chapter how diversification solves this risk – and what science has to say about it.
What is behind diversification? The theory in a nutshell
This brings us to the Modern Portfolio Theory (MPT) by Harry Markowitz. He received the Nobel Prize in Economic Sciences in 1990 for his groundbreaking doctoral thesis.
Markowitz was the first to provide theoretical proof of the positive effect of diversification on the risk and return of an overall portfolio. At the core of his theory is the distinction between systematic and unsystematic risk.
All securities on the market are exposed to systematic risk – i.e. market risks such as rising interest rates, recessions or political instability. It cannot be diversified away and is simply the price of investing itself.
Unsystematic risk, on the other hand, is company-specific risk – such as management failures like in the VW emissions scandal. This risk can be reduced through diversification. And that is the crucial point: the market compensates you for systematic risk – but not for unsystematic risk. So if you bet on individual stocks, you take on unnecessary risk without being able to expect a higher return for it.
“Company-specific risk can be reduced through diversification – market risk cannot.”
You achieve the strongest diversification effects by combining investments with the lowest possible correlation . The range extends from +1 (identical movement) through 0 (independent movement) to –1 (opposite movement). Within the equity asset class, typical correlations are between 0.70 and 0.95 – the effect is real, but limited. Combining different asset classes brings much more, as we will see below.
The efficient frontier: what makes an optimal portfolio
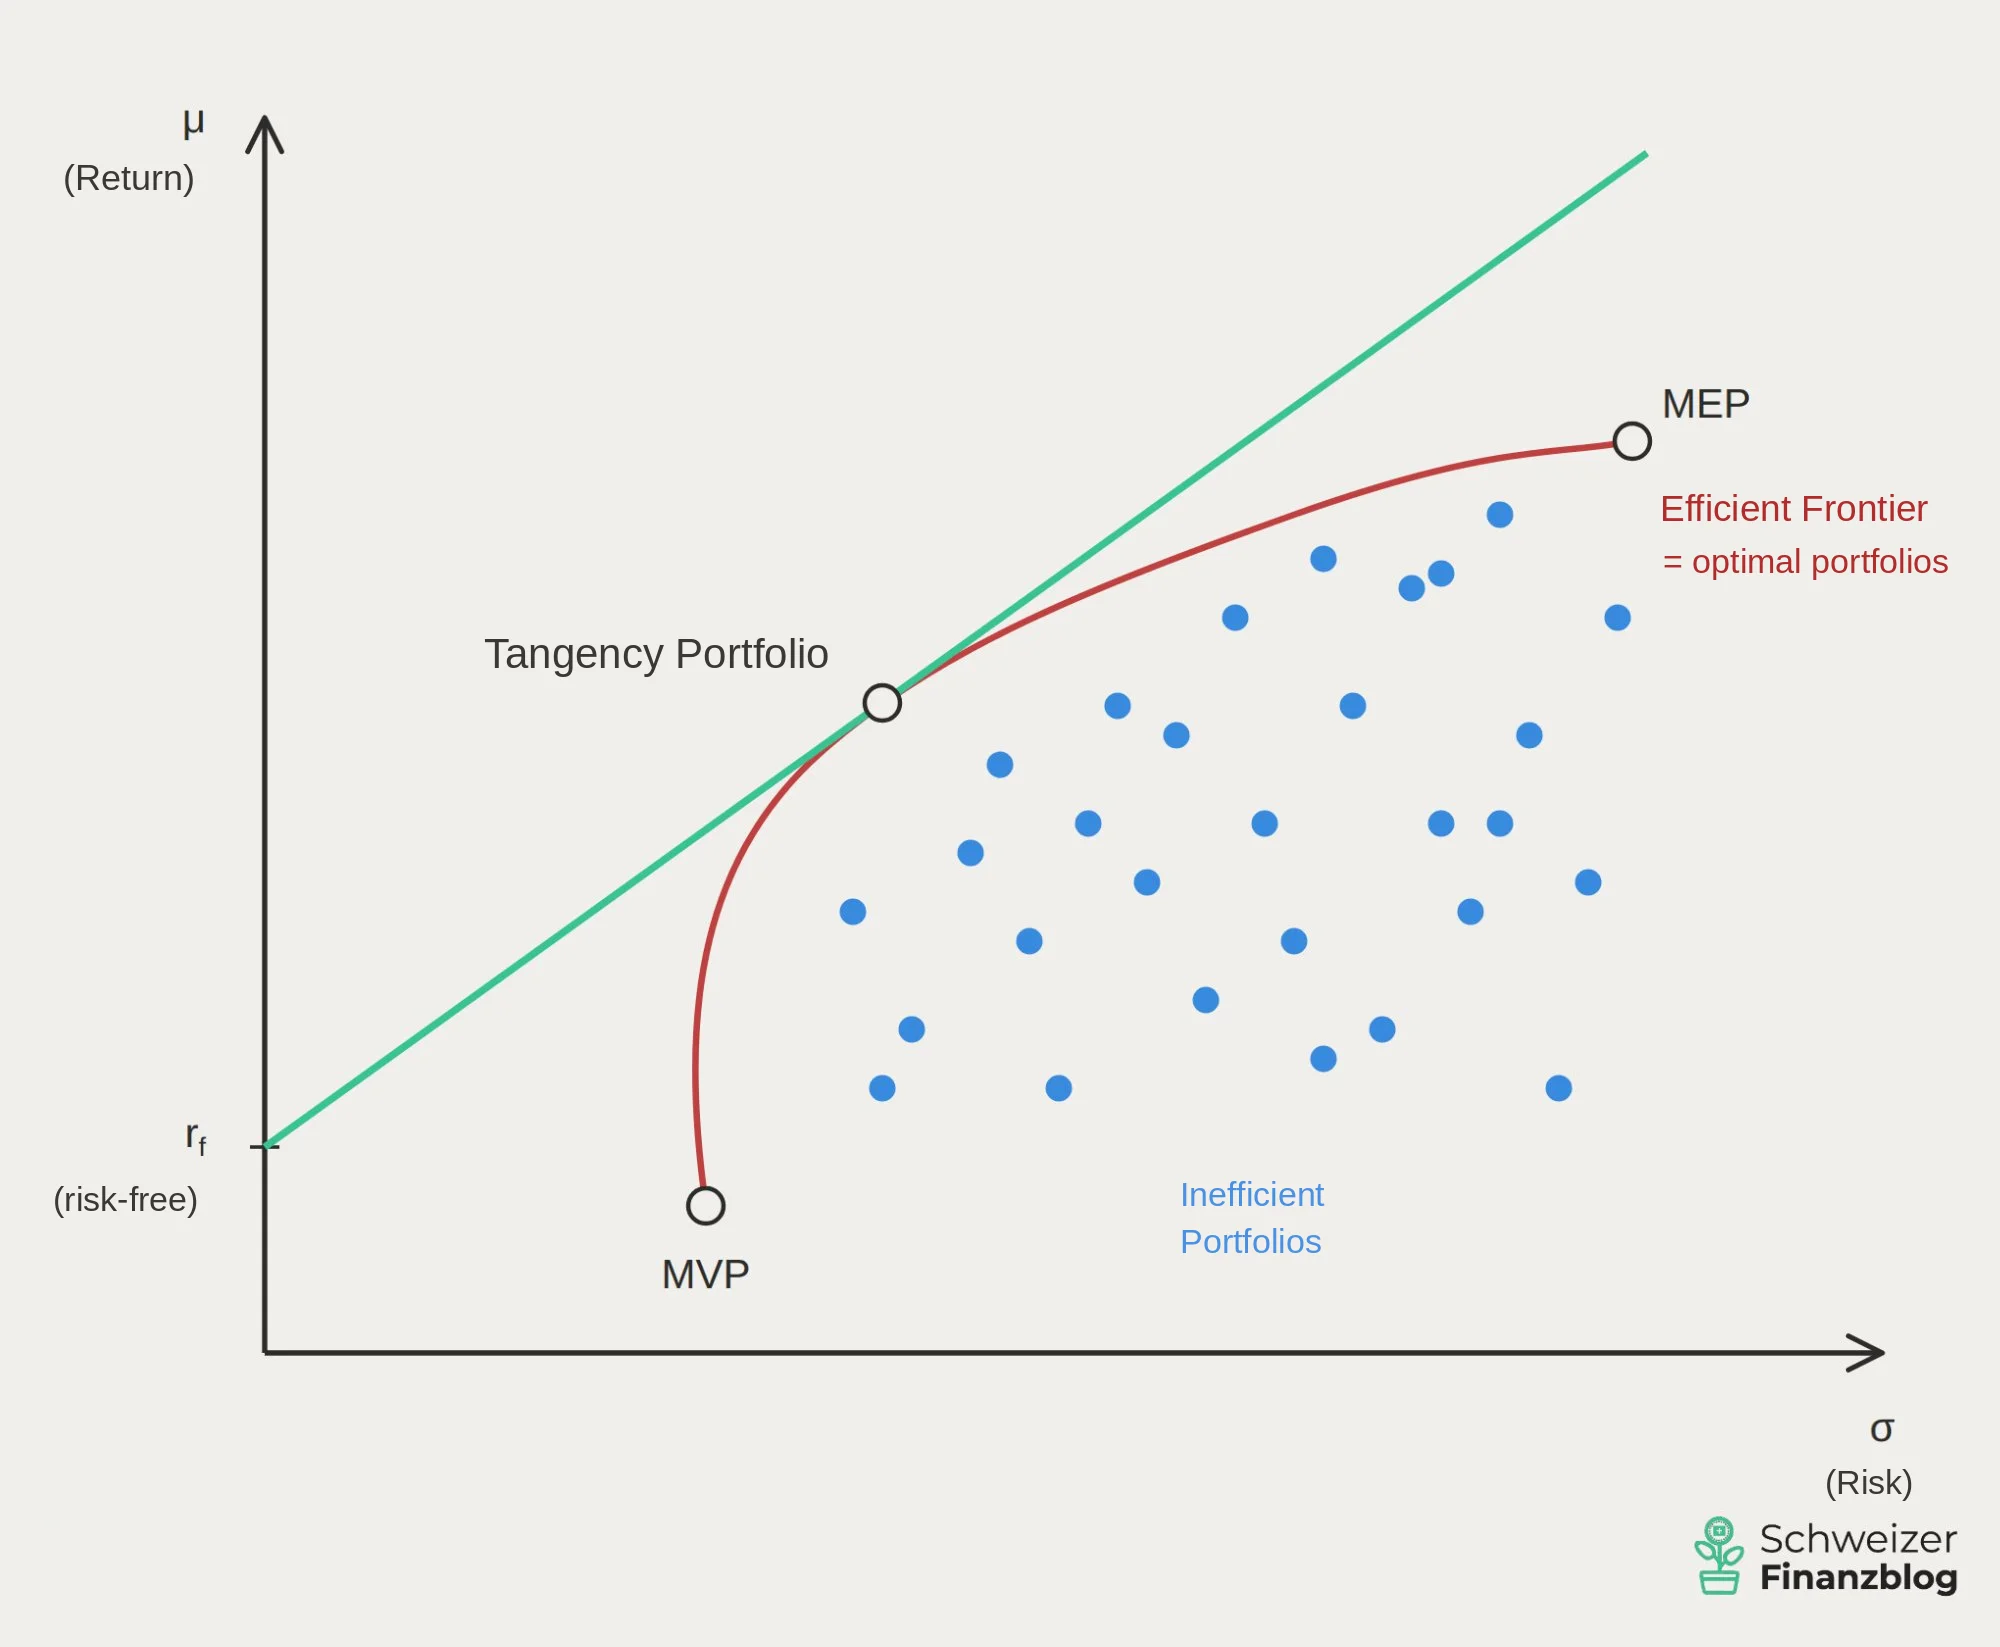
Markowitz not only showed that diversification reduces risk – he also specified the minimum amount of risk that has to be taken for a given return. The result is the efficient frontier (German: Effizienzlinie).
The efficient frontier is created by plotting all conceivable portfolio combinations on a chart – with risk on the X-axis and expected return on the Y-axis.
Portfolios on the curve are efficient: they achieve the maximum possible return for a given risk. Portfolios below it are inefficient – too much risk for too little return. Portfolios above the curve are simply not attainable.
“Diversification is the only free lunch in investing: the same expected return – but less risk.”
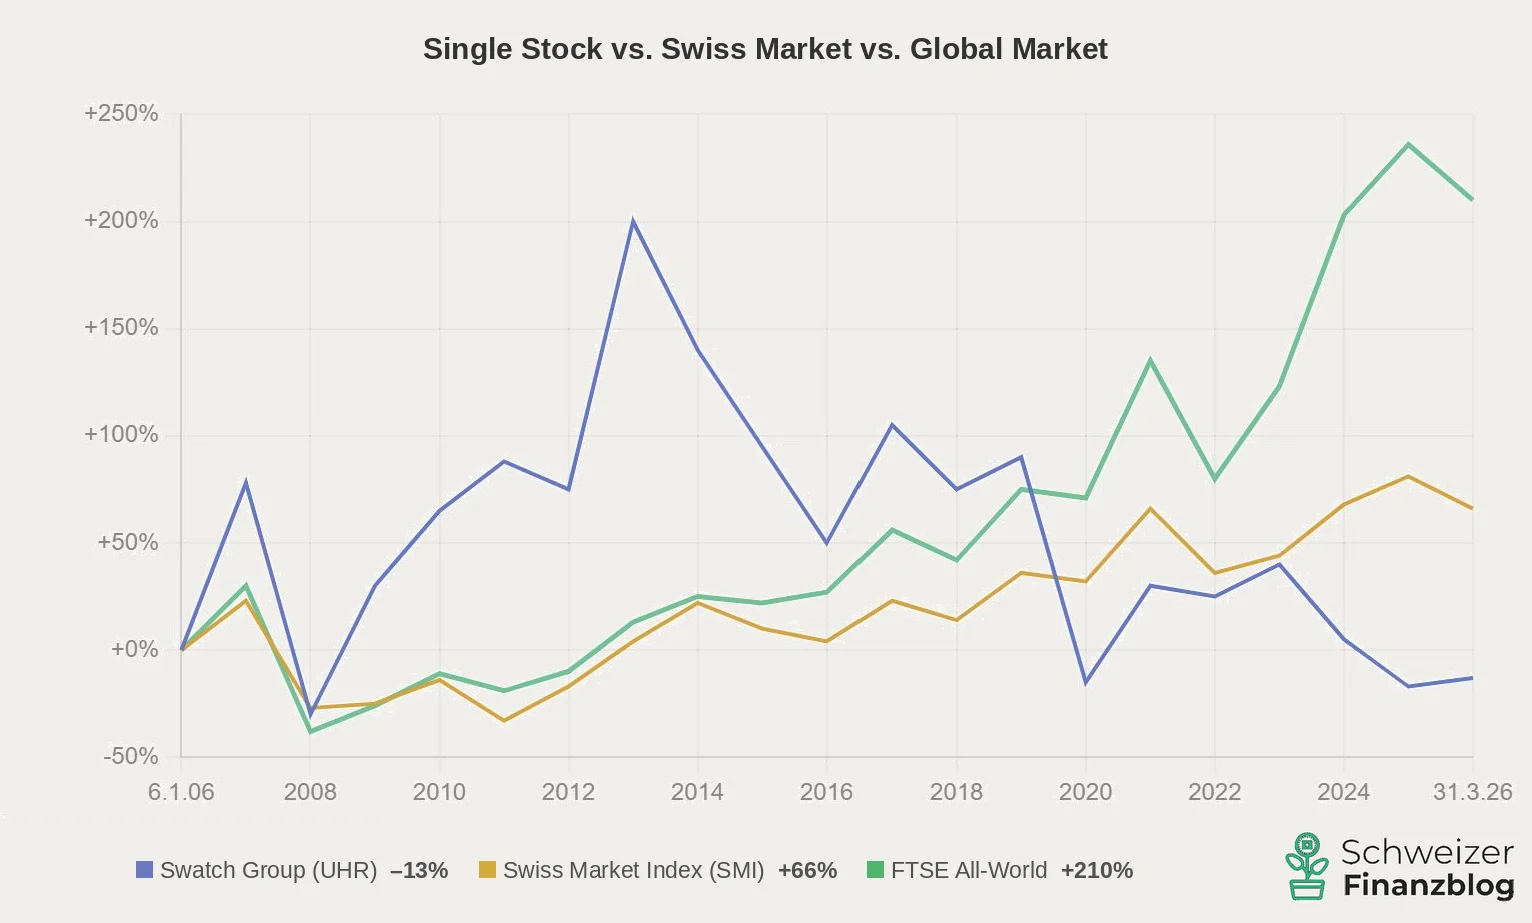
A global equity ETF such as the FTSE All-World is close to the MEP – the maximum return portfolio at the upper end of the efficient frontier. A single stock such as Swatch Group, on the other hand, lies to the right outside the curve: with the same or even lower expected return, you bear significantly more risk – without being compensated for it. That is exactly the “free lunch” of diversification: not more return, but less risk for the same expected return.
Diversification in practice – two stages
Theory is all well and good – but how do you actually put diversification into practice? And how far do you have to go? The old stock market wisdom that you should not put all your eggs in one basket comes in two stages. But first, you should meet one important requirement.
The emergency fund. Before you invest, you should keep bank savings covering three to six months of expenses as a liquidity reserve. This reserve serves to cushion unforeseen expenses – for example in the event of job loss, illness or repairs – without you having to touch your investments. Paying off any consumer loansalso takes priority, as their interest exceeds any realistic investment return. Only once you have built up this reserve and are free of consumer debt can you invest the rest of your wealth for the truly long term.
Stage 1 – Diversification within the equity asset class
Let us start with the most important level: spreading your equities widely. A simple rule of thumb helps you find your bearings:
- No-go: individual stocks
If you hold only one share, you bear the full company-specific risk. A total loss – as with Swissair – is not a theoretical scenario. - Suboptimal: a few Swiss stocks
Many people tend to overweight domestic equities – the so-called home bias. Understandable, but structurally problematic: the Swiss market is heavily concentrated in three sectors (pharma, financials, consumer goods) and accounts for less than 3% of global market capitalisation. - Recommended: global and across sectors
A global ETF on the FTSE All-World or MSCI ACWI covers thousands of companies from all over the world. Company-specific risk is practically eliminated – and whether individual companies rise in the index or disappear simply need not concern you.
Caution: limited concentration risk even in ETFs
If you buy an MSCI World ETF and think you are perfectly diversified, you should take a closer look: around 70% of the index is made up of US equities, with over 20% in the seven largest technology companies alone – the “Magnificent Seven” (source: MSCI, as of April 2026). In addition, the MSCI World only covers large and mid-sized companies in developed markets – emerging markets such as China, India or Brazil are not included. If you want genuine geographical diversification, you have two options: either add an emerging markets allocation with a separate ETF, or go straight for an MSCI ACWI or FTSE All-World, which already include emerging markets. If you want to go one step further, you can also add a small-cap ETF to your portfolio – and thereby also capture smaller companies.
Lawmakers also have diversification rules: for UCITS funds – the standard structure of most ETFs available in Switzerland – the so-called 5-10-40 ruleapplies: no single position may exceed 10% of the fund’s assets, and all positions above 5% may not account for more than 40% in total. UCITS is not a must, but a quality label intended to protect investors. Other ETFs – such as those that track the best-known Swiss index, the SMI – do not meet the requirements, as Nestlé, Novartis and Roche together regularly account for more than 50% of the index. So if you want to invest in a well-diversified way, you should look out for the UCITS label.
Digression: currency risk – an issue for Swiss investors
When you invest globally, you automatically invest in foreign currencies – around 60% of a FTSE All-World consists of US dollar stocks. What matters is not whether you buy your ETF in CHF or USD, but in which currency areas the companies in the fund operate.
Is that a reason to forgo global diversification? No. In the long run, the benefits of diversification clearly outweigh the drawbacks, and currency fluctuations partly even out over time. ETFs with currency hedging (“hedged”) do exist, but they cost more and eat into returns over the long term. For most investors with a long horizon, currency risk is simply something to live with – and part of the package.
Conclusion on diversification stage 1
Combined with a solid liquidity reserve in your bank account, you are already well positioned with stage 1 – a global equity ETF covers the essentials. But if you want to go one step further – reducing fluctuations or opening up additional return opportunities – you combine different asset classes. That is stage 2.
Stage 2 – Diversification across asset classes
Even more effective than spreading within equities is combining different asset classes – because their correlations with each other are significantly lower than within the equity asset class. While equities from different markets still show correlations of 0.70 to 0.95, correlations between equities and other asset classes are often much lower – sometimes close to zero or even negative. However, correlations are not fixed; they can shift over time. The lower the correlation, the greater the diversification effect.
Bonds
Bonds – in Switzerland usually called Obligationen – often move in the opposite direction to equities. In times of crisis, bond prices rise when everyone is looking for safety. However, this does not always apply: in 2022, both equities and bonds lost massive value when central banks raised interest rates drastically. So bonds are not a panacea, but they can be a valuable portfolio anchor over long periods.
A classic example is the 60/40 portfolio: 60% global equities, 40% bonds. For decades, it has been considered a proven starting point for people with a balanced investment approach – more stability, but also lower returns than a pure equity investment. If you have a long investment horizon and are aiming for maximum growth, you will see bonds as a brake on returns. The right weighting ultimately depends on your individual risk profile – which is exactly the topic of the next lesson.
Alternative investments as an add-on
If you want to expand your portfolio beyond the classic asset classes, you will find further sources of diversification among alternative investments – with different return, risk and liquidity profiles.
- Real estate
Real estate ETFs are the most accessible way into “bricks and mortar” – without a mortgage, a condominium owners’ association or administrative hassle. They provide ongoing income, but are sensitive to interest rate changes and are not completely decoupled from the stock markets. - Commodities
Gold, oil and industrial metals often act as a hedge against inflation and have low correlations with equities. Gold in particular has behaved as a safe haven in many crises. However, commodities do not generate ongoing income such as dividends or interest. - Crowdlending
P2P lending – lending directly to private individuals or SMEs via online platforms – can generate attractive returns. But the risks are real: during the 2020 coronavirus crash, several platforms froze withdrawals, and at Estateguru, returns for many fell from double digits to close to zero – high default rates on German real estate loans continue to weigh on the platform to this day. Conceivable as a small add-on for risk-takers, but not as a core building block. - Collectibles
Collector’s items – art, watches, whisky, sports cards – are considered inflation-resistant and have little correlation with the financial markets. Platforms such as Splint Invest let you invest from as little as EUR 50. The downsides: low liquidity, assets that are hard to value and no ongoing income. - Cryptocurrencies
Bitcoin & Co. are among the most volatile asset classes of all – if you invest here, you should be able to withstand strong fluctuations and only use money you could do without in an extreme case.
Conclusion on diversification stage 2
All asset classes can usefully complement your portfolio – but none replaces the stable foundation of diversified equity ETFs. The golden rule: the more exotic the investment, the smaller its weighting should be.
The pragmatic middle way: the core-satellite approach
The core-satellite approach elegantly resolves the apparent dilemma between diversification and concentration. The idea is simple:
- Core – 70–100% of the portfolio
One or two broadly diversified ETFs – such as MSCI ACWI or FTSE All-World – form the stable foundation. There is no speculation here; this is where wealth is built over the long term. People with a more defensive risk profile can also add bonds to the core. - Satellite – optional 0–30%
This is where there is room for targeted positions – individual countries or sectors, factor ETFs, individual stocks or alternative investments such as real estate ETFs, P2P lending, collectibles or crypto. These positions can beat the market, but they do not have to. Losing them does not jeopardise the overall portfolio.
The decisive advantage: you keep the discipline of diversification at the core without giving up the fun of active investing. And you always know what is at stake.
The honest downside: diversification vs. concentration
Here comes a point that finance blogs often keep quiet about because it seems to undermine the main message. But it is part of the truth:
Exceptional returns come from concentration, not diversification.
Warren Buffett achieved his excess returns because he bet heavily on a few carefully selected companies. Private equity funds – if they outperform the market at all – also do so through concentrated bets. Anyone who had bet everything on Nvidia or Apple in the past would be rich today.
That sounds tempting – but it is not a realistic path for the vast majority. And for one simple reason: concentration increases not only the opportunities, but the risks to the same extent. For every Buffett, there are hundreds who backed the wrong horse and suffered total losses. Excess returns through concentration require sound analysis, a robust psychological profile, a lot of time – and above all a considerable amount of luck.
For most private investors, the following therefore applies: diversification is not the path to super returns – but it is the path to solid, risk-adjusted returns over decades. And that is exactly what sustainable wealth building means in practice.
– Partner offers –
Still looking for the right financial solution? Our recommendations – with attractive welcome bonuses.
– – – – –
Conclusion
Diversification is not a lazy compromise – it is the only proven “free lunch” in investing: the same return potential, less risk. If you pile up individual stocks, you take on unnecessary risk without corresponding compensation in returns. And if you park your wealth in a savings account, you may avoid price fluctuations – but you pay a different price: a gradual loss of purchasing power due to inflation and missed compound interest.
Even the first stage – a global equity ETF combined with a solid liquidity reserve – forms a sound foundation. If you want to go further, you also diversify across different asset classes – with a sense of proportion.
The core-satellite approach combines the best of both worlds: a stable foundation thanks to diversification and room for targeted positions thanks to controlled concentration.
In the fourth lesson of this financial guide, we pick up exactly where we left off and turn to asset allocation – in other words, how to spread your total wealth across the various asset classes in line with your individual risk profile.
You can find an overview of all lessons here: Learn to invest – in eight lessons.
You might also be interested in
Updates
2026-06-12: Explained the 5-10-40 rule in more detail and made minor adjustments.
2026-05-18: Added commodities and cryptocurrencies to the alternative asset classes.
2026-04-06: Article completely revised and updated.
Disclaimer
Disclaimer: Investing involves the risk of loss. You must decide for yourself whether or not you want to take these risks.
Errors excepted: We have written this article on diversifying your investments to the best of our knowledge and belief. Our aim is to provide you as a private investor with information on finance that is as objective and meaningful as possible. Should we nevertheless have made mistakes, forgotten important aspects and/or if information is no longer up to date, we would be grateful if you let us know.
About the authors
Stefan Huser
Stefan has been investing in the stock market himself since 2015. He has been shaped by Markowitz’s portfolio theory and Gerd Kommer’s book “Souverän investieren”. He follows a core-satellite strategy: a global equity portfolio of ETFs forms the core, complemented by alternative investments. At the blog, he mainly takes care of the writing. Stefan lives with his family in Zurich and is interested in literature, photography and financial freedom.
Antun Brcina
Antun (“Toni”) has been investing in the stock market since 2015. Financially, he has been particularly inspired by Gerd Kommer’s book “Souverän investieren” and the Fama-French five-factor model. His money is invested in a broadly diversified, long-term global equity portfolio of ETFs. At the blog, he mainly works on the calculators and the code. Toni lives with his family in the Zurich area and is interested in sports, technology and entrepreneurship.

8 Comments
Der Artikel ist wirklich sehr gelungen. Die Struktur ist klar, die Beispiele (Swatch, Swissair, Credit Suisse) treffen es auf den Punkt, und der Ehrlichkeit-Abschnitt zu Konzentration vs. Diversifikation hebt den Artikel nochmal ab. Das liest man nicht überall.
Weiter so!
Ein sehr gelungener und wichtiger Beitrag! Gerade in Zeiten, in denen an jeder Ecke vermeintliche „Geheimtipps“ für einzelne Aktien gehandelt werden, ist es entscheidend, die Risiken des Stock-Pickings realistisch einzuschätzen. Der Artikel erinnert eindrücklich daran, dass selbst traditionsreiche Schweizer Unternehmen wie Zürich Versicherung oder UBS keine Garantie für stabile Renditen sind.
Die klare Erklärung der Modernen Portfoliotheorie zeigt zudem, dass Diversifikation kein theoretisches Konzept ist, sondern in der Praxis über langfristigen Anlageerfolg entscheidet. Besonders gut gefällt mir der Hinweis auf den Unterschied zwischen systematischem und unsystematischem Risiko – ein Punkt, den viele Privatanleger oft unterschätzen.
Ich stimme der Kernaussage voll zu: Stock-Picking ist mehr Spekulation als Investition. Wer langfristig Vermögen aufbauen will, sollte breit diversifizieren – am besten global und über verschiedene Assetklassen hinweg. So wird aus Risiko-Reduktion eine echte Strategie.
Vielen Dank für den fundierten Kommentar! Es freut uns sehr, dass die Bedeutung der Diversifikation so klar rübergekommen ist – genau das wollten wir mit dem Beitrag erreichen.
Hallo zusammen
Wäre das ein gutes Portfolio bez. der Diversifikation?
60% HSBC MSCI World (IE00B4X9L533)
20% HSBC EURO STOXX 50
(IE00B4K6B022)
20% UBS MSCI Switzerland
(CH0226274246)
Gruss und Danke für das Feedback
Hoi Erwin
Mit dem MSCI World bist du in über 1600 Aktien der entwickelten Welt investiert, weshalb du alleine mit diesem Produkt sehr gut diversifiziert bist. Bei den anderen beiden Produkten erreichst du keine zusätzliche Diversifikation, da die Aktien dieser ETFs bereits im MSCI World enthalten sind. Möglicherweise ist es aber dein Wunsch, die Eurozone im Allgemeinen und die Schweiz im Speziellen bei deiner Anlage besonders stark zu gewichten (d.h. stärker als die entsprechende Marktkapitalisierung der Aktien aus der Eurozone und der Schweiz).
Was unseres Erachtens in deiner Aufstellung fehlt, sind die Emerging Markets, womit du Aktien von zusätzlichen 25 Ländern erreichst. Auch kannst du dir überlegen, ergänzend noch die “Small Caps” zu berücksichtigen, womit du dann – was die Anlageklasse Aktien betrifft – extrem gut diversifiziert wärest.
Beste Grüsse
SFB
Hallo zusammen
Vielen Dank für das Feedback.
Genau das war meine Idee/Wunsch mit Europa und der Schweiz, da ich davon ausgehe, dass die Wirtschaft in Europa sich in den nächsten Jahren besser entwickeln wird.
Bei dem Emerging Markets weiss ich nicht so recht. Dieser ist mir fast zu “China” lastig. Ansonsten wäre es eine Möglichkeit den MSCI World durch den iShares MSCI ACWI UCITS ETF (Acc) zu ersetzen. Somit hätte ich die Schwellenländer auch mit drin.
Beste Grüsse
…ja genau, den MSCI World ETF durch einen ETF ersetzen, welcher auf dem Index MSCI ACWI oder FTSE All-World (von Anbieter Vanguard) basiert, wäre ein prüfenswerte Option…
Paranoid vor einem Crash muss man nicht sein, doch wer sich nicht absichert und seine Asset Allocation absichert ist selbst schuld. Man kann weiter investieren und Investments halten die bei einer Rezension stark steigen. Auch andere Währungen wie der Schweizer Franken können eine Lösung sein.