By Stefan Huser and Antun Brcina
Updated on
Your portfolio is set up, your asset allocation is fixed – and then the markets do whatever they like. Prices rise, fall, shift. Suddenly your portfolio no longer matches your risk profile. Does it have to be that way? Not necessarily. In this fifth lesson of our financial guide, you’ll learn how to get your wealth back in balance with little effort – and when you can skip it altogether.
< Lesson 4 | Overview | Lesson 6 >

In a nutshell
In the last lesson, you learned how to split your wealth into a high-risk and a low-risk portion. That lays the foundation of your portfolio. But the markets don’t stick to your plan: prices rise and fall, and the weightings shift with them. Rebalancing means restoring your original allocation.
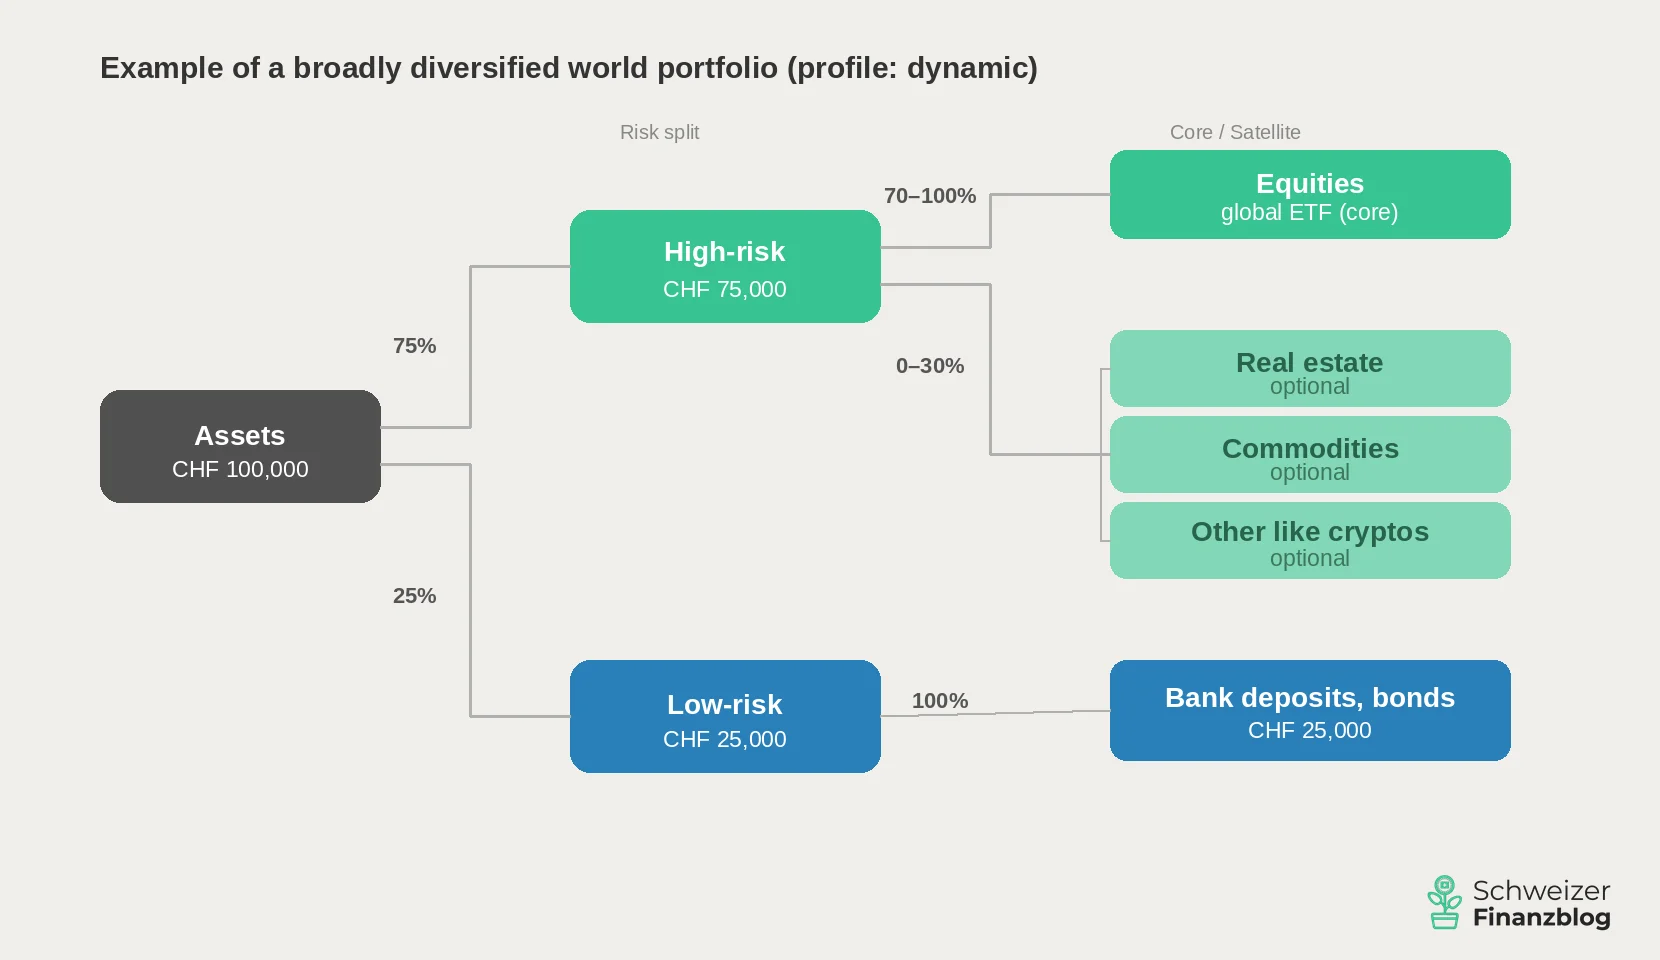
An example: you’ve invested CHF 100,000 – 75% high-risk, 25% low-risk.
Now the stock markets drop by 30%. Your high-risk portion falls from CHF 75,000 to CHF 52,500, while the CHF 25,000 in your savings account stays the same. Your total assets now come to CHF 77,500 – and the low-risk share is suddenly 32% instead of 25%. Your portfolio is much more conservative than you planned.
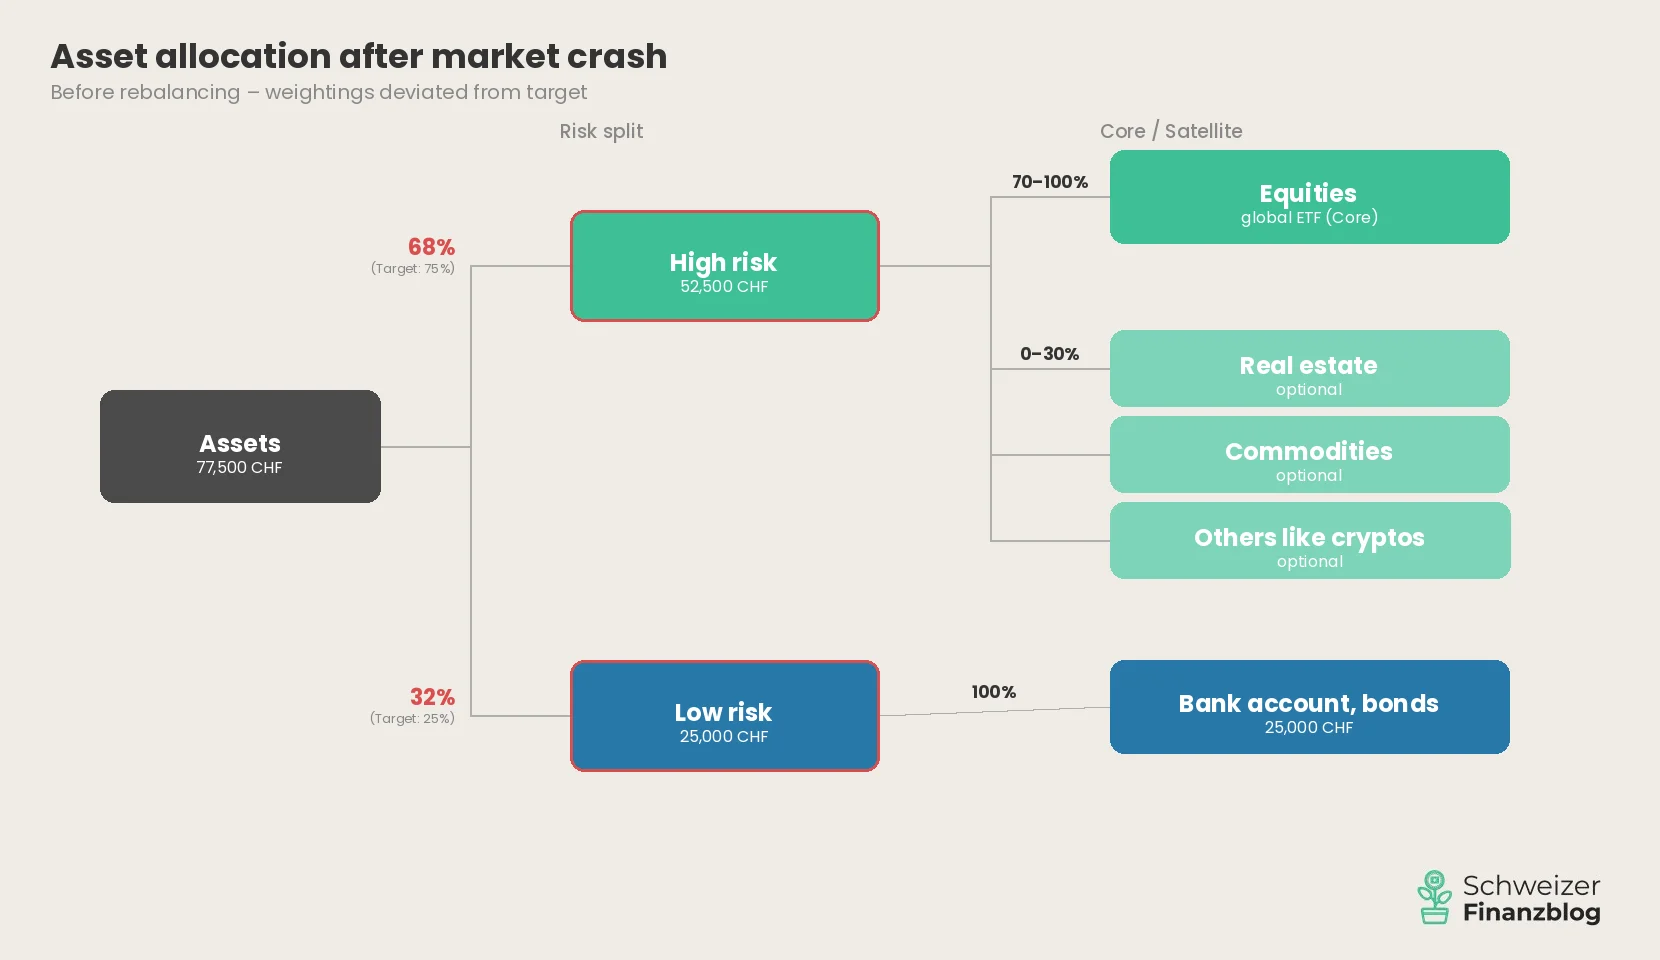
To get back to 75/25, you’d have to shift around CHF 5,600 from your savings account into the high-risk portion – right after a crash, of all times, when your gut is telling you not to. That’s exactly what rebalancing is: a sober, rule-based correction that brings your portfolio back in line with your risk profile.
But before you set up a rebalancing calendar: not every portfolio needs this correction. If you hold a single global ETF and define the low-risk portion as a fixed franc amount – e.g. CHF 25,000 in a savings account, not counting your emergency fund – you simply have nothing to rebalance. The ETF is continuously adjusted internally by the provider. And a fixed amount doesn’t shift, no matter what the markets do. In the same crash, your CHF 25,000 stays where it is. Your high-risk portion has shrunk, but your risk profile hasn’t changed – and that’s the logic behind the fixed franc amount. No action needed.
So rebalancing becomes relevant when the low-risk portion is defined as a percentage (as in the example above) or when the portfolio consists of several ETFs, for example in a core-satellite approach. In both cases, the weightings drift apart over time – and you have to actively readjust. Let’s now look at how to do that pragmatically and cheaply.
Two questions arise: when should you rebalance? And how?
In theory, there are two approaches: calendar-based and threshold-based. With the calendar-based approach, you review your portfolio at fixed intervals – say, once a year. With the threshold-based approach, you only act when a deviation exceeds a certain value, e.g. 5 percentage points.
In practice, you can combine both: you check your portfolio once or twice a year – and only step in if the deviation is large enough. That’s all it takes. Rebalancing isn’t a day-to-day job, but an occasional fine-tuning.
There are basically three methods for bringing your portfolio back to its target weighting:
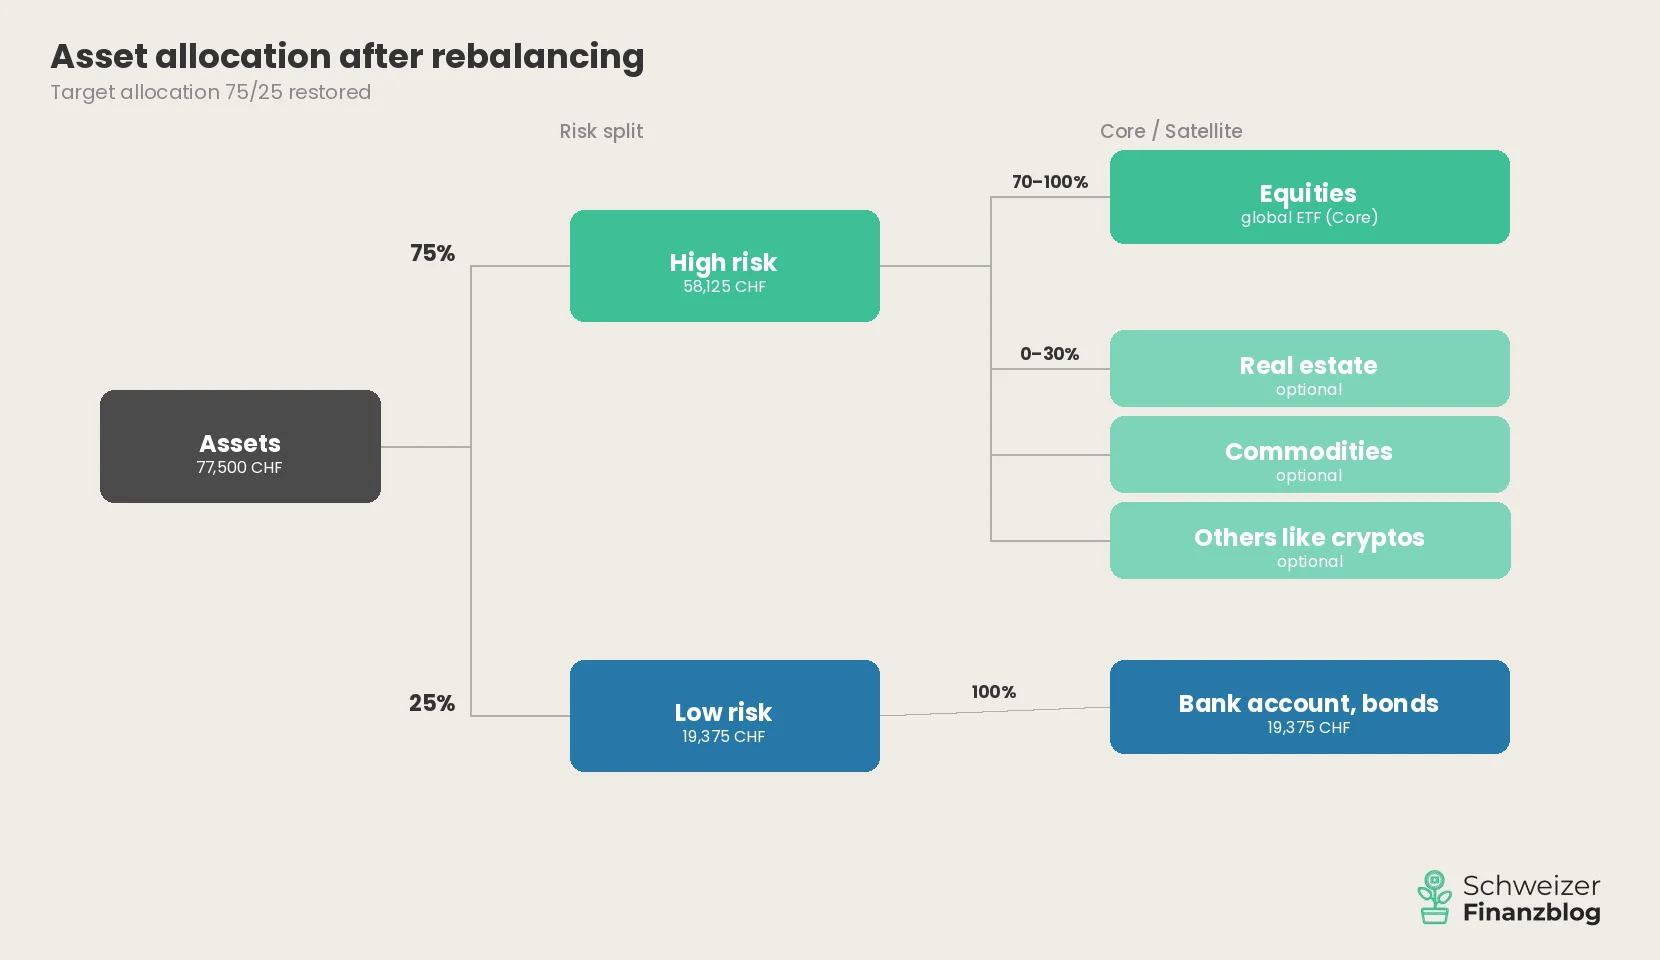
If you balance every position down to the last franc, you’ll pay unnecessarily high transaction fees – especially with smaller amounts. Focus on the biggest deviations. Once the overall split between the high-risk and low-risk portions is right again, you can safely ignore smaller imbalances within the high-risk portion. You’ll simply realign them with your next savings contribution. As a rule of thumb: if a position deviates from its target weighting by more than 5 percentage points, action is called for. Below that, the effort usually isn’t worth it.
The following chart shows what this looks like in practice.
Everything described so far relates to the accumulation phase – the period in which you build up your wealth. But even if you’re drawing on your wealth in retirement, you can rebalance. The principle is simply reversed: instead of steering new contributions, you first sell positions that are above their target weighting. That way, each withdrawal brings your portfolio closer to its target weighting – without additional transactions.
If you hold part of your wealth in Pillar 3: here, rebalancing is usually automated. You specify your risk profile once, and the provider takes care of the readjusting for you – often already included in the management fees. You still have to look after rebalancing your non-pension assets yourself, though.
For private investors in Switzerland, rebalancing generally has no tax consequences. Capital gains on private assets are tax-free. The only exception: if you trade so frequently and on such a large scale that the tax authorities suspect professional securities trading, your gains are taxed as income. With one or two rebalancing transactions a year, that’s not an issue.
The main goal of rebalancing is clear: your portfolio should match your risk profile again. But there’s a pleasant side effect known in the specialist literature as the rebalancing bonus.
The principle behind it is simple: when rebalancing, you systematically buy more of the investments that have fallen and trim those that have risen. In other words, you act countercyclically – and it’s precisely this behavior that can generate a small extra return over the long term. Various studies put this effect at around 0.1 to 0.5 percentage points per year.
The rebalancing bonus is not a law of nature. It works best when prices return to their average after swings – the so-called regression to the mean. In phases of long-lasting trends, on the other hand, rebalancing can hold you back because you sell winners too early. None other than Charlie Munger, Warren Buffett’s long-time partner, firmly rejected rebalancing for exactly this reason: anyone who systematically trims their winners slows the growth of their portfolio.
Then there are the transaction costs. At an expensive traditional bank, they quickly eat up the bonus. The rebalancing bonus is therefore only worth it with a low-cost online broker that charges low fees per transaction.
So: think of the bonus as a welcome extra, not a guarantee.
“The real case for rebalancing isn’t the extra return – it’s risk control.”
– Partner offers –
Still looking for the right financial solution? Our recommendations – with attractive sign-up bonuses.
– – – – –
Rebalancing isn’t a third major investment principle alongside diversification and asset allocation – it’s the maintenance that ensures your portfolio still matches your risk profile after market swings.
If you keep it simple – one global ETF and a fixed franc amount in a savings account – you don’t need to worry about it. For everyone else: check once or twice a year, readjust when deviations are larger, ideally via new contributions rather than sales. There’s no need for perfection – as long as the overall allocation is right, you can safely ignore smaller imbalances.
In Lesson 6, we take a closer look at the investment vehicle that keeps cropping up in this guide: the ETF. What’s behind it – and why do we speak of a revolution in private investing?
You can find an overview of all lessons here: Learn to invest – in eight lessons.
2026-06-12: Selective adjustments made.
2026-04-14: Article completely revised and updated.
Disclaimer: Investing involves the risk of loss. You have to decide for yourself whether or not you want to take on these risks.
Errors excepted: We wrote this article on rebalancing to the best of our knowledge and belief. Our goal is to give you, as a private investor, the most objective and meaningful information possible on all things finance. If we have nevertheless made mistakes, or if important aspects have been forgotten and/or are no longer up to date, we’d be grateful if you let us know.
How much of your money belongs in equities – and how much stays in your bank account? The answer is the most important decision you’ll make when investing. Not picking the right ETF, not the perfect moment to get in – but how you structure your assets. In this fourth lesson of our financial guide, you’ll learn how to determine your personal asset allocation step by step and what role your risk profile, your liquidity reserve and the third pillar play in it.
< Lesson 3 | Overview | Lesson 5 >
In a nutshell
Behind the term asset allocation lies a simple idea: structuring your assets. In concrete terms, it’s about how you spread your money across different asset classes – how much goes into equities, how much stays in your bank account and how much, if any, you put into real estate or other investments.
If diversification is the blueprint, then asset allocation – in other words, the structure of your assets – is the foundation of your house. It determines how solidly the building stands, not the colour of the walls or the model of the kitchen. Numerous studies confirm exactly this: it isn’t the choice of individual products but the way you split your assets that has the greatest impact on long-term investment success. Your asset allocation is what you align every other investment decision with.
Before we get into the details, it’s worth looking at the big picture. Your assets can be divided into three areas, each with a different job: the liquidity reserve as a safety net, the low-risk portion as an anchor of stability and the high-risk portion as the engine of returns.
Every sound financial plan includes a liquidity reserve – an emergency fund of three to six months’ expenses in your bank account. This reserve is there to cushion unforeseen expenses such as job loss, illness or major repairs without you having to touch your investments.
Even though the liquidity reserve also sits in your bank account at low risk, it is not part of your asset allocation. The difference: the low-risk portion of your investments is a deliberate strategic decision within your portfolio. The liquidity reserve, by contrast, is a prerequisite that has to be in place before you even think about investing. It’s reserved for emergencies – and therefore off-limits for investment purposes. Paying off any consumer loans also takes priority – their interest exceeds any realistic investment return.
Only what’s left after your emergency fund and paying off debt is your freely available investment capital. And it’s exactly this capital that you now structure through asset allocation.
How you split your freely available assets depends on your individual risk profile – that is, on the interplay between your risk tolerance and your risk capacity, which we covered in detail in Lesson 2.
A quick reminder: risk tolerance describes how much of a price loss you can stomach without lying awake at night or selling in a panic. Risk capacity describes how much loss your wallet can absorb without putting you in financial difficulty – determined by your financial situation and your investment horizon.
Both factors need to be in line. An example: you’re young, earn a good salary and could easily cope with a 50% price loss financially. But at minus 20% you get nervous and sell. In that case it’s not your risk capacity that counts but your risk tolerance – it sets the tighter limit. Conversely, if you see yourself as a risk-taker but want to buy a flat in three years, you should stick to your lower risk capacity. In short: whichever of the two factors is more cautious sets the limits.
Based on your risk profile, you divide your freely available investment capital into two parts: a high-risk portion and a low-risk portion. As a rule of thumb: the higher the equity share, the riskier – but also the higher-yielding – your portfolio.
Let’s assume a fictitious investment capital of CHF 100,000 – your emergency fund is already in place. You have a regular income and your running costs under control. Five typical ways to split your assets:
| Risk profile | High-risk* | Low-risk** | Historical return p.a.*** | Max. loss*** | Min. investment horizon |
|---|---|---|---|---|---|
| Defensive | 0–20% | 80–100% | 1–2% | up to –12% | 0–2 years |
| Conservative | 20–40% | 60–80% | 2–3% | up to –23% | 3–4 years |
| Balanced | 40–60% | 40–60% | 3–4% | up to –35% | 5–7 years |
| Dynamic | 60–80% | 20–40% | 4–5% | up to –46% | 7–9 years |
| Aggressive | 80–100% | 0–20% | 5–6% | up to –58% | 10+ years |
For the aggressive profile, we recommend an investment horizon of at least 10 years because of its high volatility. More conservative models with a low equity share, on the other hand, are also suitable for shorter periods.
The high-risk portion is the return engine of your portfolio – and its most important building block is equities.
“In the high-risk portion, there’s no way around equities.”
In concrete terms, it does four jobs:
ETFs that track broad market indices across all regions of the world are particularly well suited as investment vehicles. You’ll find out why we consider ETFs especially attractive for investing in Lesson 6.
The simplest and at the same time most elegant solution: with a single global ETF – such as the Vanguard FTSE All-World or an MSCI ACWI ETF – you invest in thousands of companies from developed and emerging markets, weighted by market capitalisation. One purchase, global diversification, minimal effort. That’s the core idea of passive investing – and the ideal starting point for most investors.
If you want to go beyond this foundation, you can apply the core-satellite approach from Lesson 3. The core – 70 to 100% of the high-risk portion – remains a broadly diversified equity ETF. If you like, you can fill the rest, up to a maximum of 30%, with targeted add-ons in the satellite:
Rule of thumb: the more exotic the investment, the smaller its weighting.
The low-risk portion is the anchor of stability in your portfolio – and a sedative for your nerves. When stock markets drop 30% yet again, this is the part that keeps you calm. In concrete terms, it does three jobs:
Bank deposits – in a savings or personal account – are the simplest and most liquid option. You can access them at any time. In Switzerland, deposits of up to CHF 100,000 per person and bank are protected by deposit insurance. The expected return is clear: at best some protection against inflation, but no real growth in wealth. That’s not this portion’s job anyway – it’s meant to give you security and room to act.
High-quality bonds – such as Swiss federal government bonds with a top “AAA” rating – also offer a high level of security. Historically, however, their return in Switzerland has been close to inflation. If you’re hoping for a meaningful return after inflation, Swiss bonds will usually disappoint you. Still, they can play a role as a stabiliser in a portfolio – especially for investors with a balanced or conservative profile.
Other options such as medium-term notes or fixed-term deposits offer a bit more return than a savings account, but tie up your capital for a fixed term. You’ll find an overview in Lesson 2.
“Setting your individual asset allocation, tailored to your risk profile, is the be-all and end-all of investing.”
A question we get again and again: where in my asset allocation does my 3a money actually belong – low-risk or high-risk?
Our answer: neither. Your 3a assets are tied-up retirement savings – you can’t simply withdraw them whenever you want. Early withdrawals are only possible in a few cases, such as buying a home, emigrating or becoming self-employed. That’s why Pillar 3a doesn’t belong in the same drawer as your freely available assets but follows its own rules.
That doesn’t mean you should ignore it, though – quite the opposite. If you still have 10, 20 or more years until retirement, you’re sitting on a huge compounding lever. And that’s exactly why we recommend investing your third pillar in equities. The biggest return killer? Fees. Traditional bank products often charge 1% or more per year – sounds like little, but over the long term it can add up to tens of thousands of francs in lost returns. Low-cost online providers with fees below 0.5% make a huge difference here.
– Partner offers –
Still looking for the right financial solution? Our recommendations – with attractive sign-up bonuses.
– – – – –
Asset allocation is the most important decision you make when investing – more important than the choice of individual products, more important than the timing of your entry, more important than whether you buy ETF A or ETF B. It’s your guiding star, the point you align every other investment decision with.
The principle is simple: first, secure your liquidity reserve. Then divide your freely available assets into a high-risk and a low-risk portion based on your risk profile. In the high-risk portion, broadly diversified equity ETFs form the core – if you like, you can add to them using the core-satellite principle. In the low-risk portion, bank deposits provide stability and a good night’s sleep. You look at your 3a assets separately – invested in equities and at low cost.
Write down your target allocation – so that you can monitor it periodically and take corrective action when needed. Because when equities rise or fall, the weighting shifts automatically. How to restore your original portfolio structure easily and at low cost is the topic of our next lesson: Rebalancing.
You’ll find an overview of all lessons here: Learn to invest – in eight lessons.
2026-06-12: Minor adjustments made.
2026-05-19: Table of historical returns and losses adapted to Swiss conditions (adjusted for inflation and currency).
2026-04-10: Article completely revised and updated.
Disclaimer: Investing involves the risk of loss. You have to decide for yourself whether or not you want to take on these risks.
Errors excepted: We have written this article on asset allocation to the best of our knowledge and belief. Our goal is to provide you, as a private investor, with information on financial topics that is as objective and meaningful as possible. If we have nevertheless made mistakes, or if important aspects have been forgotten and/or are no longer up to date, we’d be grateful if you let us know.

 X