
 Newsletter

neon has overhauled its offering: the entry-level plan without a basic fee now includes fewer services, while the paid plans offer additional benefits. At the same time, neon keeps expanding its ecosystem – including a newly launched Pillar 3a solution that is fully integrated into the app.
In this review, we share our experience with neon – from paying, saving and retirement saving to investing in ETFs, including a particularly interesting one with no purchase fees.

In a nutshell
neon is a Swiss neobank founded in 2017 that focuses on app-based paying, saving, investing and retirement saving via smartphone, with around 240,000 customers.
-
Account models & costs:
-
Four options: neon free, neon plus (CHF 20/year), neon global (CHF 80/year) and neon metal (CHF 150/year)
-
Low-cost card payments abroad with an FX mark-up of 0% to 0.35%, depending on the account model
- No multi-currency account
-
-
Investing & ETFs:
-
No custody or currency exchange fees, trading currency always CHF
-
ETF trades at 0.5% per transaction, particularly attractive for amounts up to around CHF 1,000
-
Selected ETFs – including the flagship Vanguard FTSE All-World – with no purchase fees in the savings plan
-
-
Retirement savings: Pillar 3a solution fully integrated into the app, with total costs of 0.39% to 0.45% p.a. – one of the cheapest on the Swiss market
-
Security: Swiss regulation with deposit insurance of up to CHF 100,000
Our experience with neon shows: If you want to handle banking, investing and retirement saving simply, digitally and cheaply on your smartphone and don’t need a multi-currency account, neon is a convincing solution.
🎁With our neon promo code neonSFB you get CHF 100 in trading credits.
Contents
- CHF 100 bonus – with promo code neonSFB
- What is neon?
- What does neon offer?
- Our experience with payments at neon
- neon services and prices for payments WITHOUT a card
- neon free services and prices for payments WITH a card
- Our experience with saving at neon
- Our experience with investing at neon
- neon Pillar 3a – simple and low-cost
- How good is neon’s support?
- How do I sign up with neon?
- How safe is neon?
- Why neon – and when Yuh might be the better choice?
- Final verdict from our neon review
- You might also be interested in
- Updates
- Disclaimer
CHF 100 bonus – with promo code neonSFB
If neon’s offer convinces you, you can claim the following welcome bonus:
🎁 CHF 100 in trading credits
This lets you invest up to CHF 20,000 free of fees. You also support our blog.
👉 Here’s how it works:
- Download the neon app to your smartphone and sign up.
- Enter the promo code neonSFB when you sign up.
- Transfer at least CHF 1 to your neon account to activate it.
- Once activated, you receive CHF 100 in trading credits – valid for your first three trades within two months.
📌 The fees are charged as usual after the trade and credited back after two working days.
Let’s get started with our neon review.
What is neon?
The Swiss smartphone bank was founded in 2017 with the aim of becoming Switzerland’s first independent account app. The guiding idea: unbeatably cheap, super simple and completely secure.
neon was set up by four founders: Jörg Sandrock, Julius Kirscheneder, Simon Youssef and Michael Noorlander. The official launch took place in March 2019.
With around 240,000 customers, neon is now one of the largest neobanks in Switzerland. This success is all the more remarkable because neon – unlike competitors such as Yuh or Zak – was not launched by deep-pocketed, established banks but by a handful of innovative minds with a comparatively small budget.
neon offers an attractive mix of banking services that you can add to individually to suit your taste.
What does neon offer?
neon’s range essentially covers four basic financial functions:
- Paying
- Saving
- Investing
- Retirement saving
In this review, we look at all four areas: we explain which services neon offers, assess how useful they are – and give each one a price tag. In keeping with our mission, we pay particular attention to investing.
Unique variety: four neon plans…
With its comprehensive relaunch in May 2025, neon is focusing even more than before on an offering tailored to individual needs, with no fewer than four different plans:
- neon free: “The digital everyday account for complete independence.” (no basic fee)
- neon plus: “The smart account with a plus in availability.”
- neon global: “The borderless account with extra protection online and on the go.”
- neon metal: “The exclusive account for a completely carefree lifestyle.”
Despite all the variety, the fact is that the new, paid neon plus plan includes services that used to be part of the free neon free plan:
- No currency exchange fees on card payments
- Two free cash withdrawals per month
- Phone support
neon free now charges a currency exchange fee of 0.35% – still attractive compared with the market, but a step back from the previous, unrivalled offer. Cash withdrawals at ATMs now also cost CHF 2.50 per transaction. For the latter, however, neon offers a valid alternative: free cash withdrawals are now possible at Coop, Aldi and Lidl with a minimum purchase of CHF 10.
“neon free” is nevertheless likely to remain the most popular plan, as it is the only one without a basic fee. The other three plans come at a cost and offer more service in return.
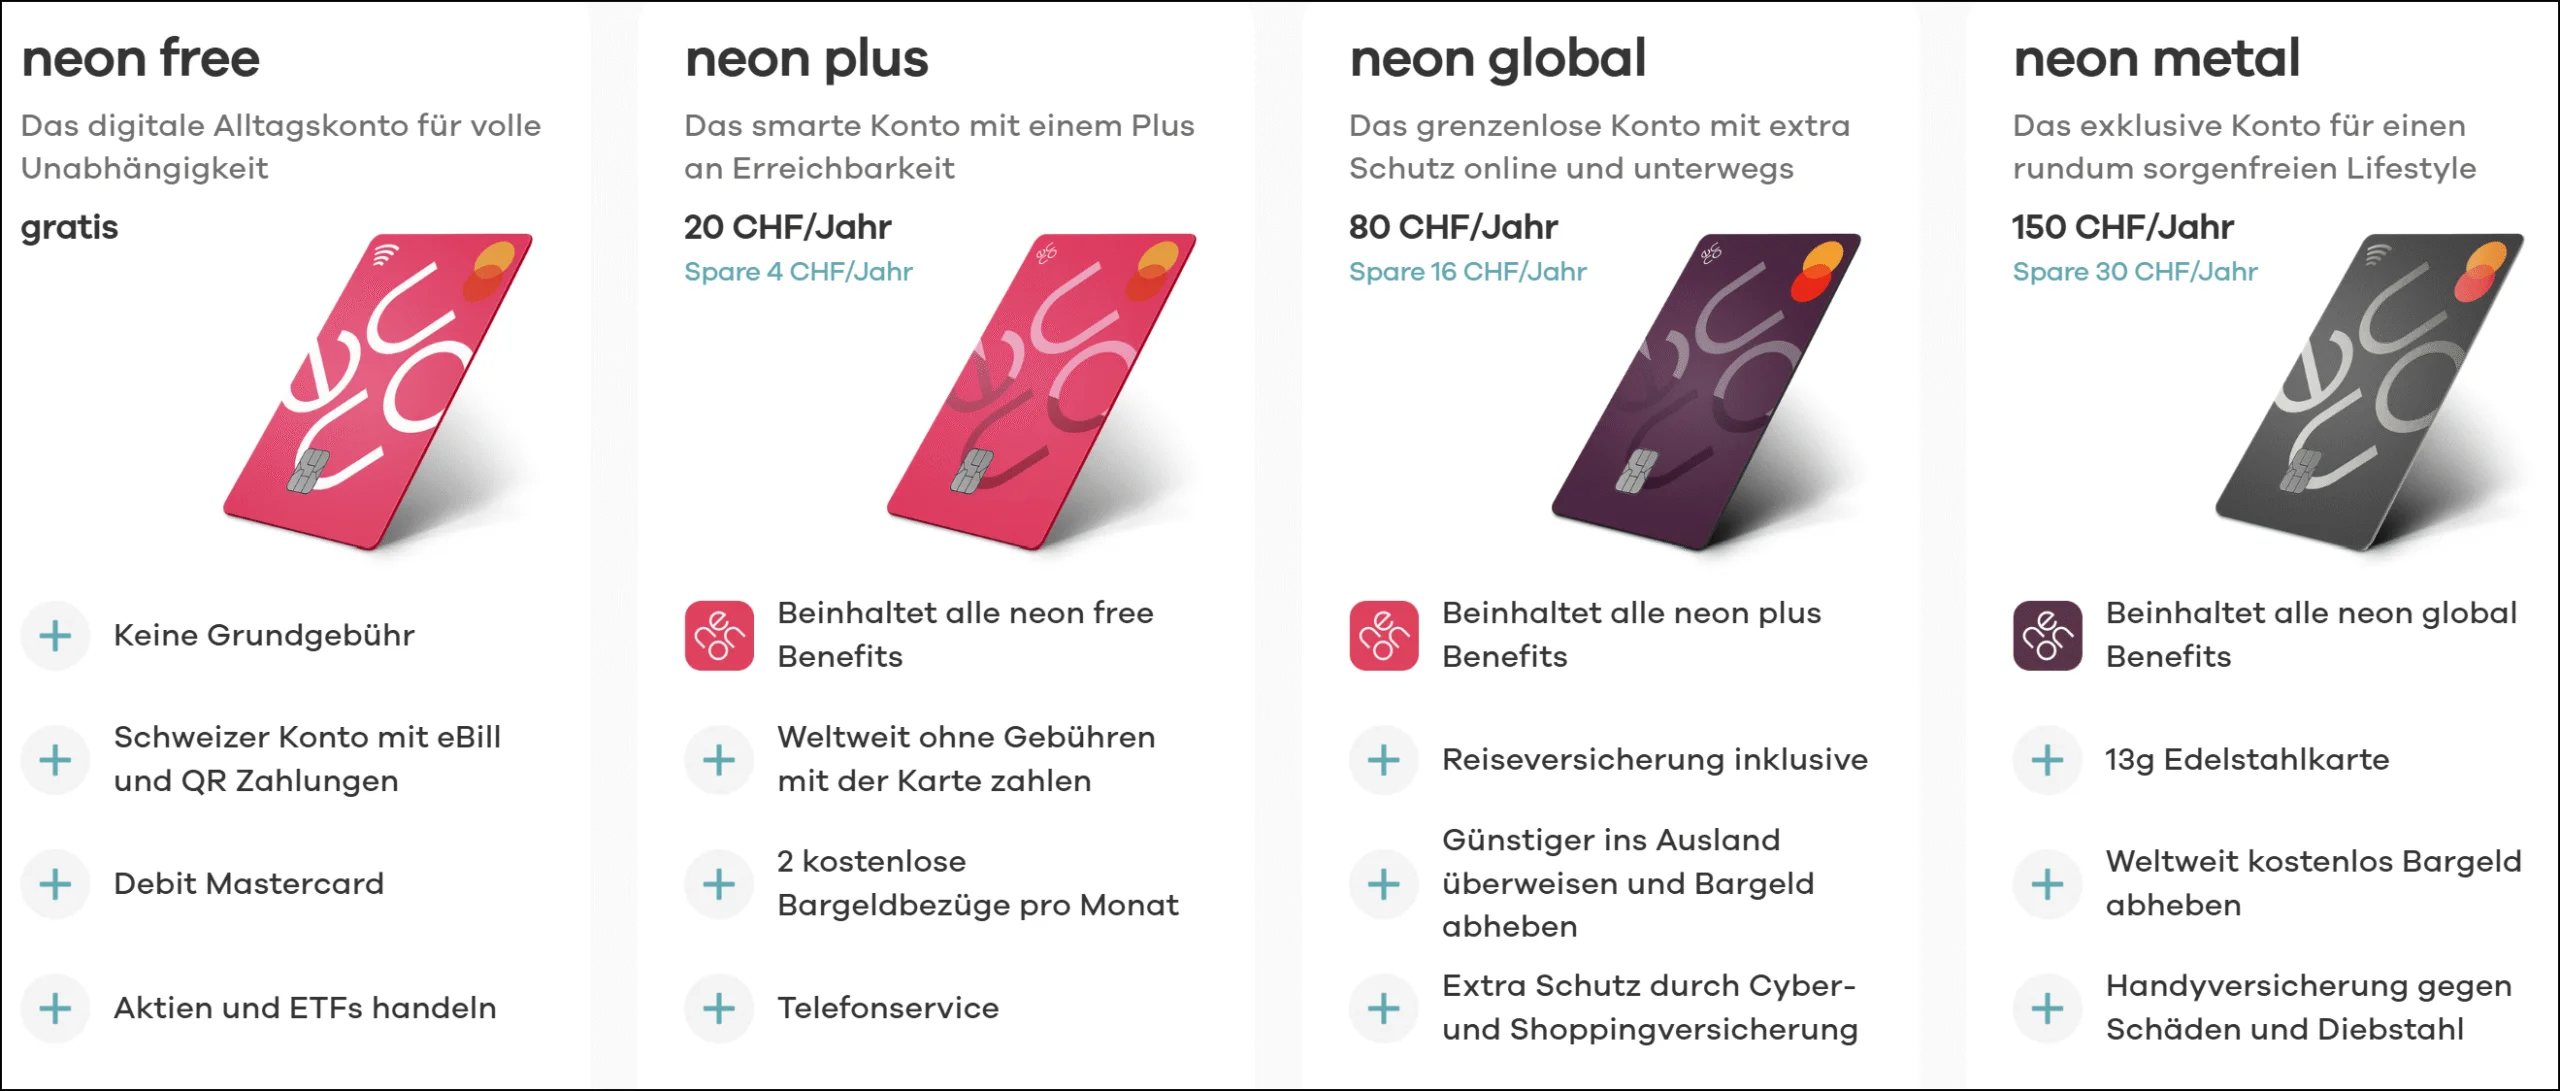
More information on the current account models is available on the neon website.
…which can be combined with two add-ons
Each of the four plans presented above can optionally be combined with the following two add-ons:
- neon green: “For a climate-friendly everyday life.”
- neon duo: “The joint account for duos.”
“neon green” option
For everyone who wants to do something good for the environment when paying by card, there is a card made of unvarnished cherry wood (!) or recycled plastic. For every CHF 500 spent with the neon green card, neon plants a tree. neon green can be combined with all the plans presented above and costs an extra CHF 3 per month.
More information on the green offering is available on the neon website.
“neon duo” option
neon also offers the optional neon duo joint account. It can likewise be combined with all neon plans. neon describes it as follows:
- For 2: the account for everyone who shares a home. In love, engaged, married, living together – or simply friends
- One login, one app: switch between your personal and joint account with a swipe
- 2 cards, 1 IBAN
- Keep track of your joint payments and transactions at all times
- CHF 3 per person per month
- Open the account directly in the app – no paperwork, no branch visits
What we find particularly innovative about neon duo is that you can manage both your personal and your joint account in the same app and keep an eye on both worlds with a single swipe at any time. There is one drawback, though: neon doesn’t offer this cool feature for free but charges an additional monthly fee of CHF 3 per person.
More information on the joint account is available on the neon website.
Our experience with payments at neon
For most people, payment features and conditions are likely to be the main factor when choosing a smartphone bank.
Below, we break the neon free offering down into its individual services and give each one a price tag (see also neon’s price list).
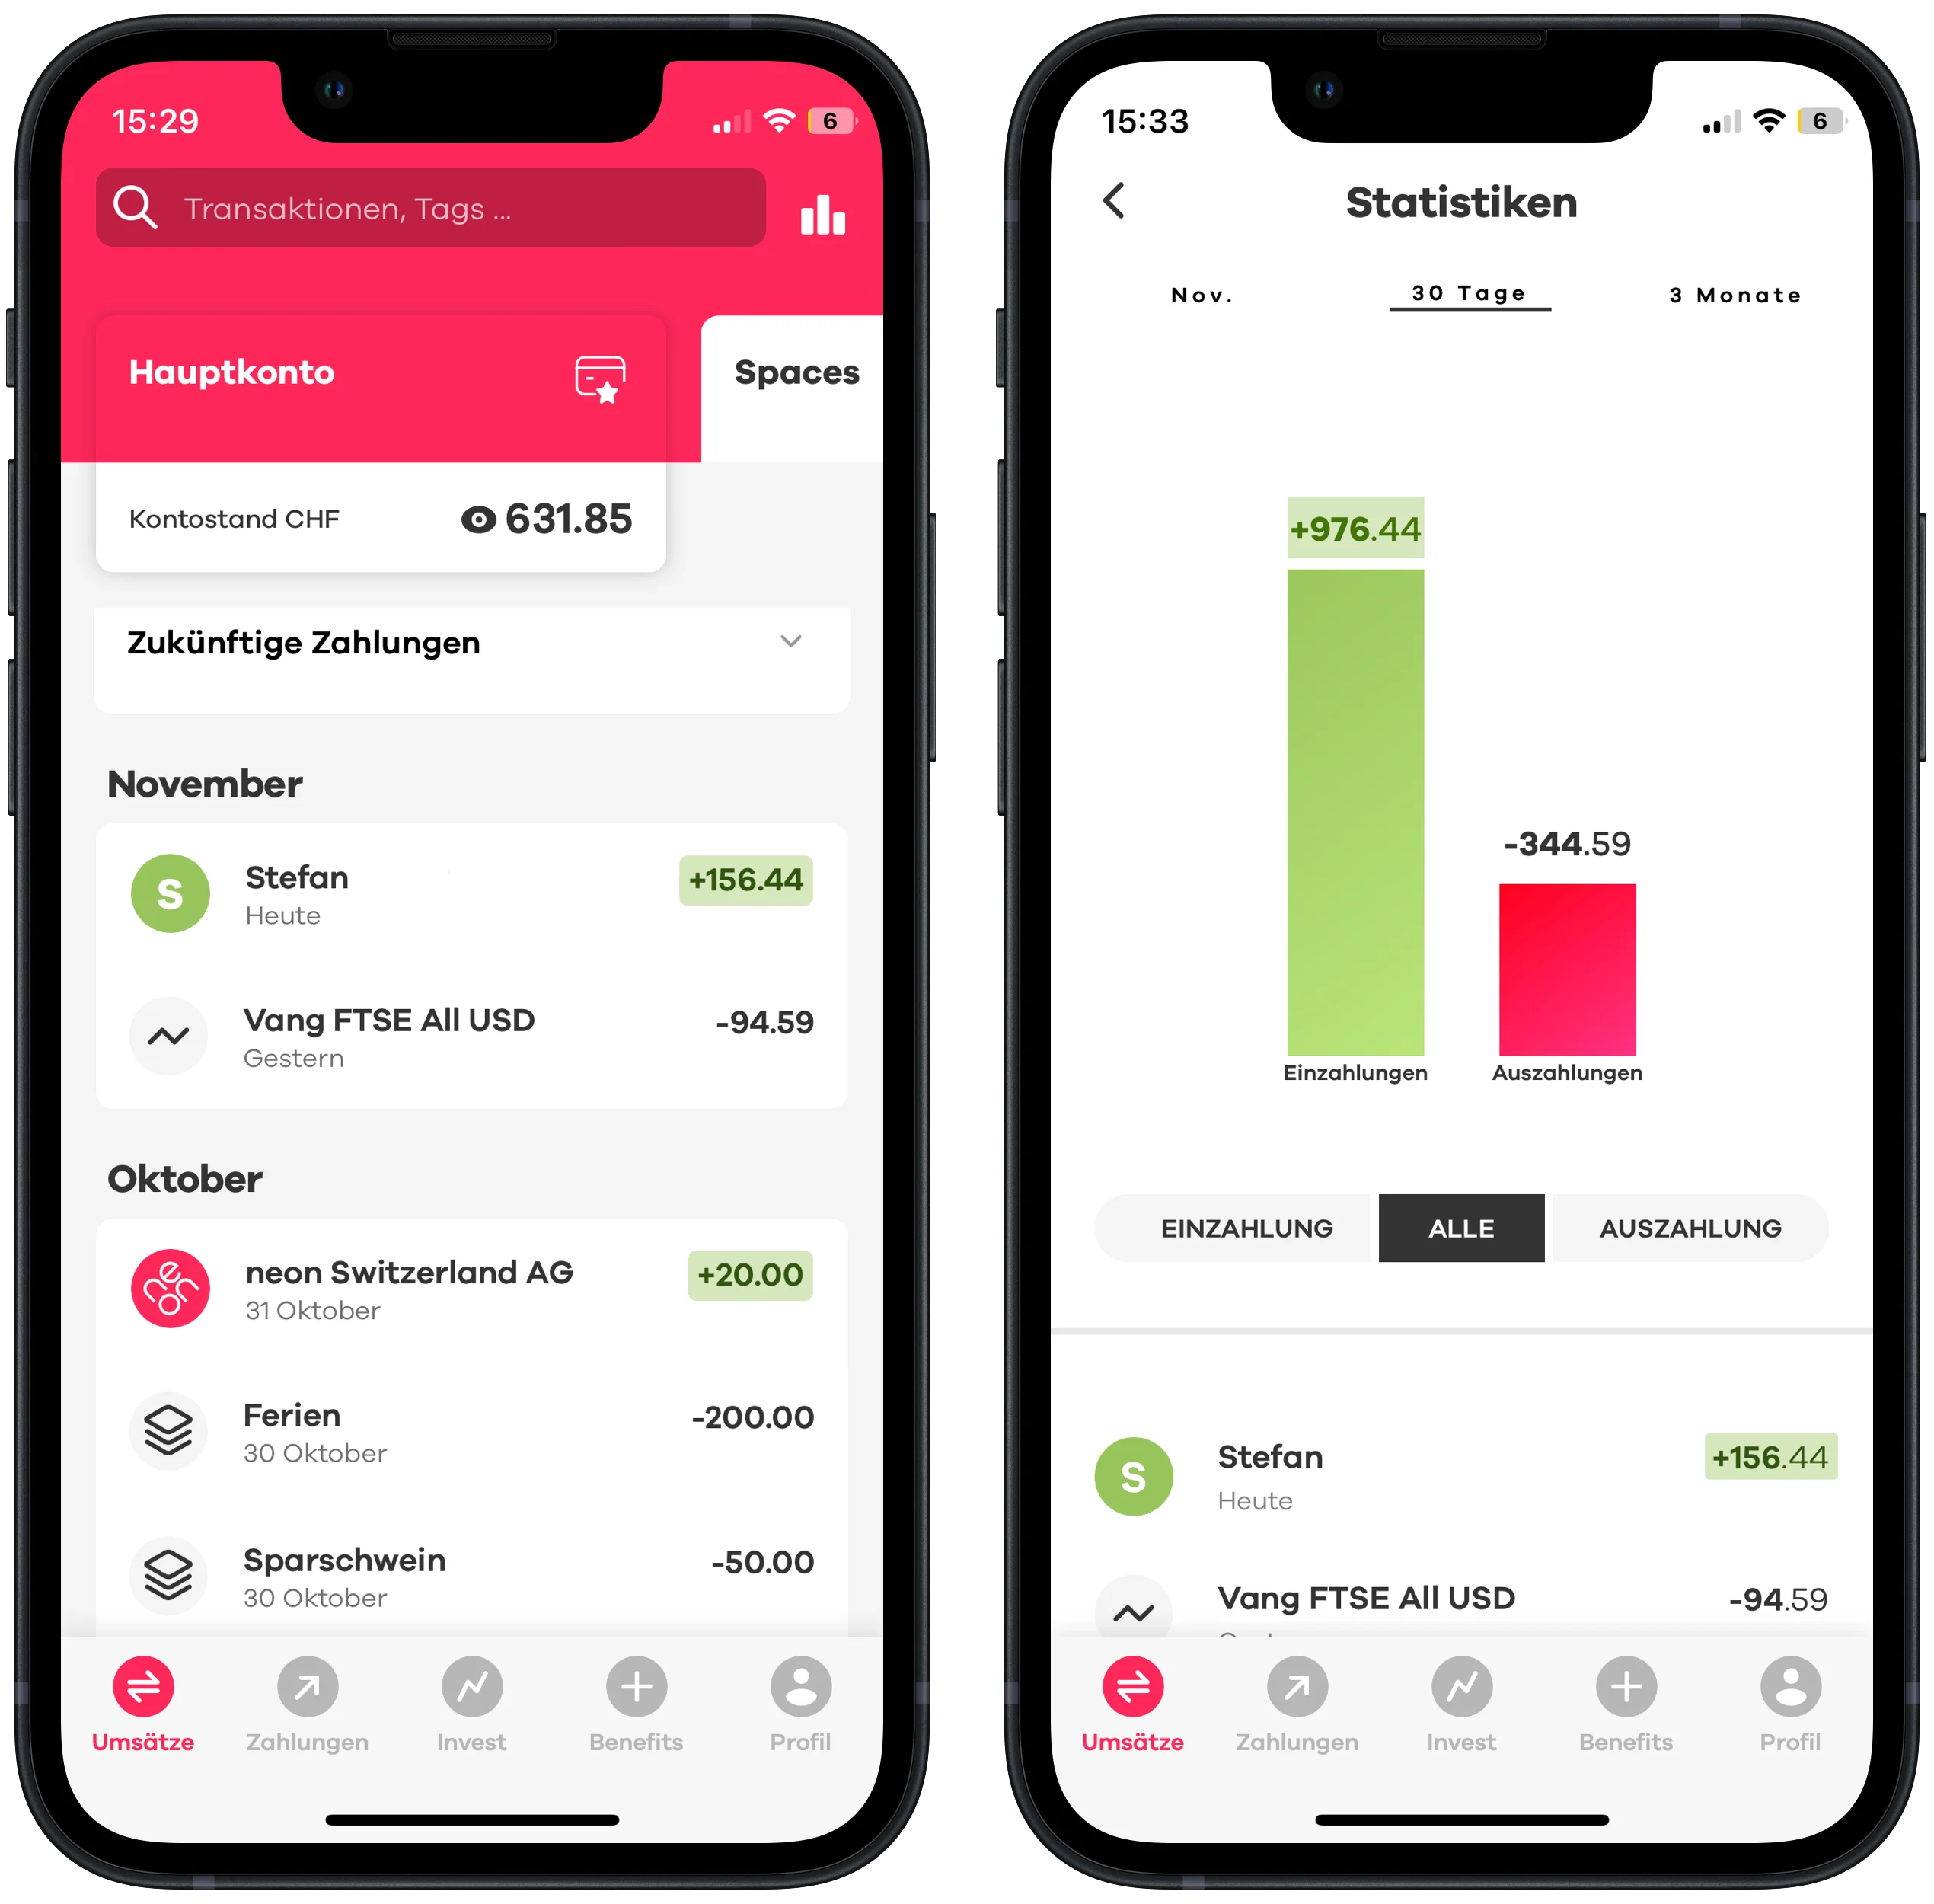
neon services and prices for payments WITHOUT a card
- Free account management (any interest, however, only on the savings account)
- Domestic IBAN transfers free of charge in CHF and with a 1.5% exchange rate mark-up in EUR
- International transfers possible in 20 currencies incl. EUR; fees usually between 0.8% and 1.7% depending on amount and currency, made up of the partner fee charged by Wise and neon’s so-called convenience fee, but without an exchange rate mark-up
- Transfer types: one-off (manual), recurring (standing order or LSV direct debit), eBill, TWINT
- Cash deposits and overdrafts not possible
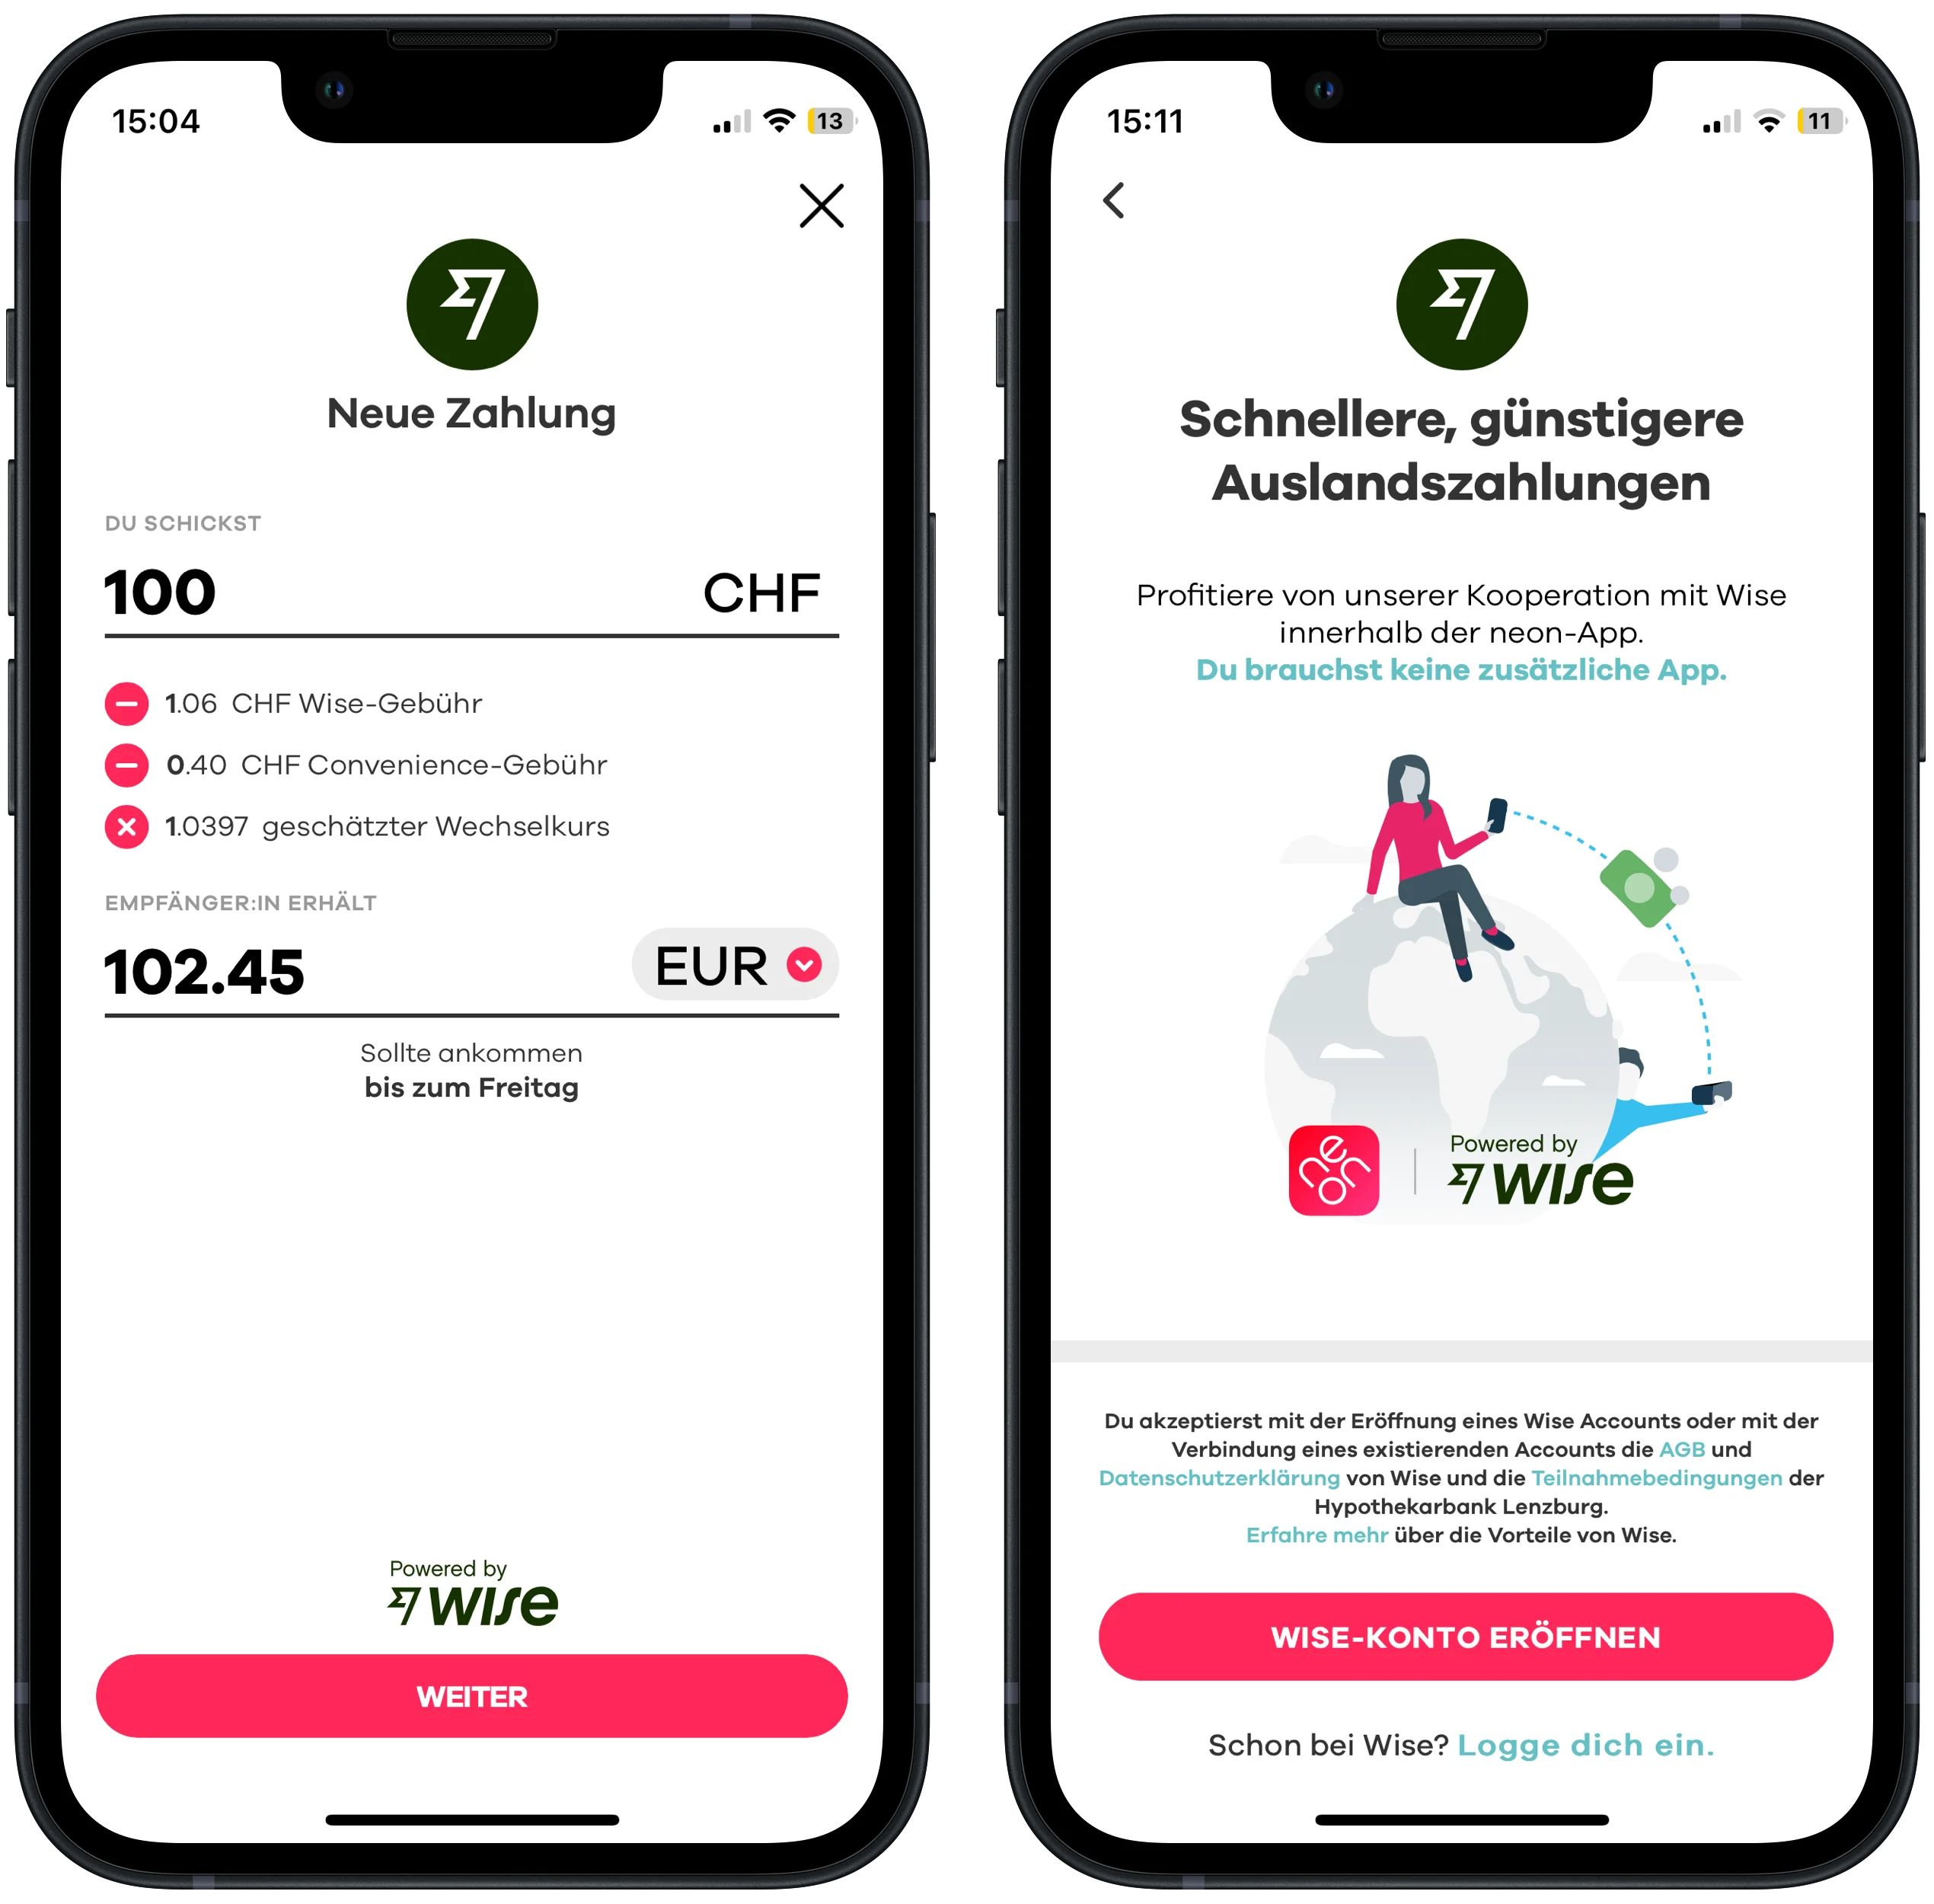
neon free services and prices for payments WITH a card
- No basic fee, but a one-off fee of CHF 20 for the debit card or neon Mastercard
- 0.35% exchange rate mark-up on card payments, based on the Mastercard rate
- Domestic ATM withdrawals: CHF 2.50 for withdrawals in CHF; CHF 5 for withdrawals in EUR
- Free cash withdrawals in Switzerland at Coop, Aldi and Lidl with a minimum purchase of CHF 10
- 1.5% per withdrawal abroad (regardless of currency; no exchange rate mark-up)
- Card can also be used via smartphone and smartwatch: “Apple Pay”, “Google Pay”, “Samsung Pay” as well as SwatchPAY! and Garmin Pay
- Monthly card limit of CHF 10,000, CHF 5,000 each online and in shops
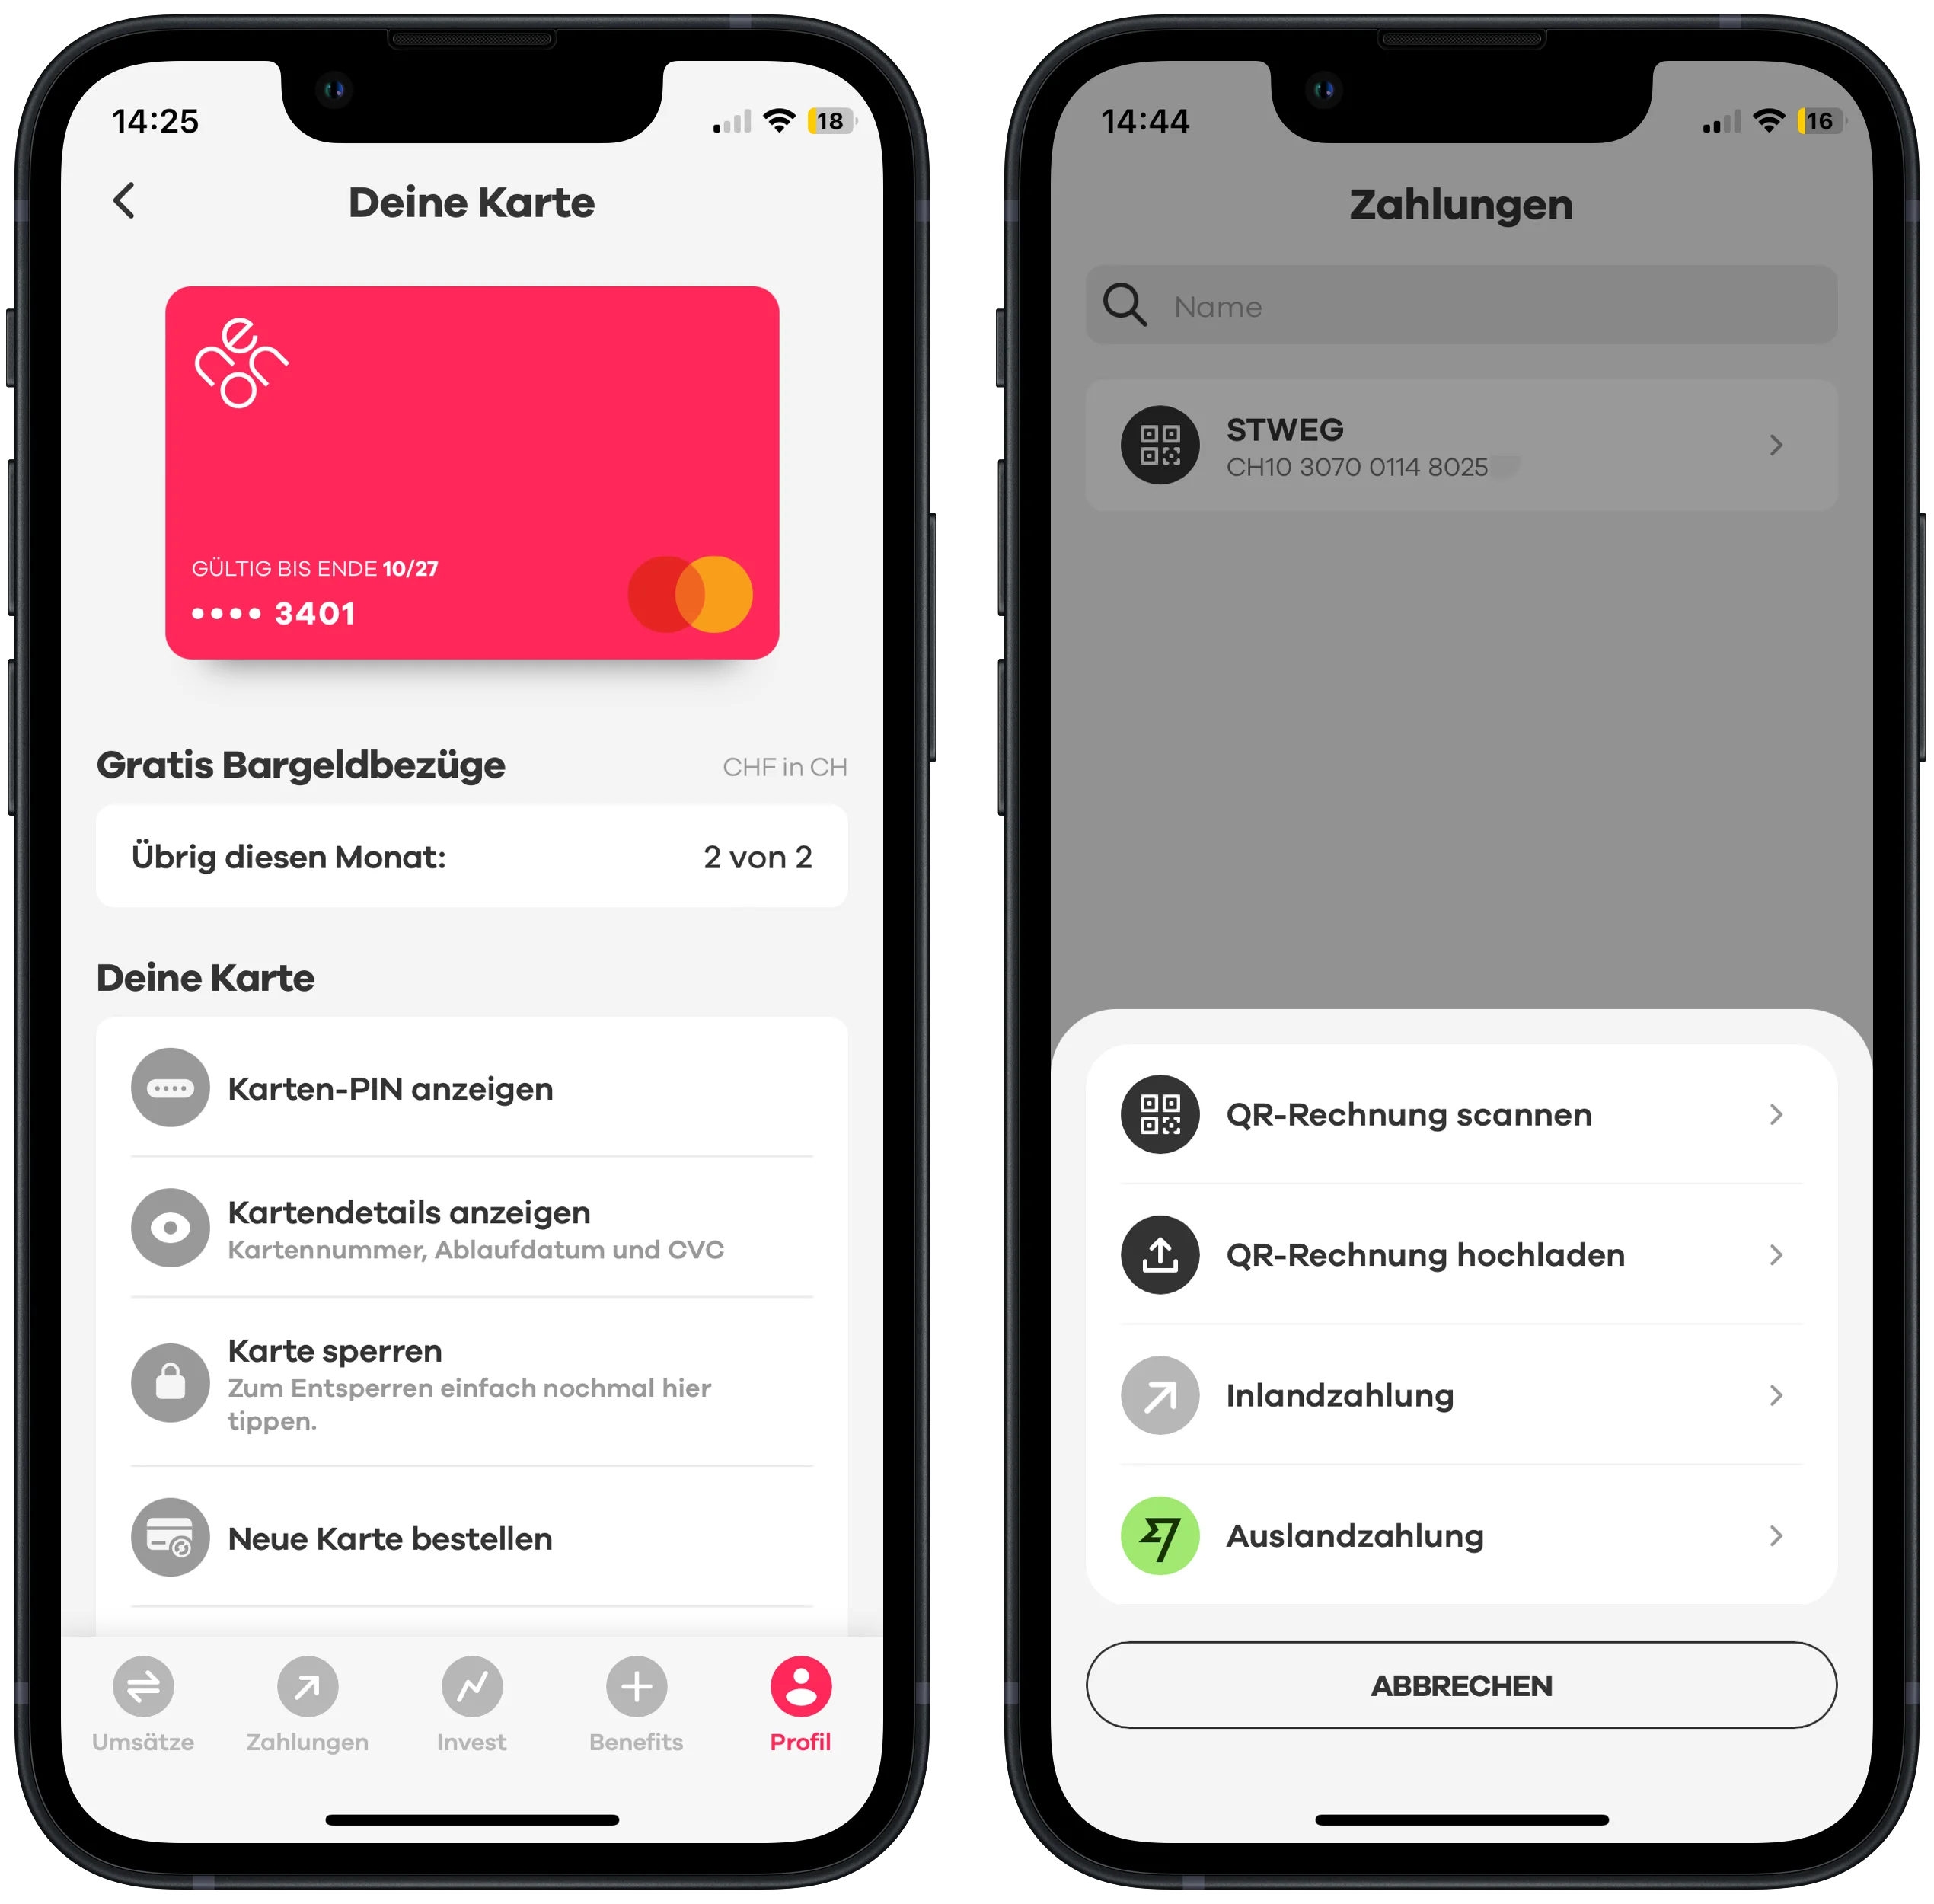
Note: In September 2024, neon replaced its previous Mastercard prepaid card with a new Mastercard debit card. The conditions are the same, but the new card is accepted even more widely. For example, it can also be used at the Swiss Post. All new customers receive the new card, as do existing customers whose prepaid card needs to be replaced.
Our verdict on paying with neon
For everyday payments, neon free is an attractive choice: no basic fee, a 0.35% currency exchange fee on card payments abroad and a user-friendly app for easy account management. Ideal for anyone who is cost-conscious and rarely needs cash.
If, on the other hand, you often pay by card abroad, occasionally withdraw cash from ATMs or value personal phone support, you are better off with neon plus (CHF 20/year): currency exchange fees on card payments are dropped entirely, and two cash withdrawals per month are included – a worthwhile upgrade for heavy users who love to travel.
The paid plans neon global (CHF 80/year) and neon metal (CHF 150/year) offer additional services such as insurance or exclusive cards. Whether this pays off for you depends on whether you really need these extras – best take a close look and weigh it up for yourself.
Our experience with saving at neon
To save with neon and benefit from interest, you first have to set up a separate account with its own IBAN. This takes just a few seconds using the app feature “Spaces”. You can then just as easily transfer money from your main account to your “Spaces” and back. Below, we summarise neon’s key savings services and conditions:
- No interest since December 2024
- Up to 10 individual savings goals (“Spaces”) can be set, with progress shown
- High liquidity thanks to a generous withdrawal limit of CHF 50,000 per month
- Regular, automatic saving possible
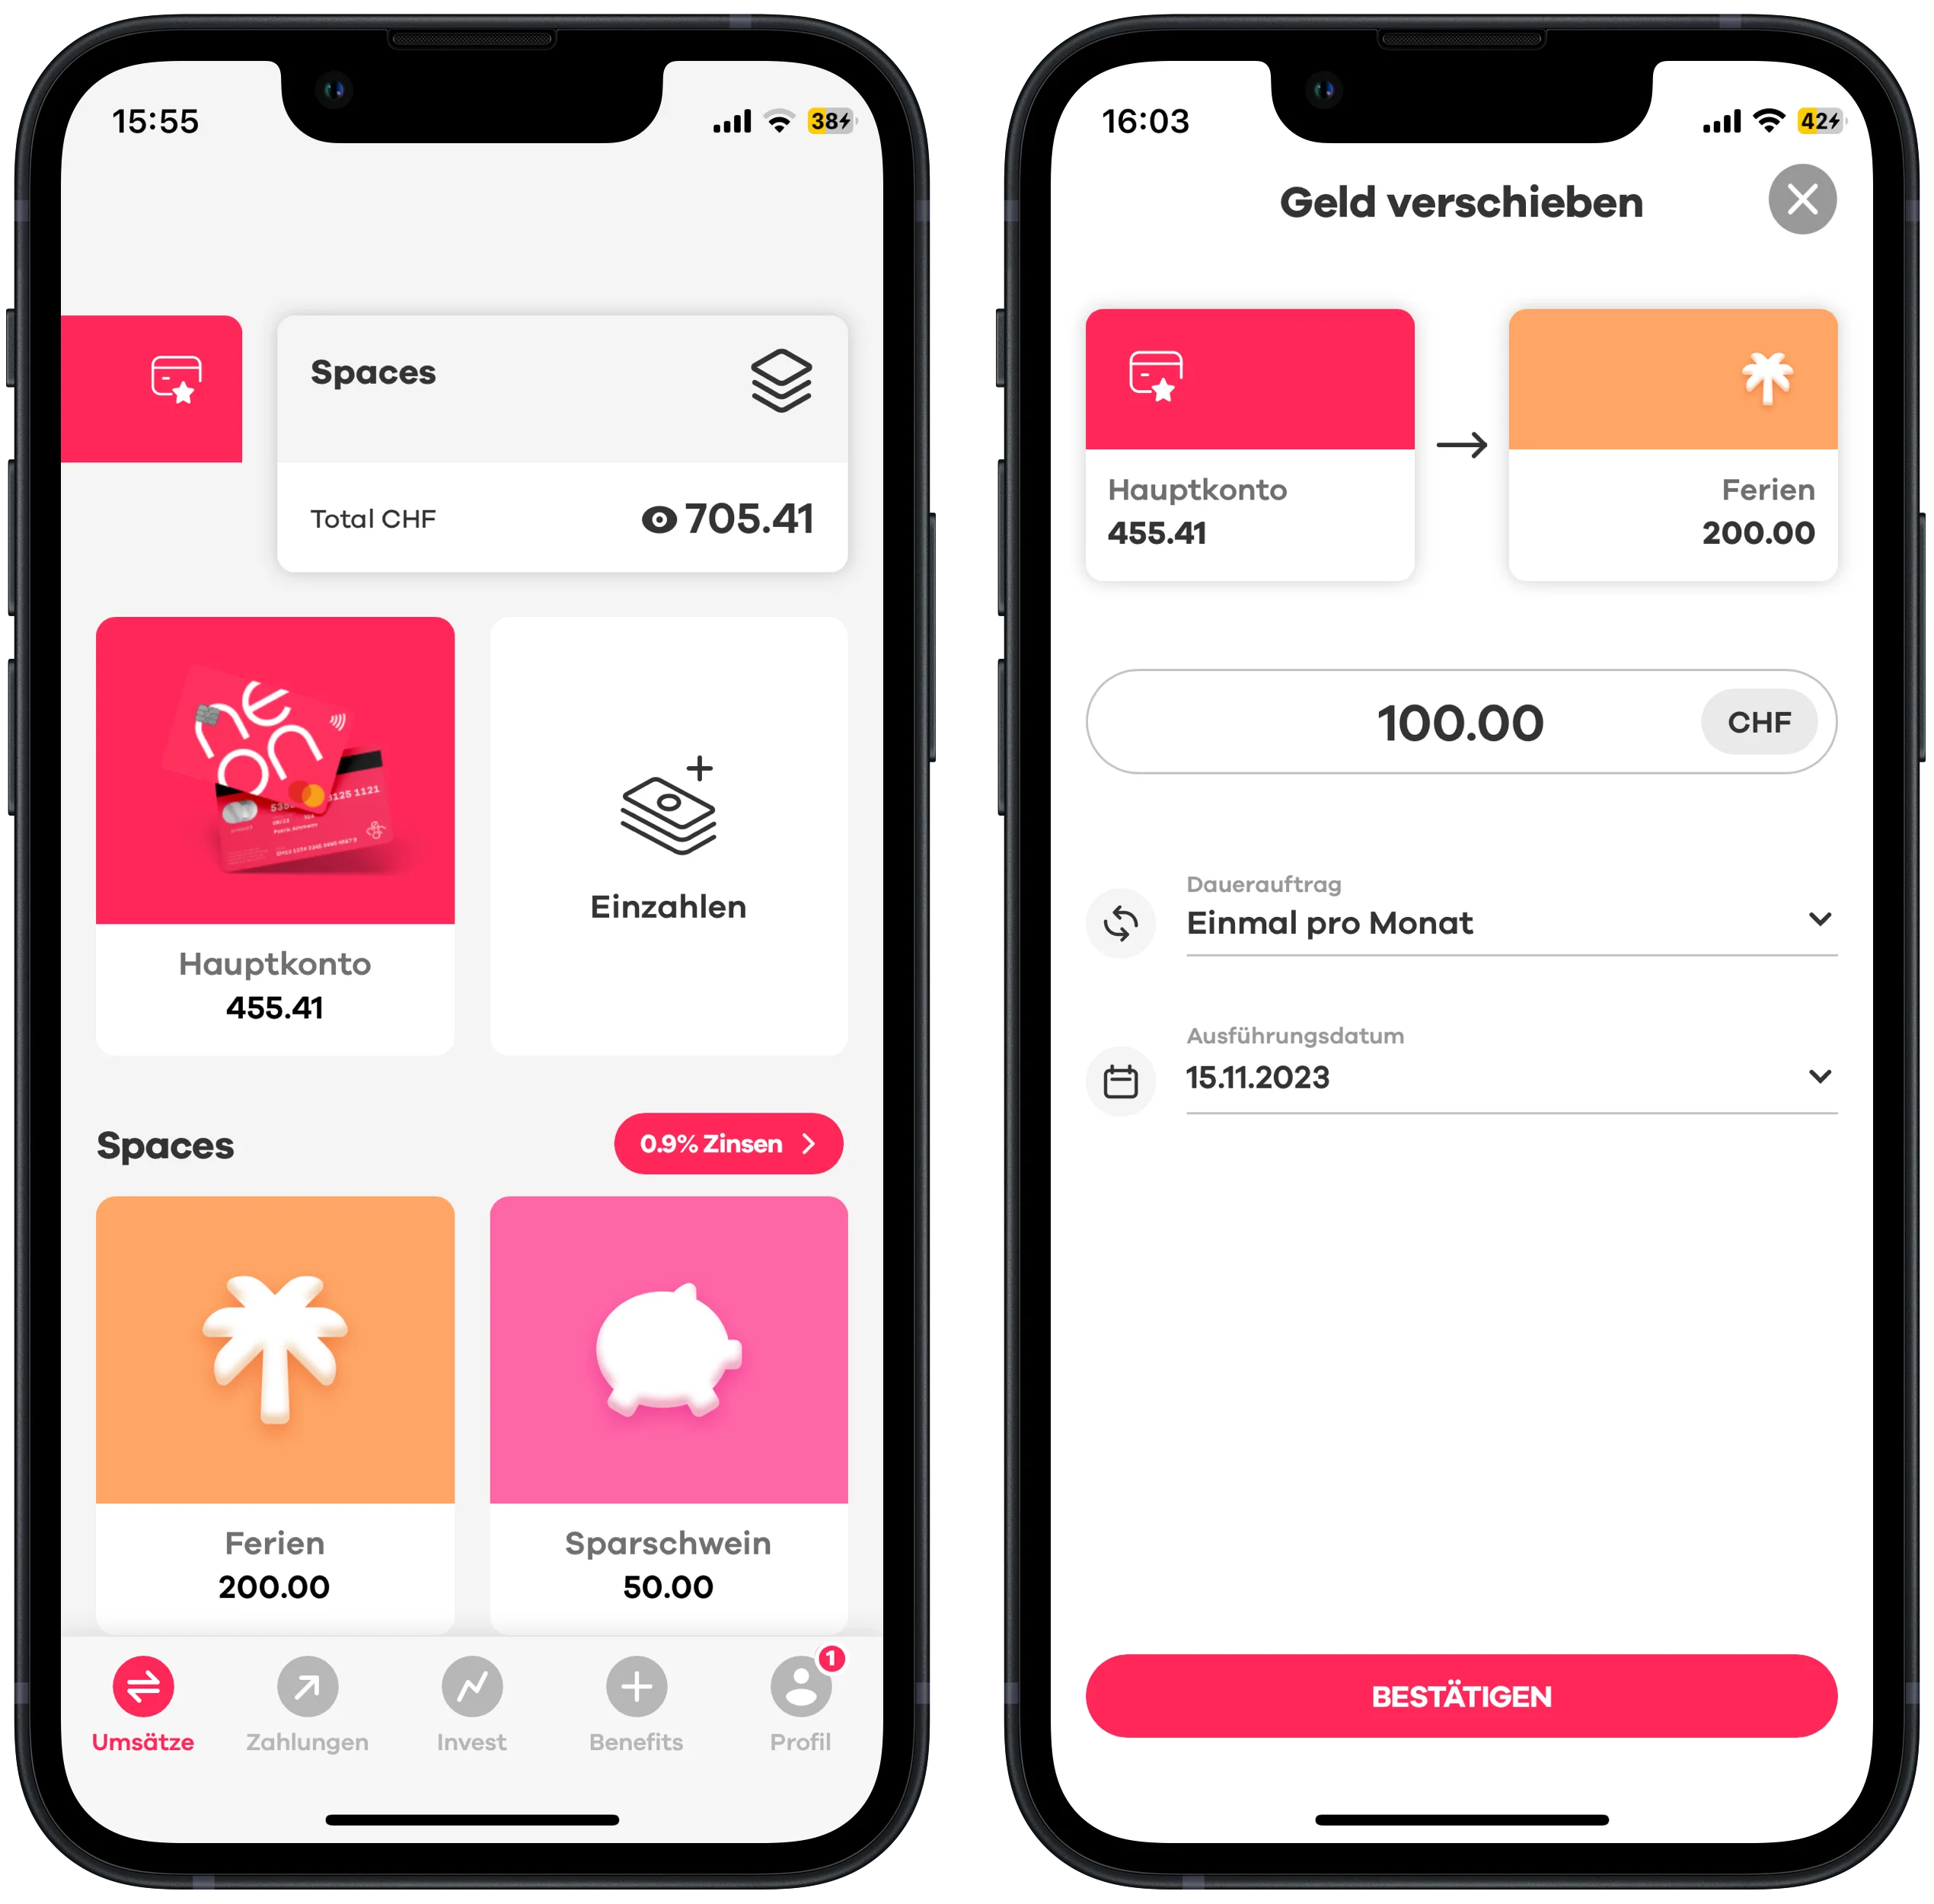
Our verdict on saving with neon
For us, the savings function plays a rather minor role, as we prefer to invest spare money. Die-hard savers are likely to find the savings feature particularly interesting, as it lets you save towards different projects not only manually but also automatically.
Unfortunately, neon has also steadily lowered its interest rates on savings, which currently stand at 0%.
Our experience with investing at neon
As passionate private investors, we are of course particularly interested in how neon performs as a securities broker. We have put together the key facts about neon Invest below:
- Investment universe limited to ETFs and individual shares
- No custody fees
- 0.5% commission per trade for ETFs and Swiss shares (no minimum fee)
- 0% commission on selected ETFs
- 1% per trade for foreign shares
- No currency exchange needed, as all products are traded in CHF
- Real-time prices: orders placed during trading hours are executed immediately at the current price
- Savings plans available, but no fractional trading
- BX Swiss (Bern stock exchange) as the only trading venue
Trading with neon only pays off for smaller amounts
The linear fee structure (i.e. always 0.5% of the transaction amount, with no cap) makes neon attractive above all for investors who want to invest smaller amounts on a regular basis.
An example: if you invest CHF 100, you pay a commission of just CHF 0.50, and for CHF 1,000 it is still an acceptable CHF 5. For trades of CHF 2,000 or more, however, you are definitely better off price-wise with a traditional online broker (see also our recommendations page).
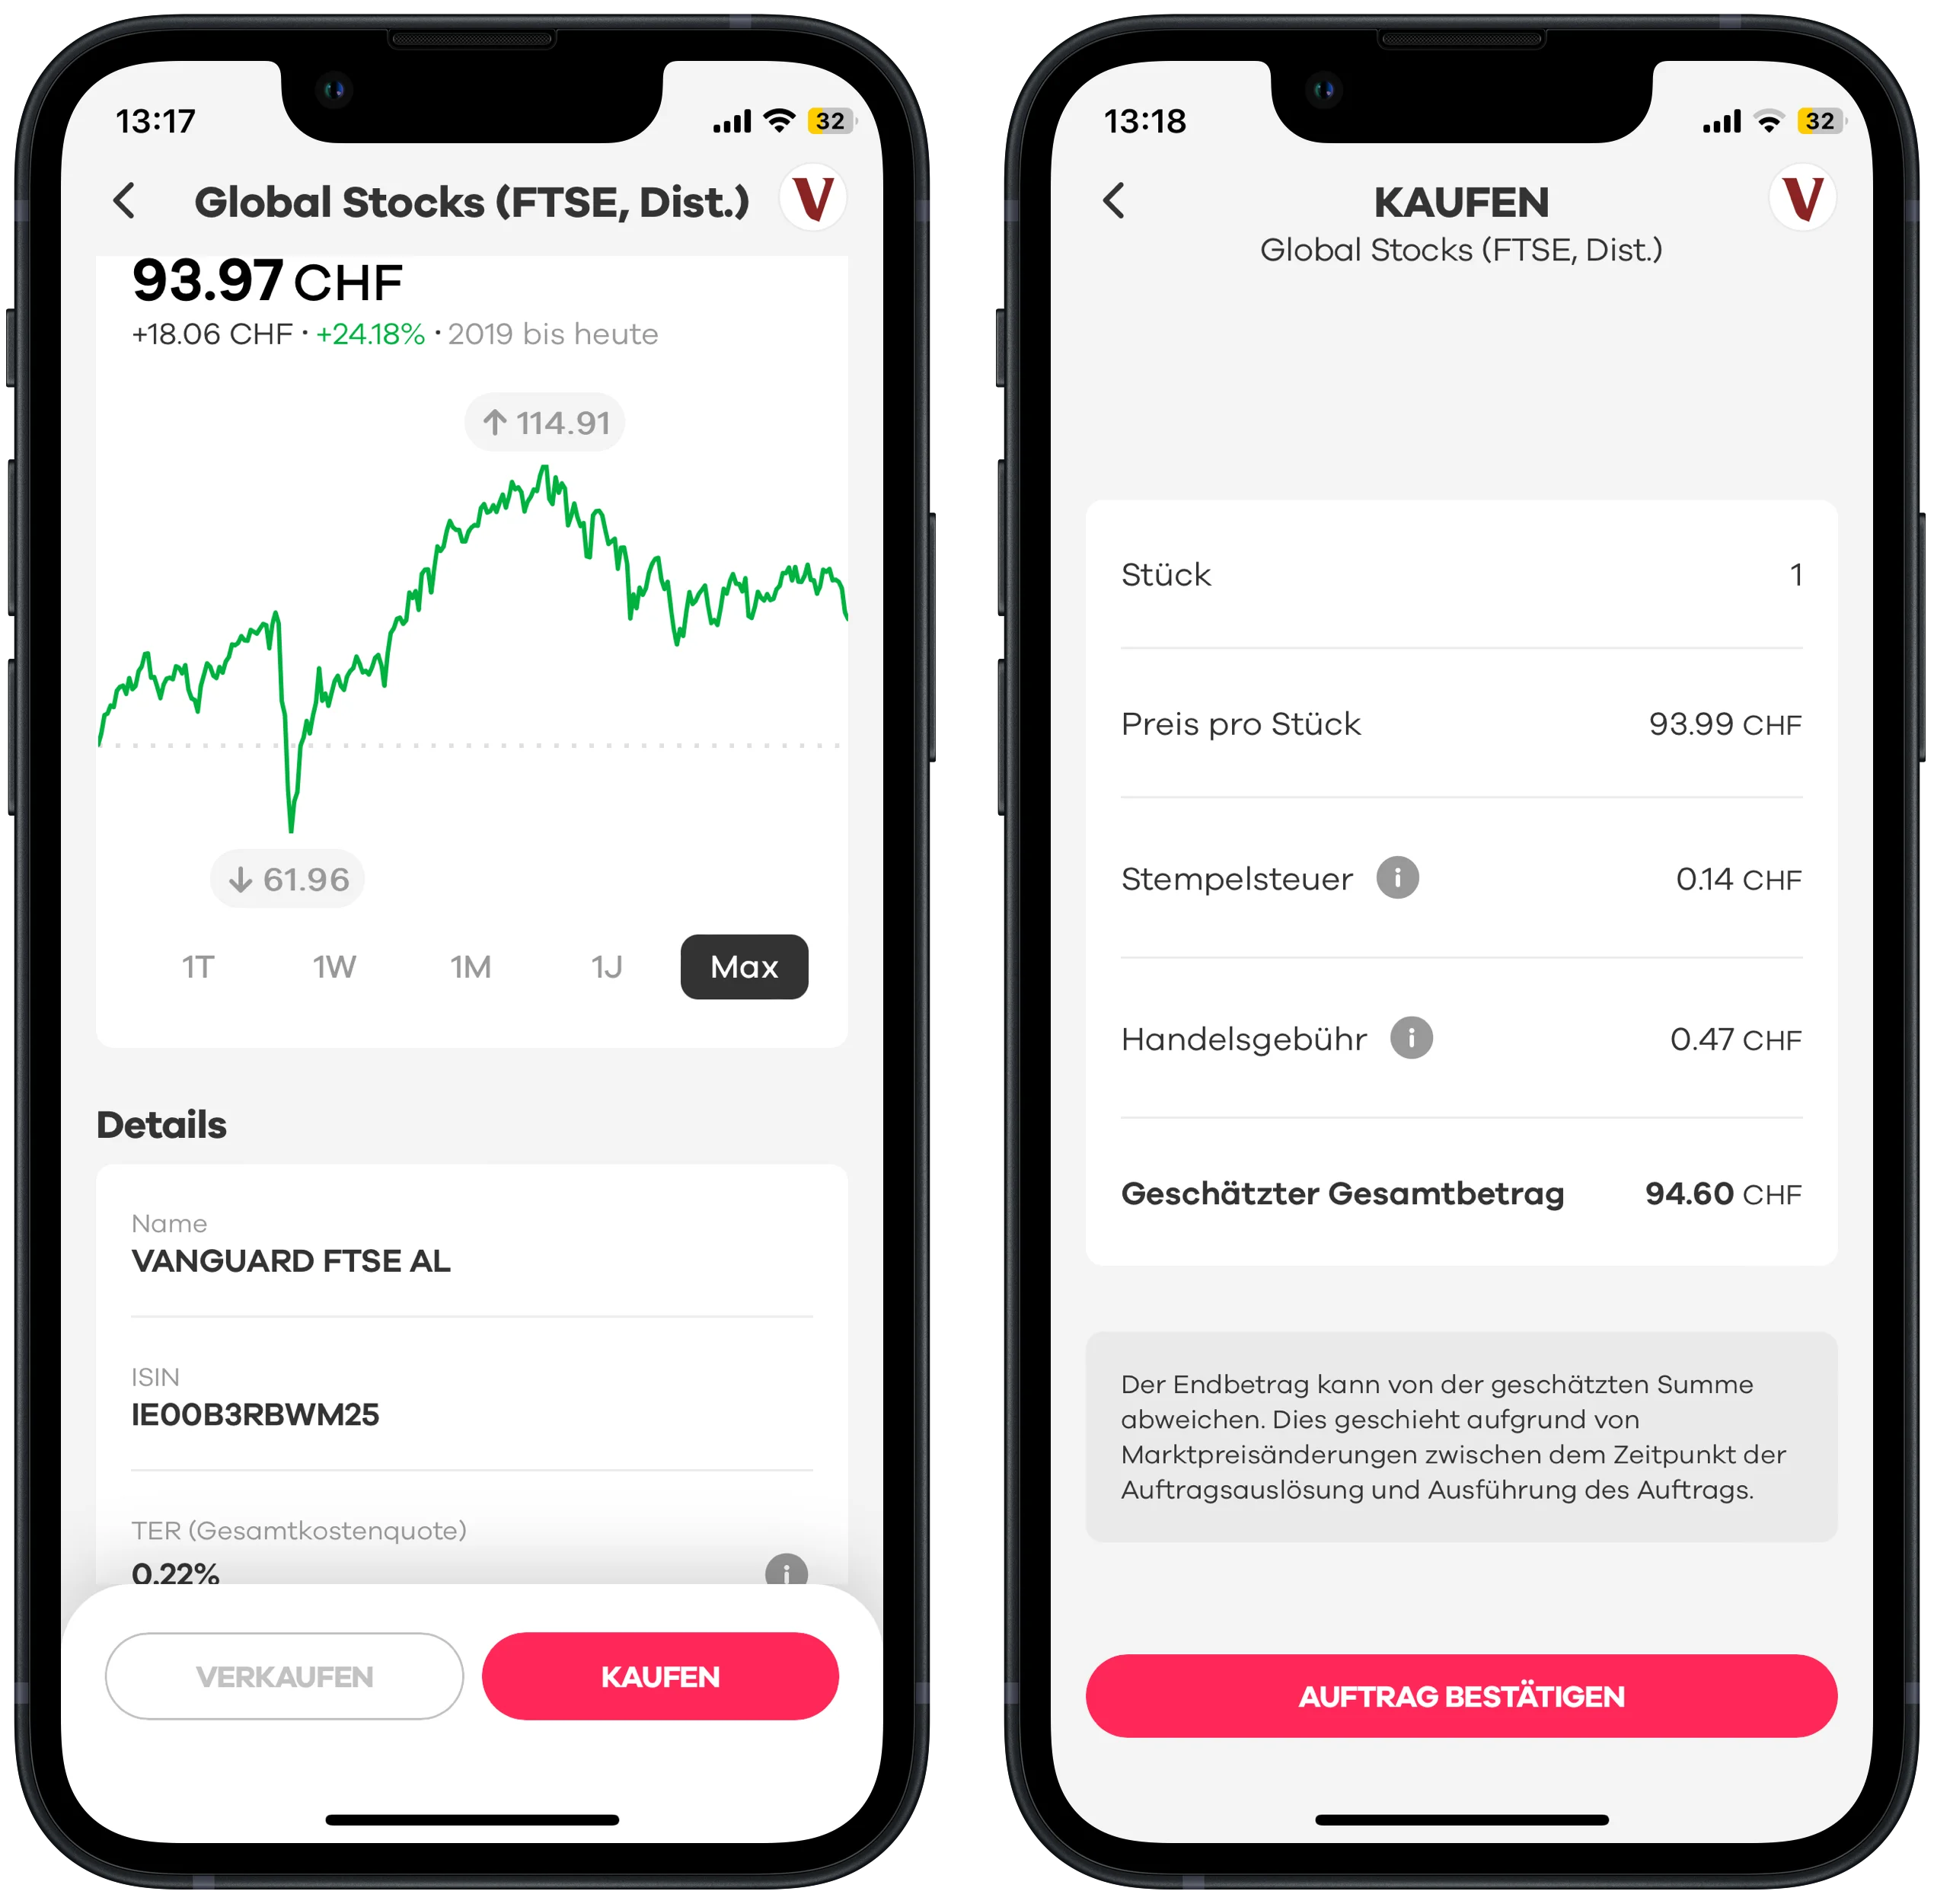
neon invest offers savings plans!
If you want to invest regularly and automatically in an ETF or a share, you can set up a savings plan with neon invest in just a few clicks, an option available since 2024. The key facts:
- Savings plan possible for up to three ETFs or shares from the entire neon investment universe (see next section)
- No additional fees
- Several commission-free ETFs (you only save the 0.5% commission within the savings plan)
- The minimum amount is determined by the price of a single unit
- No fractional trading, i.e. you cannot buy fractions of ETFs and shares
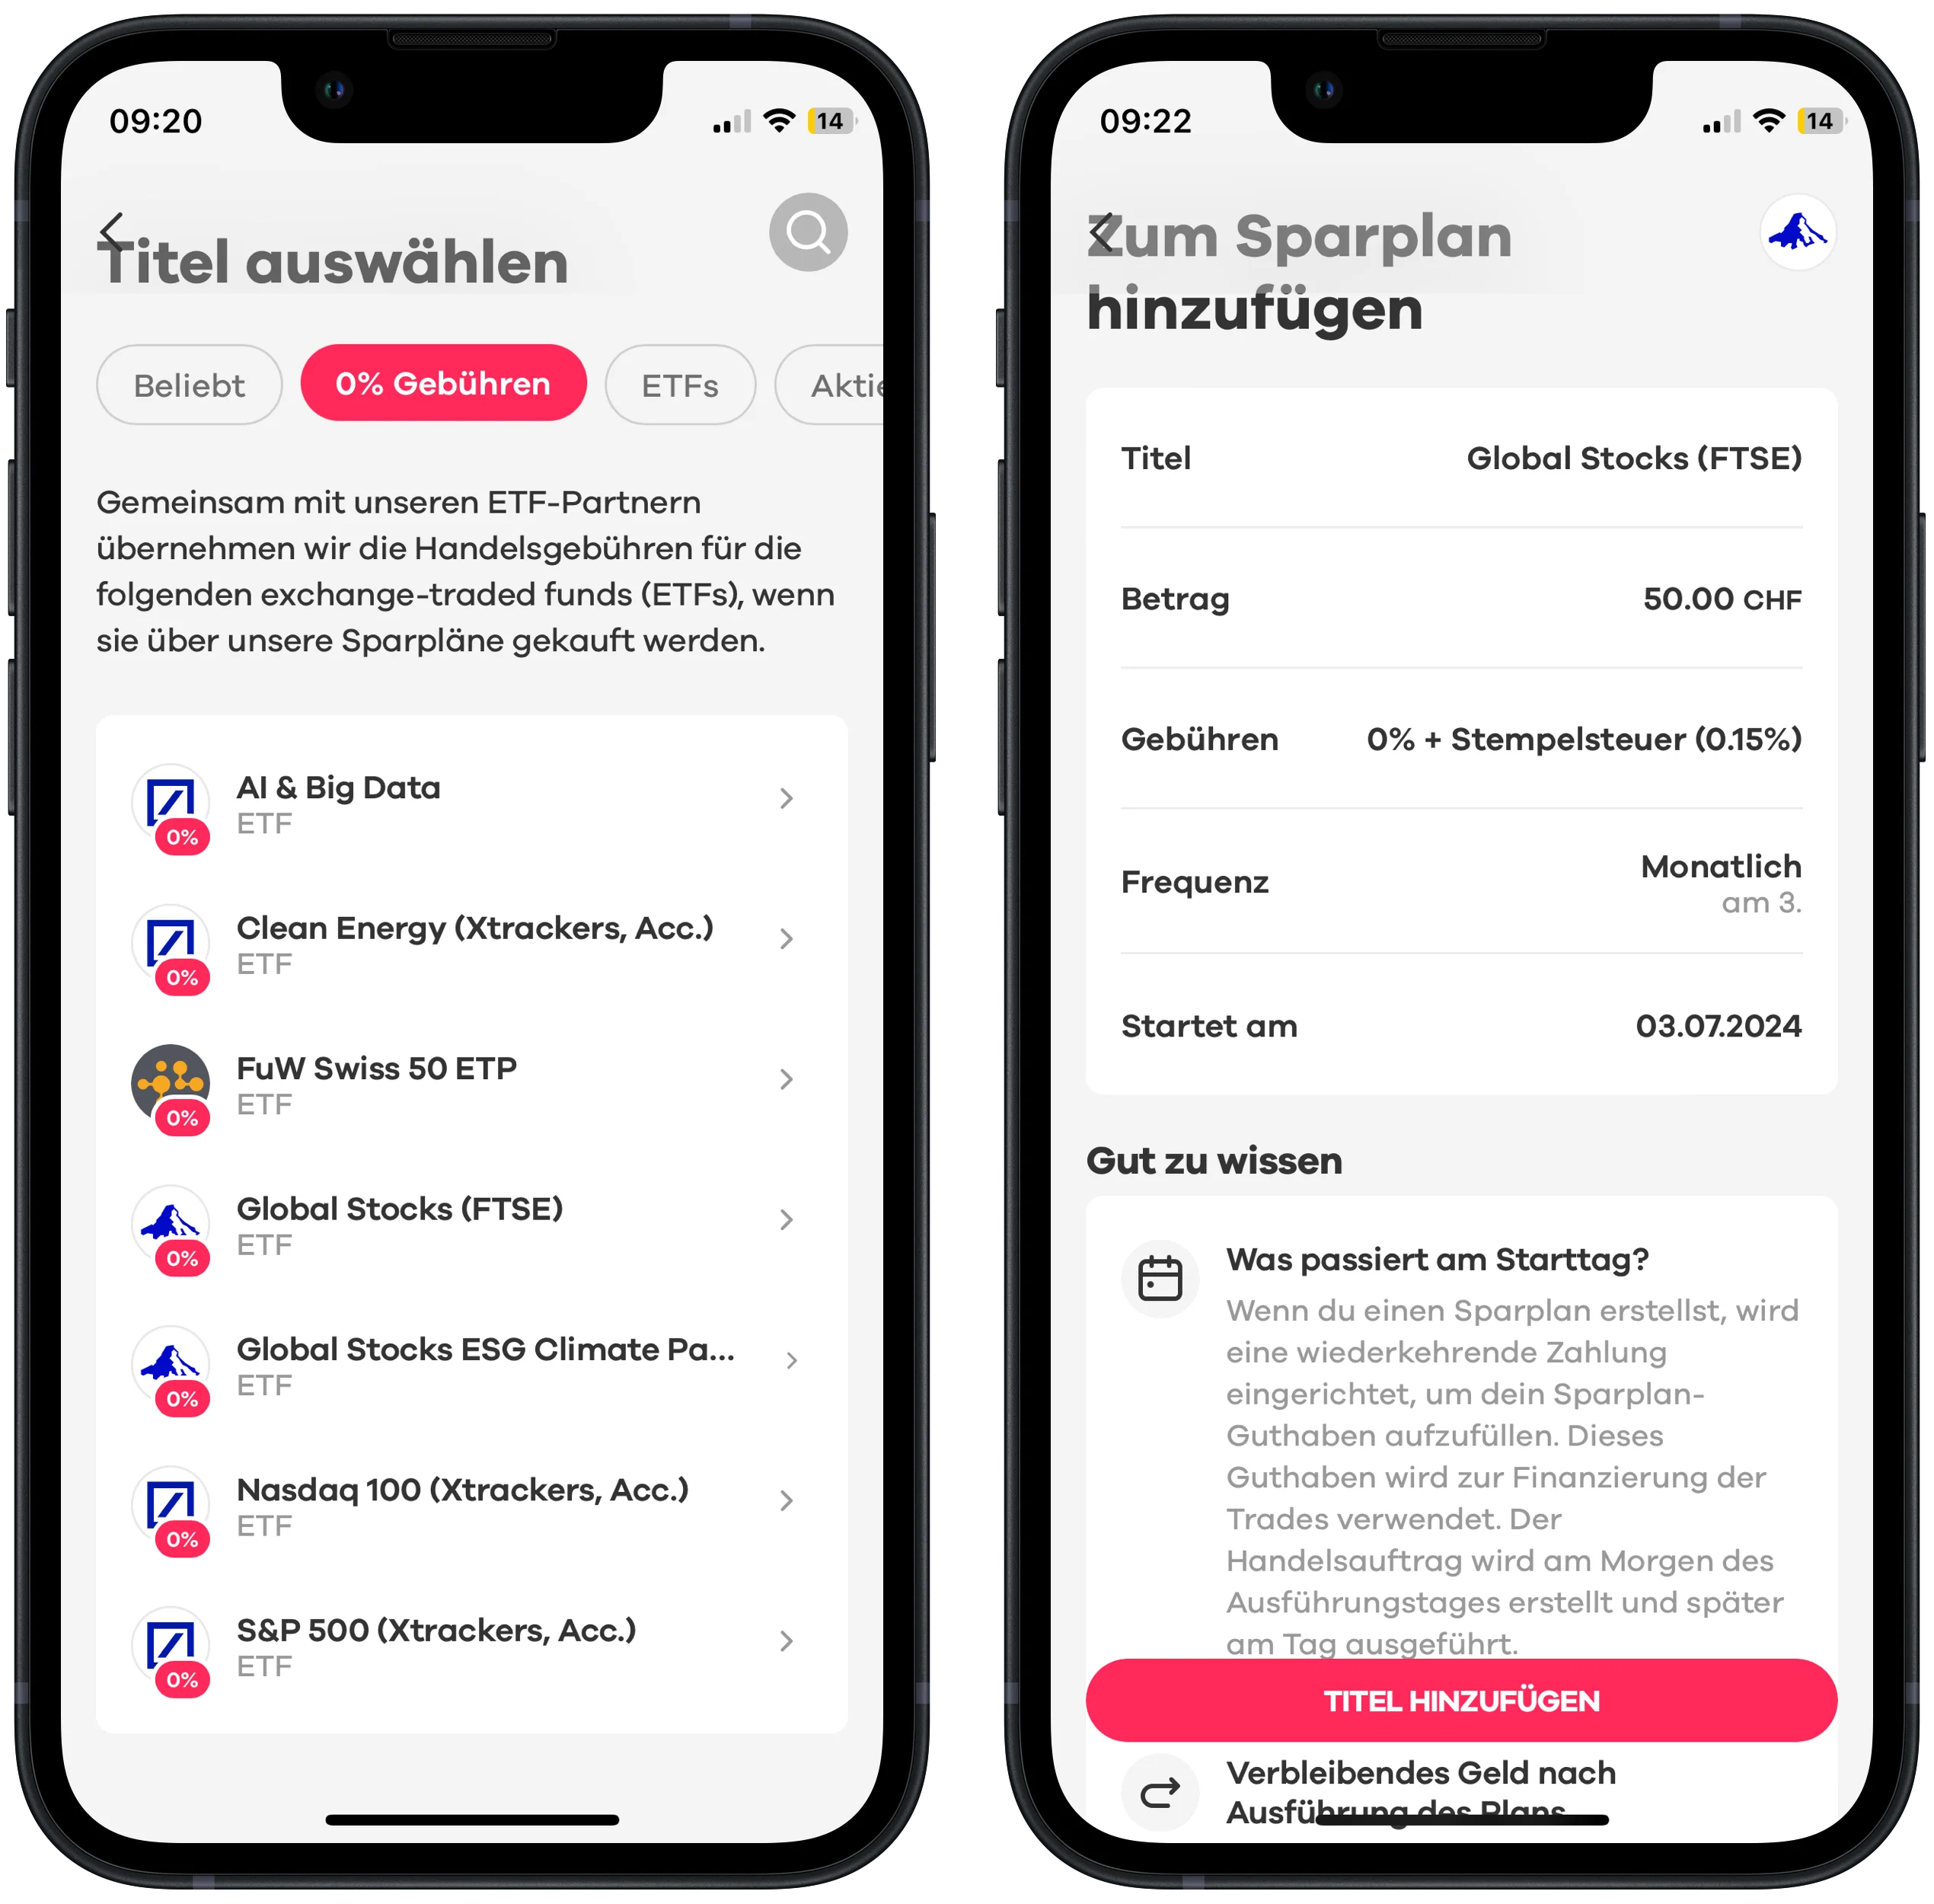
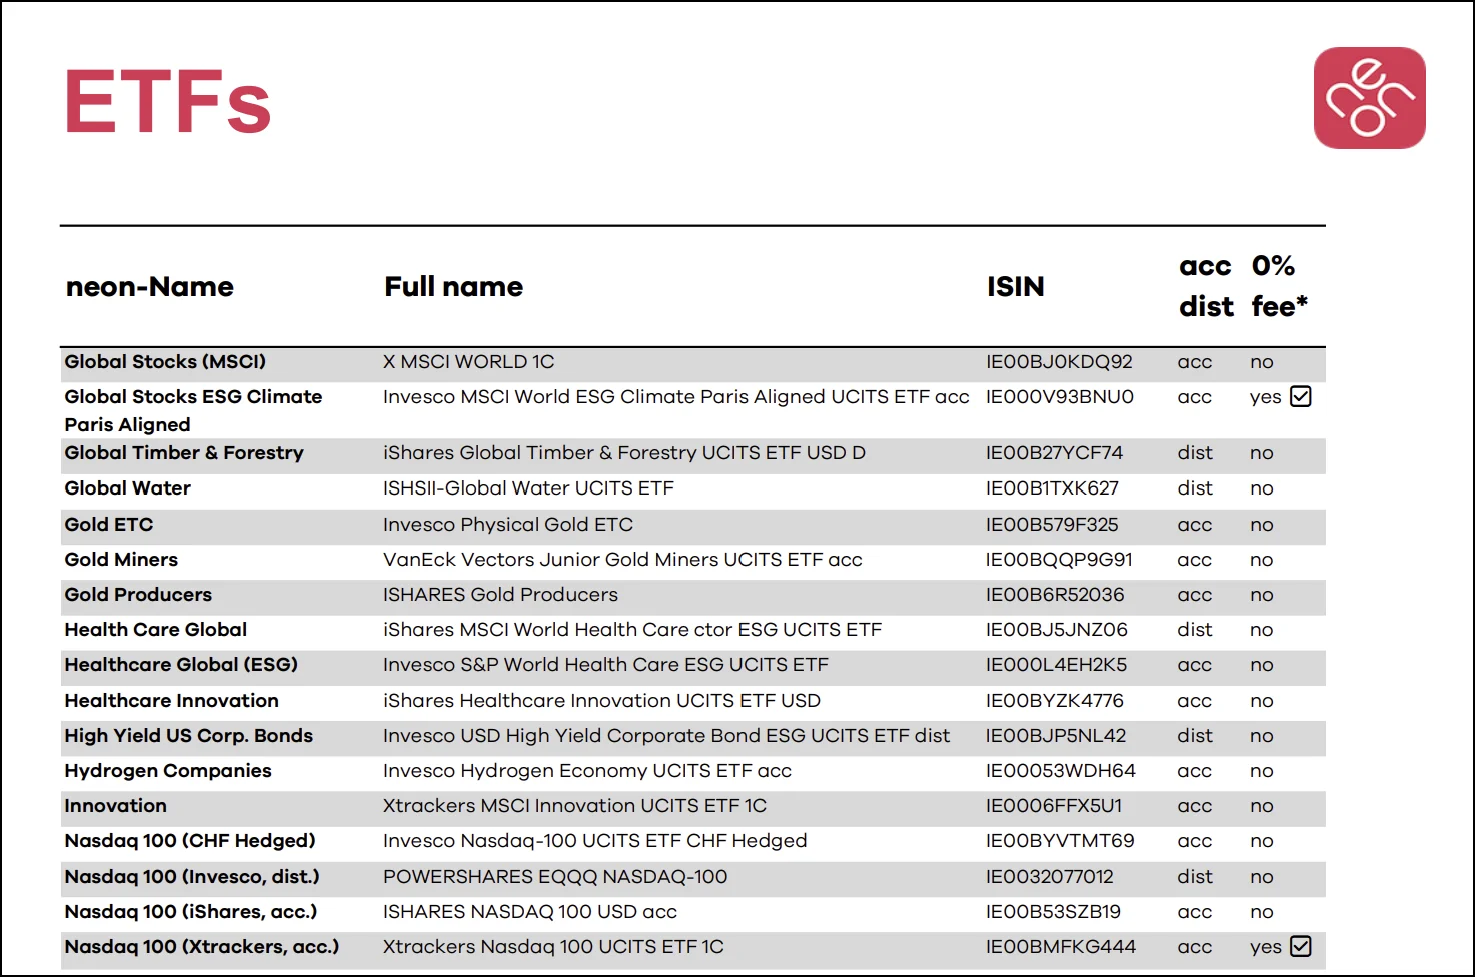
When investing regularly, purchase fees play a key role. That is why the ETFs without purchase commission in neon’s savings plan are particularly interesting. There are currently 22 free ETFs available from Vanguard (new), Invesco, Swisscanto, WisdomTree and Xtrackers (as of 19 May 2026).
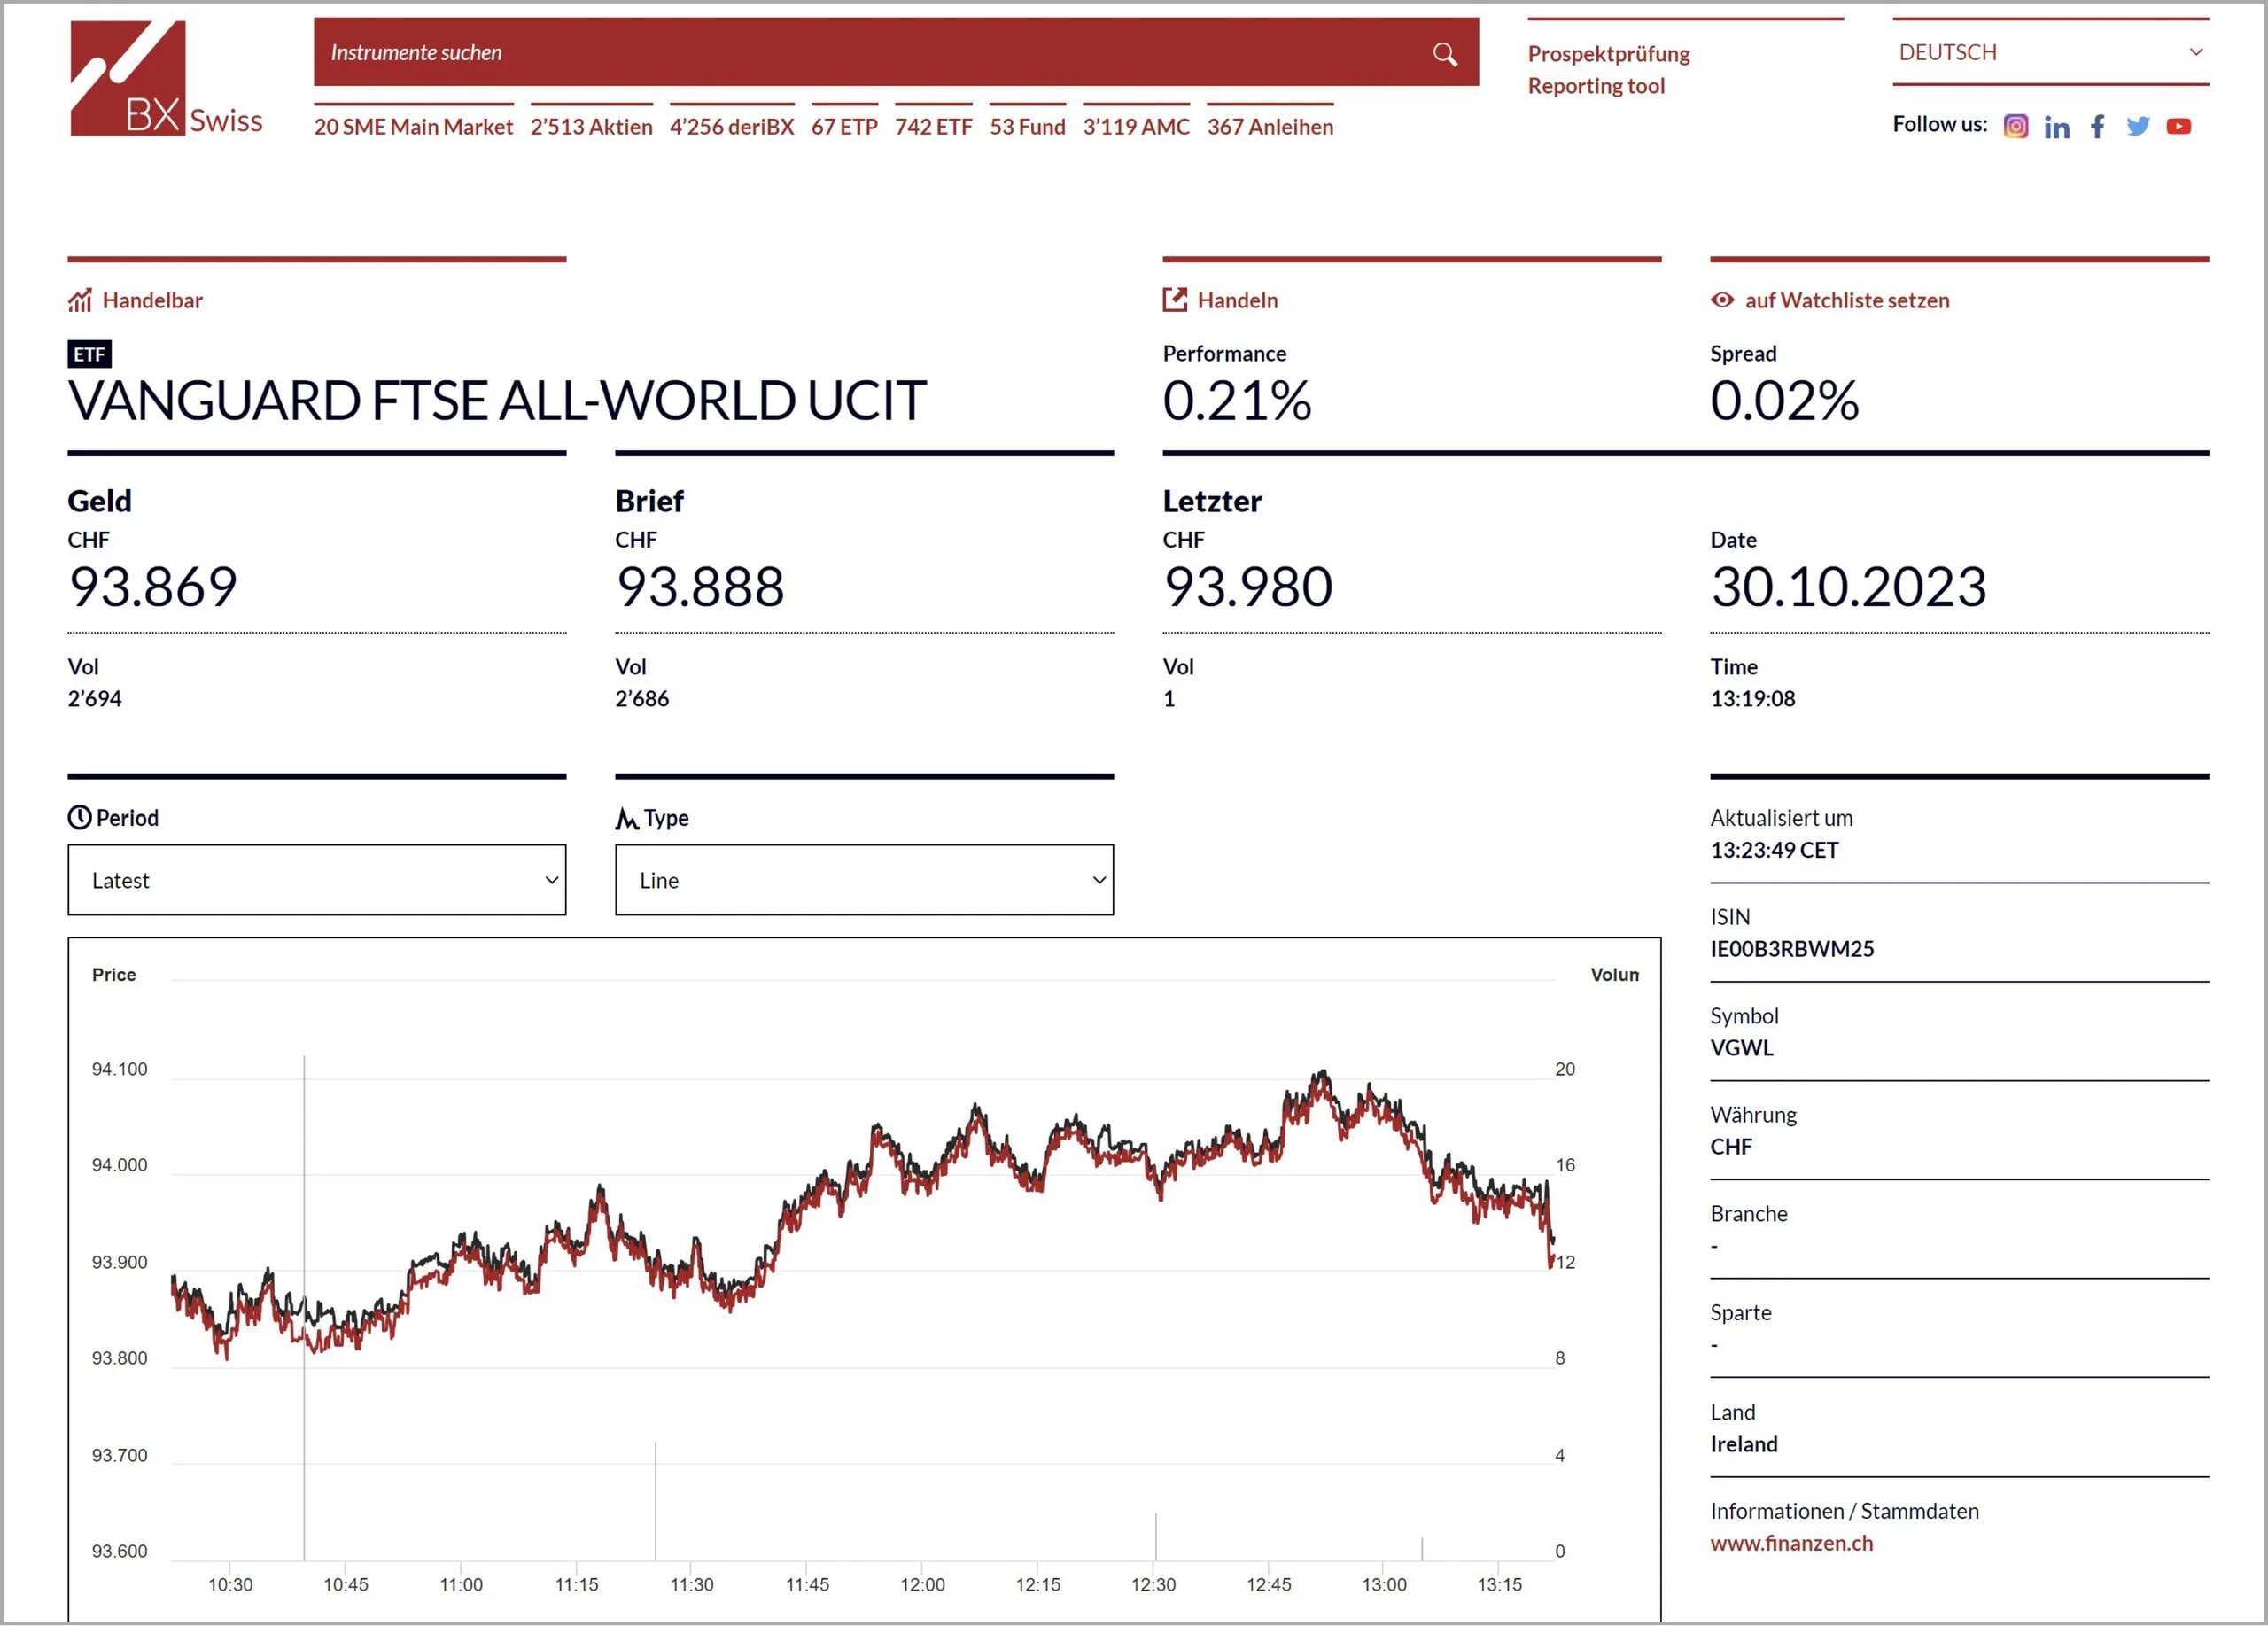
We find the Invesco FTSE All-World UCITS ETF Acc particularly attractive. The deciding factors are its low ongoing costs (0.15% TER), broad global diversification and fund size of over CHF 2 billion. This accumulating ETF should appeal to long-term investors – even though its track record is still relatively short, having been launched in June 2023. If you value a longer track record and a larger fund size and are willing to accept slightly higher costs, neon has offered an alternative tracking the same index since April 2026: the Vanguard FTSE All-World UCITS ETF Acc (IE00BK5BQT80, TER 0.19%, launched 2019).
neon’s investment universe
The investment universe consists of the following product categories and products (as of 19 May 2026, based on the filter function in neon invest):
- 313 shares: e.g. Apple, Nestlé, Netflix, Spotify, Starbucks, Tesla, UBS, Zurich
- 130 ETFs
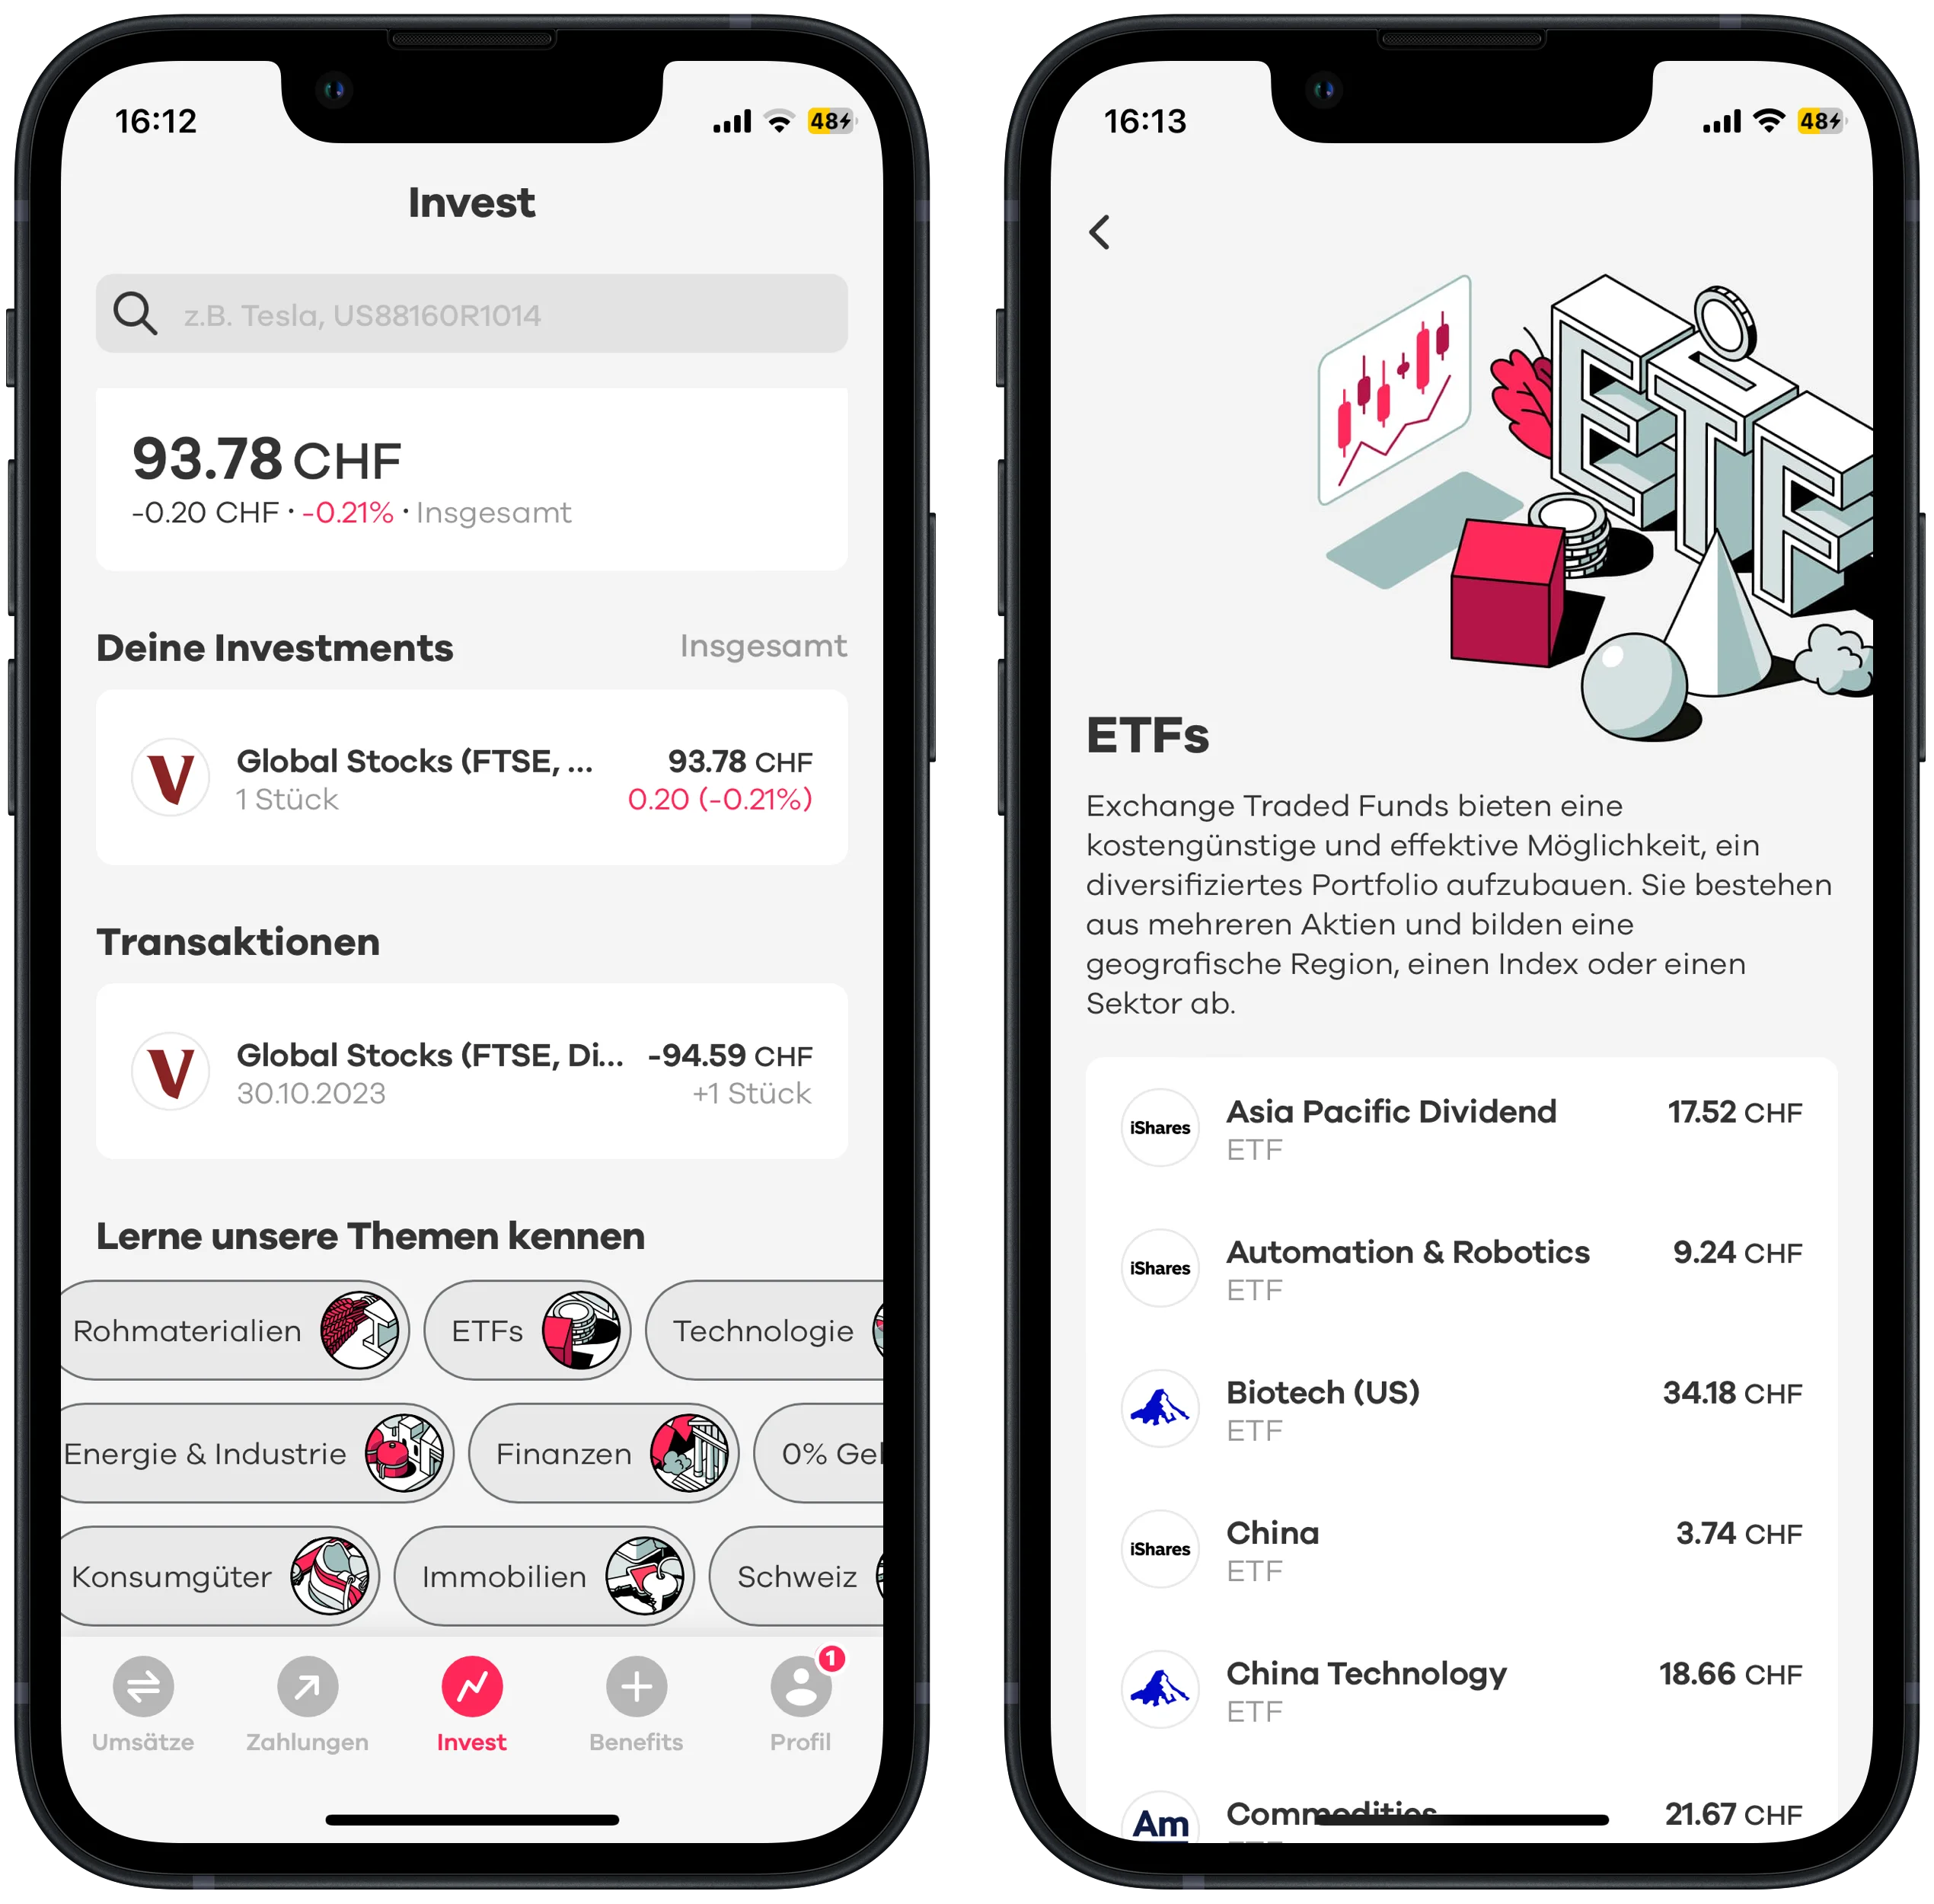
If you are not yet a neon customer, you can find the securities currently on offer in neon’s product list. New additions are highlighted in red. Unlike the app, this list lacks meaningful information such as the product costs (TER).
At least neon now shows the product name, including provider and index, as well as the use of dividends on its ETF list, so you can make a preliminary selection without further research.
How good is neon’s ETF selection?
Whether you are a beginner or a stock market pro, equity ETFs are equally well suited to return-oriented investors with a higher risk appetite and a longer investment horizon.
ETFs are our preferred investment vehicle, which is why we want to focus on them in this neon review.
Let’s start with the quantitative offering: with 130 ETFs, neon offers a solid selection for a neobank. That is a broader range than its main rival Yuh, but still well behind traditional trading platforms such as Swissquote, which cover several thousand ETFs.
But even neon’s currently still somewhat limited offering may be perfectly sufficient for you. In the end, all that matters is that the ETFs you want are included.
So let’s move on to the qualitative assessment:
As a rational investor, you are aiming for a broadly diversified global portfolio. Depending on your approach, you can build it with one ETF, with two ETFs (developed and emerging markets) or with several regional ETFs.
So much for the theory. How well can you put it into practice with neon?
The good news: with neon’s investment universe, you can easily build either a one-ETF global portfolio or a two-ETF solution (developed and emerging markets). We have linked each of the ETFs below directly to BX Swiss – neon’s only trading venue – where you can find further product details.
Options with 1 global ETF (selection):
- Vanguard FTSE All-World UCITS ETF Acc (accumulating, no purchase fees in the savings plan)
- Vanguard FTSE All-World UCITS ETF Dist (distributing)
- iShares MSCI ACWI UCITS ETF USD Acc (accumulating)
- Invesco FTSE All-World UCITS ETF Acc (accumulating, no purchase fees in the savings plan)
Options with 2 ETFs (developed and emerging markets):
Developed markets ETFs (selection):
- Xtrackers MSCI World UCITS ETF 1C (accumulating)
Emerging markets ETFs (selection):
- Vanguard FTSE Emerging Markets UCITS ETF USD (distributing)
- iShares Core MSCI Emerging Markets IMI UCITS ETF USD (accumulating)
- iShares MSCI EM SRI UCITS ETF USD (sustainable; accumulating)
Note that a currency exchange fee of around 1.5% applies to distributed foreign dividends that are converted from a foreign currency into CHF.
In terms of fees, investing with neon is therefore worthwhile above all for accumulating and/or Swiss ETFs.
In addition to the broadly diversified, market-cap-weighted “core ETFs” mentioned above and a fairly large selection of ETFs focused on “Switzerland”, neon’s range includes various specialist ETFs. These cover themes such as “real estate”, “energy”, “technology” or “commodities”.
BX Swiss, a small exchange – a drawback?
As little known as Bern’s BX Swiss (colloquially “Berner Börse” or “BX”) may be to many investors, it was founded back in 1884 and today is a regulated exchange supervised by the Swiss regulator FINMA. In 2018 it lost its independence and has since been a wholly owned subsidiary of Börse Stuttgart GmbH.
One special feature of neon is that all of its investment products can only be traded on a single exchange – BX Swiss. And on BX Swiss, all products offered, including around 750 ETFs, can be traded exclusively in the home currency, CHF.
The upside: you don’t have to exchange currencies, but you still carry the currency risk. To minimise this risk, you would have to invest only in Swiss shares or in ETFs holding only Swiss shares – which, in our view, would leave your portfolio insufficiently diversified.
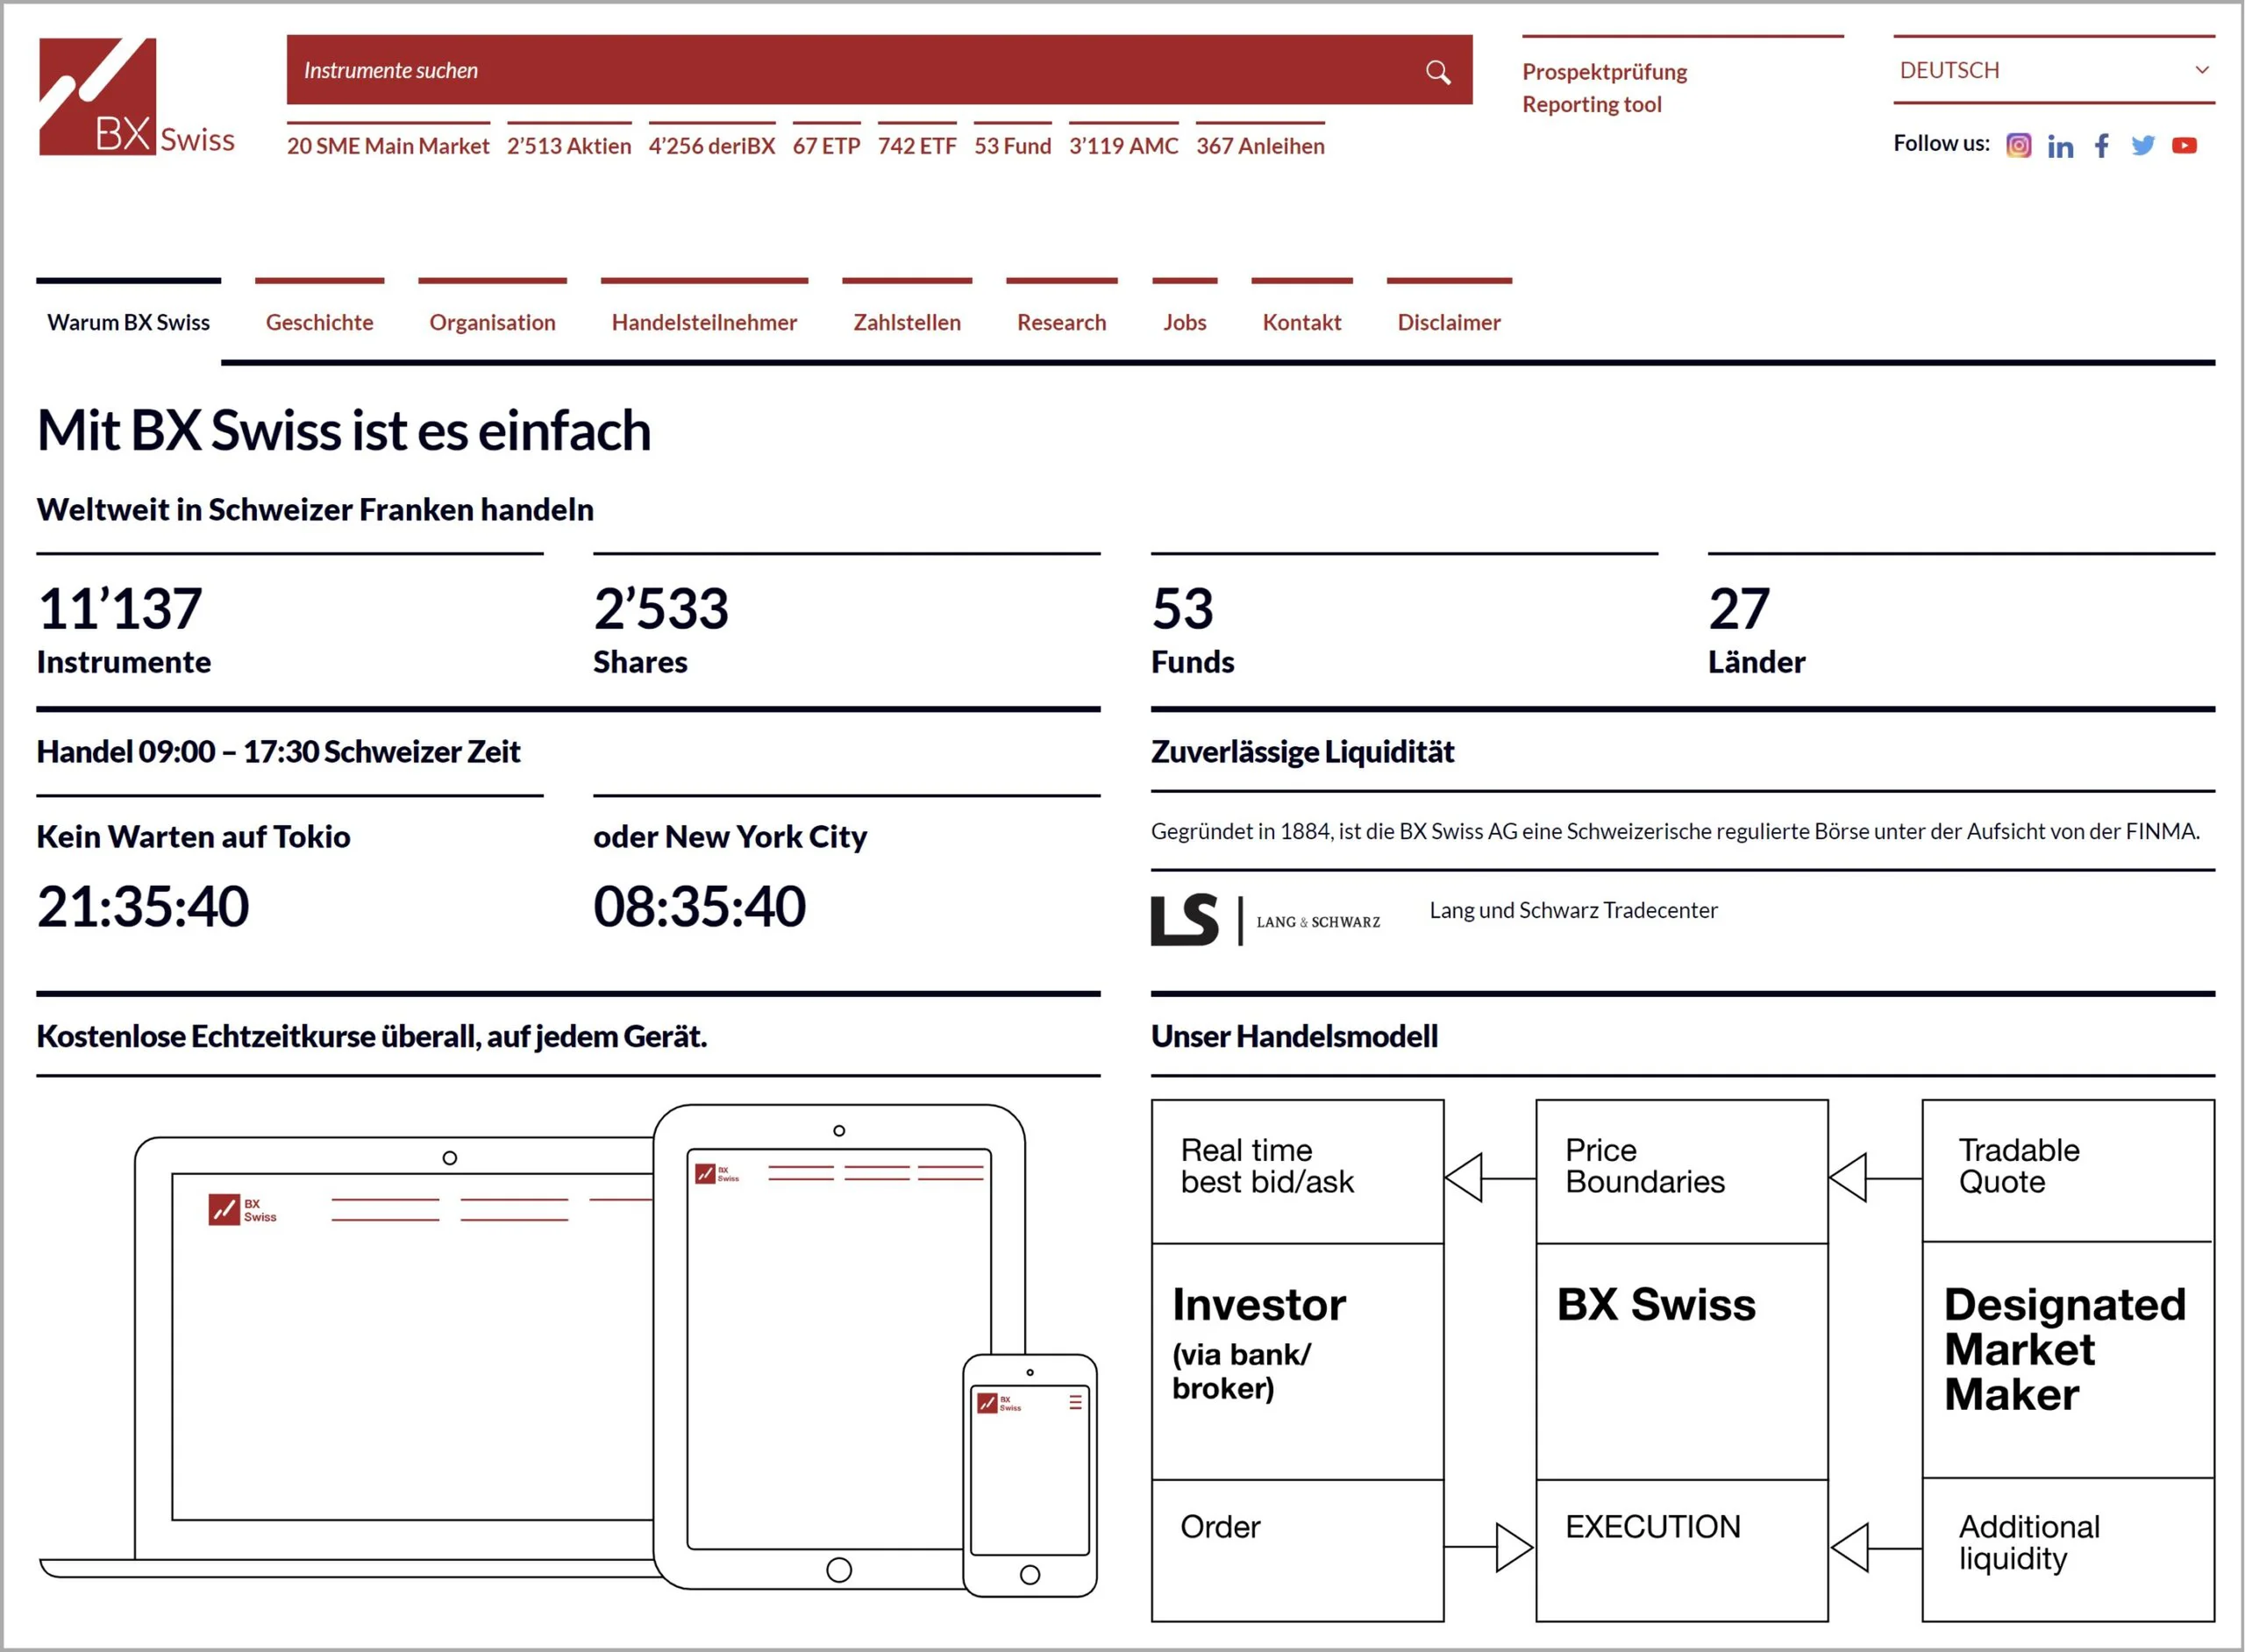
As we had no experience with BX Swiss before this neon review and wanted more clarity about this secondary exchange, we contacted Erhard Rüttimann, Market Controller at BX Swiss, and asked him the following two questions in writing:
Schweizer Finanzblog: Trading volumes for ETFs are often low on the small BX. Historically, what bid-ask spread should an investor expect with you, and is the spread comparable with the big exchanges thanks to market makers?
Erhard Rüttimann, BX Swiss: It’s true that trading volumes with us are often lower. Nevertheless, thanks to the support of our market maker (MM), we can offer competitive prices. The quality of the price is not affected by this. Our spreads are not wider, as our MM is also active on other exchanges and quotes competitive prices. Otherwise nobody would trade with us. Thanks to our MM, we can often provide more liquidity, too.
If all products on BX can only be traded in CHF, investors don’t need to exchange currencies. But the fund currency of ETFs covering foreign markets is usually not CHF. Do investors pay fees for these currency conversions? If so, which ones?
Correct, trading in CHF eliminates the need for investors to exchange currencies, which is one of the advantages. When converting into another currency to buy an ETF whose fund currency is, for example, USD, our market maker generally uses the interbank rate. The risks and costs this creates for the market maker are factored into the spread and are therefore already included in the price you see as an investor. The fees reflected in the spread by the MM are considerably lower than the costs that would arise if a bank bought directly on a foreign exchange.
Our verdict on investing with neon
Because of its linear cost structure (0.5% commission) and its still somewhat limited ETF range, we think neon is particularly suited to stock market beginners who want to gain their first experience of trading securities with smaller amounts and low fees.
But more experienced investors may also find neon appealing – for example, people who want to invest smaller amounts in their favourite ETF in addition to their traditional online broker and benefit from the competitive prices.
No minimum fee and no currency exchange when trading, and therefore no related fees, are positives.
neon’s investment universe is quite convincing for a neobank. In terms of costs (TER), market success (fund assets) and diversification, it includes some absolute top ETFs.
The small BX Swiss as the sole trading venue is certainly not a plus. But if the market maker still ensures liquidity at all times and the spread is only a few basis points, this is not a deal-breaker for us.
Finally, we see it as a plus that neon’s savings plan lets you invest regularly and automatically in ETFs or shares, in some cases even without purchase commission, but so far still without fractional trading.
neon Pillar 3a – simple and low-cost
With its new Pillar 3a solution, neon offers a retirement savings solution that is fully integrated into the app. Opening an account takes just a few minutes, entirely digitally, with no additional accounts or paperwork. neon’s partners for the 3a solution are the pension foundation simply3a and Descartes Finance.
The fees are transparent and among the lowest on the market: 0.45% p.a., falling to 0.39% p.a. from CHF 50,000. The money is invested passively in Swisscanto index funds. You can choose from five investment strategies with equity allocations between 25% and 100%, optionally with a Swiss or sustainability focus.
Besides the relatively low costs, another advantage is the simple, clean integration into your existing neon banking: everything in one app, clear structure, easy to use. If, on the other hand, you are looking for maximum flexibility in your investments, you will find more choice with pure robo-advisors such as VIAC.
How good is neon’s support?
Personal contact is not part of neon’s concept. There are simply no branches where you could meet in person. But neon also keeps phone contact to a minimum.
Based on our experience with neon, you basically have three different free channels for questions:
- Online help centre: here you will find lots of FAQs, clearly organised by topic.
- AI-powered support: instead of the previous phone support, this AI feature is offered as a beta version.
- Written support: the more specific your request, the more likely you are to get what you need by emailing [email protected]. In our experience with neon, the answers were always of good quality and the waiting times pleasingly short, i.e. the same day or the next working day.
Phone support is now only available with the paid plans neon plus, neon global and neon metal.
How do I sign up with neon?
Before you sign up with neon, check that you meet all the requirements:
- Minimum age 15
- Resident in Switzerland
- Tax liability in Switzerland only
- A valid ID from one of these countries (combined with a B/C residence permit for non-Swiss nationals).
Next, download the neon app and follow the instructions using your passport or ID card (and B/C residence permit).
In around 10 minutes you enter your personal details (don’t forget the promo code “neonSFB”!), confirm them via a free video call or via photo ID check (our recommendation, as it is available around the clock) and set your login code.
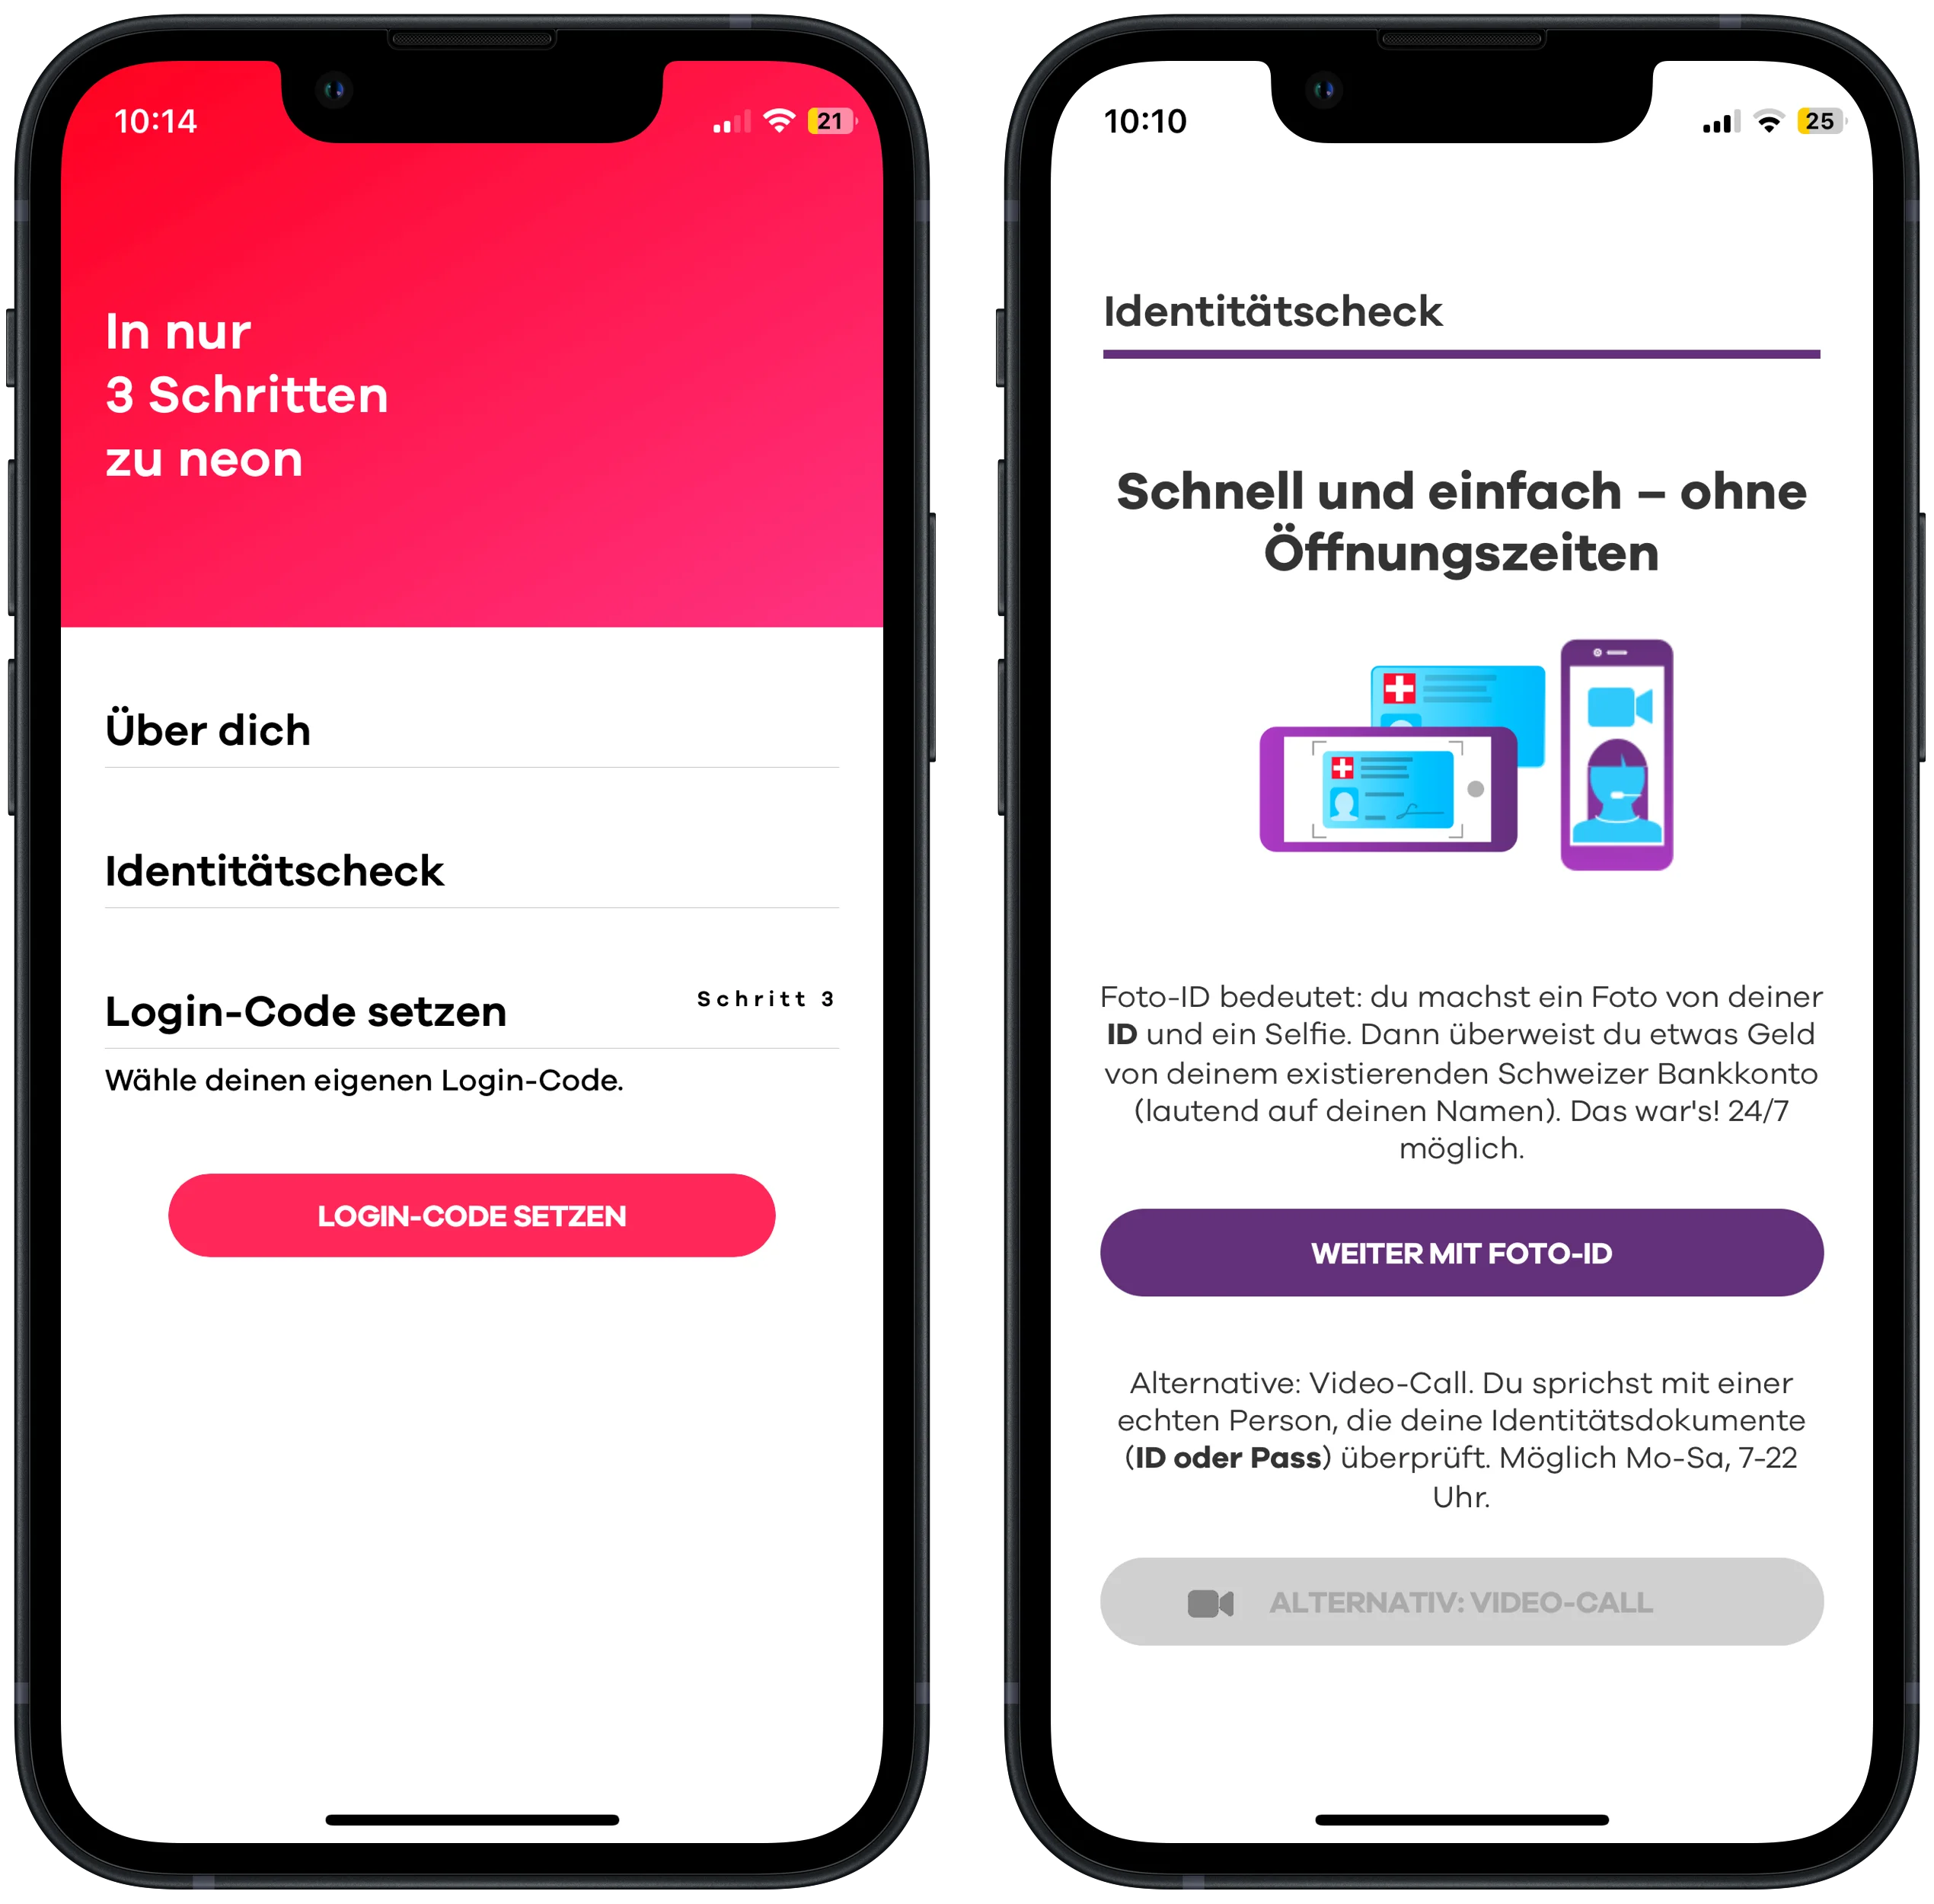
As soon as you have transferred some money from a Swiss bank account in your name, your identity check (for the photo ID option) is complete and your neon account is activated!
The upside: neon only asks you for the legally required data and doesn’t ask detailed questions about your income and assets or your working hours. Once your account has been activated, your physical neon card (Mastercard debit card) is sent to you separately by post within a few days. You retrieve the PIN directly in the app. Before you can use the card, you have to activate it in the app.
How safe is neon?
Your cash, whether for paying or saving, is held at the state-regulated Hypothekarbank Lenzburg and is protected by deposit insurance of CHF 100,000 in the event of bankruptcy.
ETF investments are of course subject to market risk, but they count as segregated assets and therefore do not form part of the bankruptcy estate.
To protect effectively against fraud and unauthorised access, neon relies on two-factor authentication – according to neon, the most widely used security standard in online banking and one considered secure.
After you open your account, your phone is verified (factor 1). In addition (factor 2), you can only access your account with a six-digit login PIN or (more easily) via biometric authentication using facial recognition (Face ID) or fingerprint.
Once logged in, you can only approve transfers with a six-digit transfer PIN, which gives you extra protection.
Card payments work the same way: on the one hand, you need the neon card, whether physical or digital on your phone (factor 1). On the other hand, the transaction can only be approved with a PIN or biometric authentication (factor 2).
Finally, if you suspect fraud, you can quickly block your card directly in the app.
Why neon – and when Yuh might be the better choice?
The best way to size up neon is to compare it with its biggest competitor and market leader Yuh: neon stands out in particular with significantly lower fees for card payments abroad – 0.35% with neon free compared with 0.95% at Yuh. Another plus: when investing, neon charges no currency exchange fees, as all investment products are traded in the home currency, CHF.
Yuh, in turn, scores with multi-currency accounts and fractional trading.
One striking difference lies in the account model: while Yuh offers one standard account for everyone, neon relies on a differentiated choice of accounts – from free (neon free) to premium options such as neon metal.
As neither neon free nor Yuh charges ongoing account or custody fees, the two offers can be combined without any problems. That way, you can benefit from the best of both providers at no extra cost – depending on your needs for paying, saving, investing or retirement saving.
Regardless of the comparison with Yuh, we have summarised the key pros and cons of neon free for you below.
Pros and cons of neon free
 Paying, saving and investing from a single provider, simply via your smartphone Moderate 0.35% currency exchange fees on card payments abroad Investing in ETFs at low fees for small amounts of up to CHF 1,000 Investing with no minimum amount and no minimum fee (flat 0.5%); with promo code neonSFB, get up to CHF 100 in trading credits for free Automated investing via savings plan, partly without purchase commission (but no fractional trading) Investing without currency exchange, as all products can be traded in the home currency, CHF Low-cost Pillar 3a solution fully integrated into the app, with total costs of 0.39%–0.45% p.a. Swiss provider with deposit insurance of CHF 100,000
 No multi-currency accounts Too expensive for larger investment amounts due to linear pricing (exception: commission-free ETFs) No fractional trading
Final verdict from our neon review
neon is aimed at anyone who wants to handle banking and investing simply, digitally and cheaply. neon is particularly strong for card payments abroad: with neon free, you only pay a currency exchange fee of 0.35%, and with neon plus (CHF 20/year) it disappears completely. Two cash withdrawals per month are also included there.
When it comes to investing, neon impresses with a clear pricing structure: no custody fees, 0.5% commission on ETFs and Swiss shares (1% on foreign shares). A plus: all trades are executed in CHF via BX Swiss – no currency exchange needed. Savings plans are available, and selected ETFs are even commission-free. For investment amounts of up to around CHF 1,000 in particular, neon is very attractively priced.
We also rate the new neon 3a solution positively: it is fully integrated into the app and, with total costs of 0.39–0.45% p.a., is one of the more affordable offers.
neon is less suitable for traditional savers with large balances. And if you want to use a multi-currency account, you are better off with Yuh – neon currently only offers a CHF account.
As a free second account with no strings attached, neon free can easily be combined with your main bank, another smartphone bank or an online broker – for more flexibility at no extra cost.
You might also be interested in
Updates
2026-05-19: Investment universe updated with newly added Vanguard ETFs without purchase fees.
2026-01-16: Article comprehensively updated.
2025-11-25: New neon Pillar 3a solution presented.
2025-05-21: Comprehensive revision following the introduction of new neon plans and conditions.
2025-01-31: New promo code “neonSFB” with up to CHF 100 in trading credits mentioned.
2025-01-14: Comprehensive update: how the new joint account works clarified, investment universe updated, savings interest rate adjusted and other selective improvements made.
2024-10-31: Note on further interest rate cuts added.
2024-10-03: Note added that the previous Mastercard prepaid card has been replaced by the new, more widely accepted Mastercard debit card.
2024-07-01: Interest rate on savings lowered to 0.5% (from 0.75%).
2024-06-13: New section on the neon savings plan, plus a note that selected ETFs are only commission-free within the savings plan.
2024-05-22: Interest rate on savings lowered to 0.75% (from 0.9%).
2024-04-23: Launch of the “neon duo” joint account mentioned.
2024-04-05: Minimum age lowered to 15 (from 16).
2024-01-09: Note on fees for foreign distributed dividends added.
2023-11-13: Minor adjustments made: Google Pay (instead of Google Wallet); EUR and USD removed from interest
Disclaimer
Transparency note: neon’s overall package convinced us, which is why we have entered into a partnership with neon. With the promo code neonSFB, you can claim a welcome bonus in the form of trading credits worth CHF 100 and support our blog at the same time. To report credibly, realistically and first-hand, Toni and Stefan became new neon customers as part of this neon review.
Disclaimer: Investing involves the risk of losses. You have to decide for yourself whether or not you want to take these risks.
Errors excepted: We have written this article about our experience with neon to the best of our knowledge and belief. Our aim is to provide you as a private investor with information on finance that is as objective and meaningful as possible. Should we nevertheless have made mistakes, forgotten important aspects or should information no longer be up to date, we would be grateful if you let us know.
About the authors
Stefan Huser
Stefan has been investing in the stock market himself since 2015. He has been shaped by Markowitz’s portfolio theory and Gerd Kommer’s book “Souverän investieren”. He follows a core-satellite strategy: a global equity portfolio of ETFs forms the core, complemented by alternative investments. At the blog, he mainly takes care of the writing. Stefan lives with his family in Zurich and is interested in literature, photography and financial freedom.
Antun Brcina
Antun (“Toni”) has been investing in the stock market since 2015. Financially, he has been particularly inspired by Gerd Kommer’s book “Souverän investieren” and the Fama-French five-factor model. His money is invested in a broadly diversified, long-term global equity portfolio of ETFs. At the blog, he mainly works on the calculators and the code. Toni lives with his family in the Zurich area and is interested in sports, technology and entrepreneurship.

6 Comments
Ganz neu ist auch ein Fondssparplan (FSP) mit 1-3 Fonds möglich. Gebührenstruktur und Fondsauswahl sind m.E. top für kleine Sparbeträge (100-500.- p.m.). Was mich nun nach weiteren Alternativen umschauen lässt: Keine Fraktionen, nur ganze Titel/Anteile. Da verpufft der DCA bei Kleinstbeträgen, was m.E. ein grosser Mehrwert eines FSP’s darstellt. Ich warte gespannt auf die Antwort vom Support, wann sie das ändern mögen…
Merci für den Hinweis. Wir haben soeben diese neue neon Sparplanmöglichkeit genauer unter die Lupe genommen und den Artikel entsprechend aktualisiert.
Bei ausländischen Dividenden fallen 1.5 % Wechselgebühren an. Das ist eine hohe Gebühr. Oder wie siehst du das?
Einverstanden, das ist eine hohe Gebühr. Wir nehmen diesen Punkt im Artikel auf und schlagen vor: bei neon vorzugsweise nur in thesaurierende und/oder inländische ETFs investieren.
Auf unsere Anfrage schreibt uns neon am 8.1.2024 zur Gebühr auf ausländischen Dividenden: “Dividenden, Nennwertrückzahlungen, etc. werden direkt von unserer Partnerbank auf deinem neon-Hauptkonto gutgeschrieben. Wenn es bei einer ausländischen Wertschrift (z.B. US-Aktie in US-Dollar) zu einer Ausschüttung wie etwa einer Dividende kommt, dann nimmt unsere Partnerbank die Umrechnung in CHF vor und schreibt den CHF-Betrag deinem neon-Hauptkonto gut. Der Wechselkurs für die Umrechnung wird von unserer Partnerbank mindestens zwei Mal am Tag aktualisiert und beinhaltet eine Interbankenkursmarge von ca. 1.5%.”
Vielen Dank für die Erklärung. Ist es also korrekt, dass die Kurswechselgebühr im Vergleich zu Saxo, wo sie 0.25% beträgt, relativ hoch ist? Obwohl viele ETFs in USD aufgelegt sind, werden sie in der neon-App in CHF gekauft und verkauft. Sind da jedes Mal noch die 1.5% versteckt?
Vielen Dank für eine Einschätzung deinerseits und liebe Grüsse
Flo
Hoi Flo
Korrekt, bei neon werden alle ETFs in Handelswährung CHF gehandelt. Dies erachten wir aber als einen Vorteil, denn der Währungswechsel beim Kauf und Verkauf von ETFs entfällt so bei neon.
Beste Grüsse
SFB