
 Newsletter
In 2018, the Swiss Bank Cler launched Zak, an innovative banking solution never before seen on the Swiss market: free and hassle-free on your smartphone. It’s been a good year since we first wrote about Zak. Since then, a lot has happened at Switzerland’s first mobile banking app. In this comprehensive Zak online bank Switzerland update, you’ll find out which innovations this smart Swiss neobank has to offer and whether it’s right for you.

In a nutshell
- In early 2018, the Swiss Bank Cler launched Zak, Switzerland’s first neobanking app.
- With Zak, account management, payments and the Visa debit card are free of charge.
- Zak offers deposit insurance of CHF 100,000 per customer.
- The Zak private account pays 0.75% interest on balances up to CHF 25,000 (as of 5 May 2023).
- With eBill, you can pay bills efficiently in the Zak app.
- At Zak, fees essentially only apply when foreign currencies are involved, be it for card purchases abroad (exchange rate markup of approx. 0.5%), cash withdrawals or payments (approx. 2% fee!).
- Thanks to digital savings pots, you can conveniently plan your finances on your smartphone, whether for everyday household expenses or special purchases.
- Zak has no foreign currency accounts and no trading functions.
- Zak offers efficient free support.
- Zak is ideal for all digitally savvy savers who want to do their everyday banking free of charge (in their home currency, CHF) and conveniently on their smartphone.
Contents
- Preliminary remarks on this Zak online bank Switzerland update
- What is Zak?
- Who owns Zak?
- When was Zak founded?
- What improvements has Zak made since our last review?
- How safe is Zak?
- How can I open an account with Zak?
- What basic services does Zak offer?
- What additional services does Zak offer?
- How do the services of Zak and Zak Plus differ?
- How does Zak make money and which services are free?
- How good is Zak’s support?
- Who is Zak particularly well suited for?
- Who is Zak not suitable for?
- You might also be interested in
- Updates
Preliminary remarks on this Zak online bank Switzerland update
End of our partnership with Zak: As of 31 October 2023, the partnership of several years between this blog and Zak was ended by mutual agreement. Instead, we have entered into new partnerships with the Swiss market leaders Yuh and neon. We believe that these two leading neobanks are not only more successful on the market, but currently also clearly offer the more attractive package. We have compiled the most important terms on our recommendations page, including promo codes.
Scope: This review covers Zak, an app-based banking solution from Bank Cler. Bank Cler services that are not offered for Zak are not covered by this review.
Errors excepted: We researched this Zak online bank Switzerland review to the best of our knowledge and belief. Our aim is to present as objective and meaningful a snapshot as possible to help you choose your bank. Should we nevertheless have made mistakes and/or overlooked important aspects, you are warmly invited to let us know how we can improve.
What is Zak?
Zak is a Swiss mobile banking app that lets you save, pay, shop, plan for retirement and handle other financial matters.
Who owns Zak?
Zak is a product of Bank Cler. Bank Cler is a Swiss bank headquartered in Basel and, since 2019, a subsidiary of Basler Kantonalbank.
When was Zak founded?
On 27 February 2018, Bank Cler launched Zak, Switzerland’s first neobanking app.
What improvements has Zak made since our last review?
Zak keeps evolving. Since our last Zak review in May 2021, the following innovations have particularly impressed us:
- Introduction of eBill for efficient payments
- Launch of the Zak Visa debit card: one card for everything, on fair terms
- Abolition of the 1.2% processing fee for card use abroad
- More flexible saving options thanks to the optimization of the clever financial planning feature “Savings Pots”
- New partnership with LINGS for insuring items by the day
We’ll explain these improvements in more detail later in this review.
How safe is Zak?
The following arguments point to a high level of security:
- Zak is backed by an established Swiss bank – Bank Cler. In other words, unlike competitors from Switzerland and abroad, Zak is not a start-up or fintech.
- Bank Cler is supervised and monitored by the Swiss Financial Market Supervisory Authority (FINMA).
- Like every bank and securities firm in Switzerland, Bank Cler is required to protect deposits up to a maximum of CHF 100,000 per customer.
- Zak uses SSL encryption and two-factor authentication for larger transactions. Specifically, for amounts of CHF 5,000 or more, you receive a code on your smartphone via PushTAN. This code is the security element for logging in and signing payments.
How can I open an account with Zak?
Stefan and Toni have been happy Zak customers for over a year now. That means we opened our accounts quite a while ago. So we’ll just say this much here: the account is opened entirely online on your smartphone – in less than 15 minutes.
You can find the seven steps of the sign-up process in our first Zak review.
What basic services does Zak offer?
The basic services include the Zak private account, the Zak Visa debit card and payments. The good news: most of the related services are free. Below, we take a closer look at these three banking services:
Zak private account
With Zak, you get a free private account. This means you pay no annual fees for account management.
Zak gives you just one account, held in your home currency, CHF.
Your private account earns 0.75% interest on balances up to CHF 25,000 (as of 5 May 2023).
However, you can divide your account by theme into so-called “Savings Pots” and “Shared Pots”. Thanks to this handy feature, you can plan your finances – be it your everyday household expenses or special purchases – simply and transparently.
What’s new is that you can now save on any calendar day of the month, with or without a predefined savings amount. To illustrate, we’ve put together the following examples:
- Savings pot “Coffee kitty & co.”: Save CHF 5 a day for the “coffee to go” you didn’t drink
- Savings pot “Mobility”: put aside CHF 20 every Wednesday for your public transport pass
- Savings pot “Island escape”: put aside CHF 100 on the 25th of each month for your holidays
- Savings pot “Dream bike”: set aside CHF 200 a month for a year for an e-bike
- Shared pot “Summer party”: make sure your shared-flat party is jointly funded by the end of the month. Here’s how it works: the co-organizers enter their expenses in the “Shared Pot”. This way, everyone can see at a glance who paid what and who owes whom how much. No more tedious calculating and collecting receipts. The debts can then be settled with a single click. To use the Shared Pot, you need a Zak account.
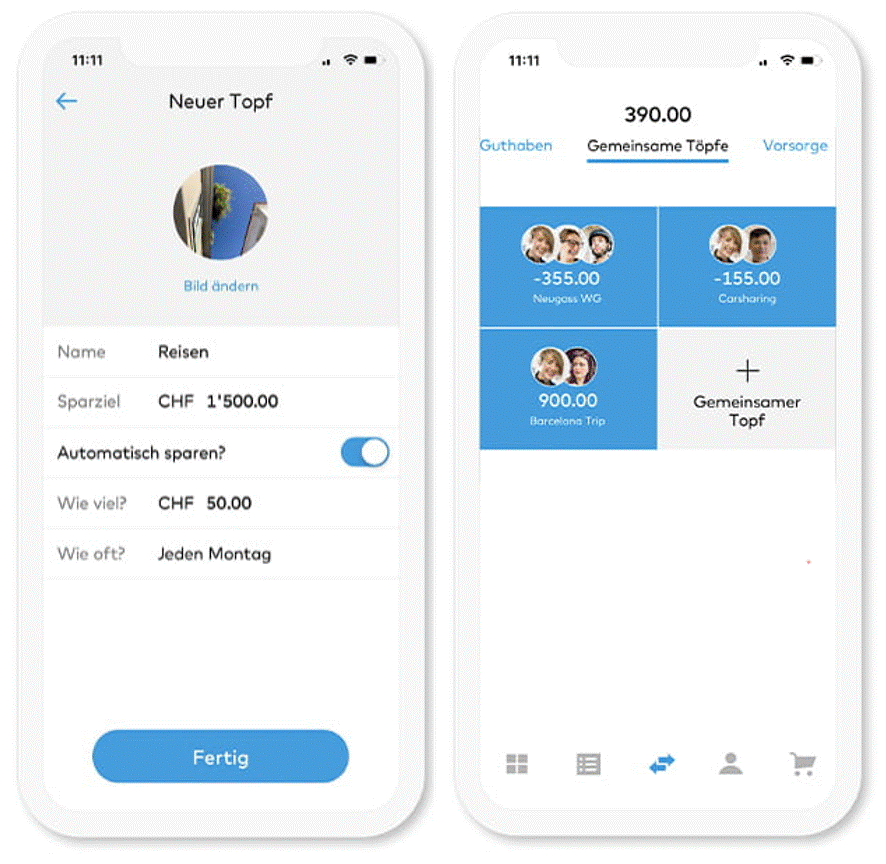
The following video tutorial clearly explains Zak’s pot system.
Zak Visa Debit: one card for everything
Finally, Zak has put an end to the card jungle: instead of a credit card, Maestro card and prepaid card, there’s now the Zak Visa debit card for everything.
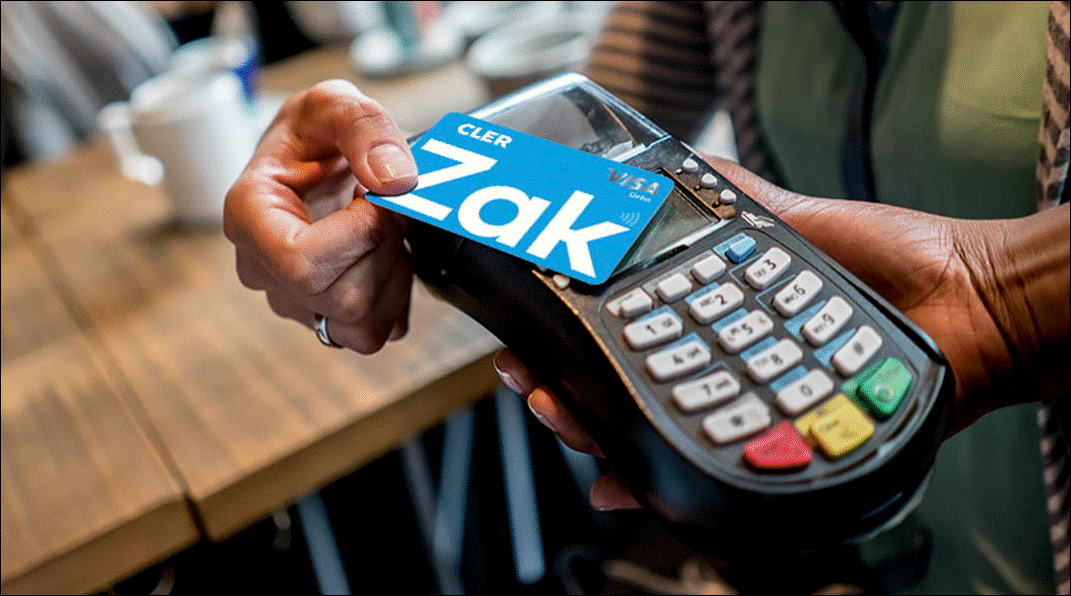
It lets you make payments worldwide – online and in shops. And if a physical card is too cumbersome for you, you can store the Zak Visa Debit in your smartphone’s digital wallet and pay conveniently with Apple Pay, Google Pay or Samsung Pay.
Full overview of your finances: all card payments are debited directly from your account and displayed in the “My transactions” menu.
It’s important that your account balance always stays positive. Unlike with a credit card, overdrafts – and the high interest payments that come with them – are not possible with the debit card.
Optionally, you can also request a push notification for every transaction. And you can assign your payments to your pots right away.
Good news: with this new debit card, you pay no annual fee. Payments in Switzerland are also free, and there are no additional processing fees abroad either. Finally, cash withdrawals at Bank Cler ATMs are free of charge.
There are only three situations in which fees apply when using the Zak Visa Debit card:
- Exchange rate markup of approx. 0.5% on purchases in foreign currencies, based on the Visa reference rate. (An improvement over the previous Zak Visa prepaid card, which charged a foreign currency surcharge of 1.2%, and cheaper than many competitors.)
- Cash withdrawals at third-party ATMs: in Switzerland, a fee of CHF 2 per withdrawal in the home currency or CHF 5 per withdrawal in euros is charged. Abroad, there is generally a fee of CHF 5 per withdrawal. (These fees do not apply with the Zak Plus account model for CHF 8/month.) Euro withdrawals are also based on the Visa reference rate plus an exchange rate markup of approx. 0.5%.
The last two cost items can be avoided, which is why we don’t consider them relevant.
Payments
Single payments entered manually or via QR code, standing orders and direct debits (LSV) are free at Zak.
Also new and free of charge, Zak offers the handy eBill service – the digital invoice for Switzerland. It lets you check and pay bills in just a few clicks.
Foreign payments within the SEPA area are free in the home currency, CHF. Transfers in euros are made with an automatic currency conversion at Bank Cler’s daily rate. For our test transfer on 4 July 2022, an EUR/CHF exchange rate of 1.02204 was applied, which corresponds to a (too high) margin of around 2% (!).
Payments at Zak are subject to the following two restrictions:
- The total of all payment orders (including standing orders) is limited to CHF 25,000 (or equivalent) per week.
- Payments outside the SEPA area and payments in currencies other than CHF and EUR are not possible.
Incoming payments in CHF are free. Incoming payments in foreign currencies are automatically converted into CHF at Bank Cler’s daily exchange rates.
Based on four test transfers in euros and US dollars to the Zak CHF account, the following exchange rates were applied:
- EUR/CHF 0.99176 (value date 28 June 2022) and 0.98098 (4 July 2022)
- USD/CHF 0.93492 (28 June 2022) and 0.94178 (5 July 2022)
Compared with the precise interbank rates from the SIX currency converter, Zak’s exchange rates include a margin of around 2% (!), which is very high by comparison. Zak confirmed this figure when we asked.
Finally, for “internal” payments, Zak offers the optional “Zak Instant” plug-in. Once it’s activated, Zak customers can send each other money in real time – just like with Twint.
What additional services does Zak offer?
Yes, the Zak app can do more than the basic services mentioned above. It also covers topics such as retirement savings, insurance, shopping and the paid Zak Plus service package. We take a closer look at these below:
Retirement savings
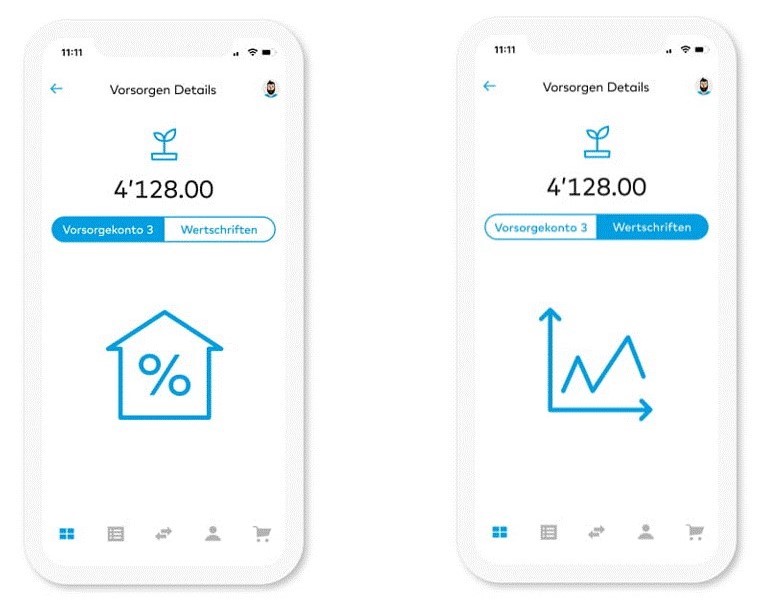
Saving for retirement in Pillar 3a is attractive from a tax perspective. Zak offers two models for this, which can also be combined: “Pension Account 3” and “Securities”. (The following comments on the investment horizon are not recommendations from Zak, but reflect our conviction that you shouldn’t invest in the volatile “equities” asset class over the short term.)
If you have a shorter investment horizon, e.g. because you want to buy a home in three years or emigrate next year, you’ll probably prefer “Pension Account 3”. This option isn’t exposed to market turbulence, as only cash is held. The current interest rate is 0.10%. There are no fees.
If, on the other hand, you have a longer investment horizon, Zak offers three sustainable investment solutions with securities as an alternative or in combination. The custody account and all transactions are free. The ongoing costs (TER) amount to 1.25% of the invested amount per year. That seems relatively high to us, which is why we recommend comparing competitors before signing up for this retirement solution.
Insurance
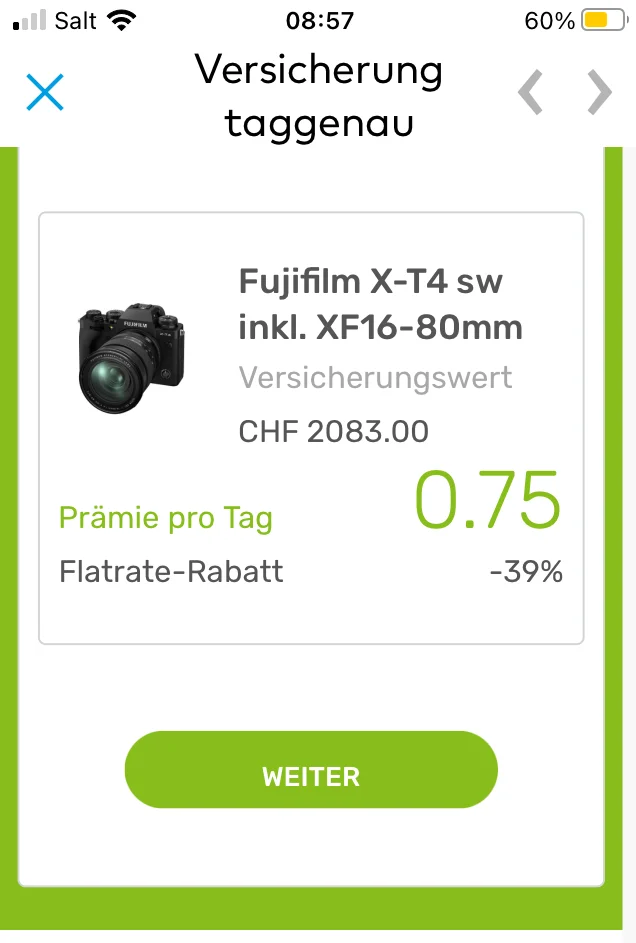
Zak has recently partnered with the innovative insurer LINGS. What makes it special is that you can insure your favorite belongings by the day.
For Stefan, a passionate amateur photographer, insuring his camera and lens for a one-day photo shoot costs, for example, just 75 centimes (see Figure 6). A fair deal!
Health, travel luggage and cyber insurance round off Zak’s insurance offering.
Shopping
Bargain hunters will find new offers all the time in the app under “Zaktion”, such as a JBL Go 3 mini speaker for CHF 33.00 instead of CHF 46.90.
Zak Plus – paid additional services
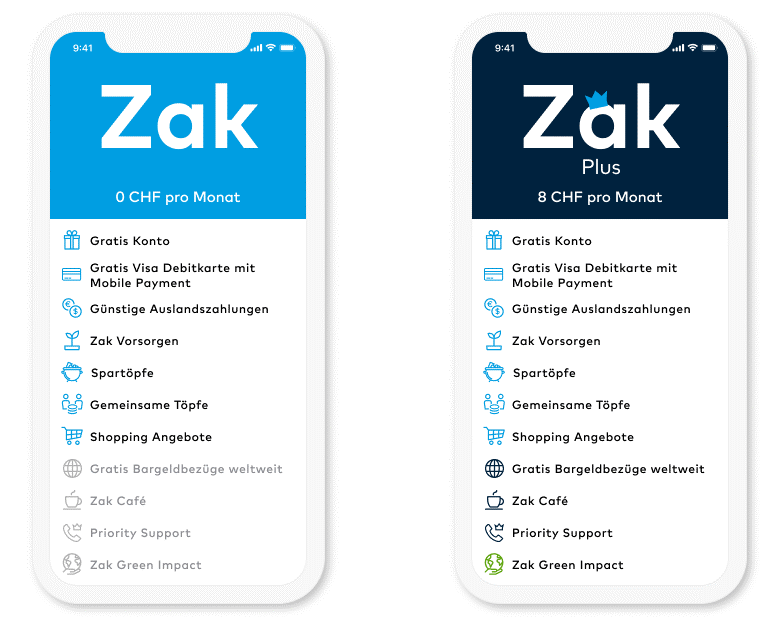
“The perfect offer for anyone who wants to stay flexible. Climate protection included.” At least, that’s how Bank Cler promotes this service package for CHF 8 a month.
“Flexible” here means unrestricted access to all ATMs worldwide on favorable terms.
And “climate protection included” refers to the 0.2 centimes that Zak donates to climate protection for every franc Zak Plus customers spend with their card. In other words, in the spirit of “spend money with a clear conscience”. Specifically, it goes to a climate protection project that changes every year as part of the Zak Green Impact Initiative.
Finally, Zak Plus customers get a free coffee at Bank Cler branches.
How do the services of Zak and Zak Plus differ?
The following figure compares the range of services of Zak and Zak Plus.
How does Zak make money and which services are free?
In the table below, you’ll find the prices for all key services of the two account models, Zak and Zak Plus.
| Services | Zak | Zak Plus | Remarks |
|---|---|---|---|
| Private account Zak | |||
| Account management | gratis | 8 CHF per month | |
| Interest rate | 0,00% | 0,00% | Account overdrafts are not possible |
| PDF account statement as at 31.12. | gratis | gratis | |
| PDF account statement, monthly | gratis | gratis | |
| Restriction on withdrawal | none | none | |
| Zak Visa debit card | |||
| Cash withdrawals at Bank Cler ATMs - from CHF - from EUR | free of charge approx. 0.5% exchange rate surcharge | free of charge approx. 0.5% exchange rate surcharge | based on visa reference course |
| Cash withdrawals at foreign ATMs in Switzerland - from CHF - from EUR | 2 CHF per purchase 5 CHF per purchase plus approx. 0.5% exchange rate surcharge | free of charge approx. 0.5% exchange rate surcharge | based on visa reference course |
| Cash withdrawals at ATMs abroad | CHF 5 per purchase plus approx. 0.5% exchange rate surcharge | approx. 0.5% exchange rate premium | based on visa reference course |
| Pay for purchases - in Switzerland - abroad | free of charge approx. 0.5% exchange rate surcharge | free of charge approx. 0.5% exchange rate surcharge | based on visa reference course |
| Card blocking - temporary via app - permanent via customer advisor | free of charge 50 CHF | free of charge 50 CHF | |
| Replacement card | 20 CHF | 20 CHF | |
| Payment transactions | |||
| Incoming payments - in CHF - in foreign currencies | free of charge at the daily rate from Bank Cler | free of charge at the daily rate from Bank Cler | Exchange rate margin of approx. 2% |
| Payments, standing order and LSV in Switzerland in CHF | gratis | gratis | |
| Payments and standing orders in Switzerland in euros | at the daily rate of Bank Cler | at the daily rate of Bank Cler | Exchange rate margin of approx. 2% |
| Payments and standing orders abroad in euros | at the daily rate of Bank Cler | at the daily rate of Bank Cler | Exchange rate margin of approx. 2%; Payments outside the SEPA area not possible |
As Table 1 shows, Zak’s basic services – account management, payments and card use in Switzerland – are free.
You incur costs whenever foreign currencies are involved, whether for purchases abroad, cash withdrawals or payments.
The price differences between the Zak and Zak Plus account models are modest. For the monthly account fee of CHF 8 for Zak Plus, you essentially get more flexibility with cash withdrawals.
Specifically, Zak Plus saves you the fixed fees on all cash withdrawals at third-party ATMs (i.e. non-Bank Cler ATMs) in Switzerland and abroad.
Conversely, this means: if you mainly pay by card or don’t rely on (third-party) ATMs in Switzerland and abroad, you’re definitely better off with the free Zak account model.
How good is Zak’s support?
In general, we recommend sending all queries to Zak’s chatbot in the app first. That way, standard questions that are simple (for it) can be answered immediately.
If it can’t help, it kindly refers you to the hotline of Bank Cler’s human support team.
We’ve found this free hotline for more specific queries to be fairly efficient (expect to spend a few minutes on hold), always in Swiss German, always friendly and mostly competent. The latter naturally depends on the person you speak to.
You can find more information about Zak’s support in our first Zak review.
Who is Zak particularly well suited for?
Zak is ideal for all digitally savvy savers who
- value an app-based Swiss banking solution with deposit insurance of CHF 100,000;
- don’t want to pay annual fees for a private account and debit card;
- make their everyday payments and/or receive incoming payments mainly in Switzerland and in their home currency, so that no costs are incurred;
- want to handle payments as efficiently as possible using QR codes and eBill;
- want to benefit from a clever financial planning feature thanks to Zak’s “pot system” – optional and free;
- last but not least, appreciate capable, (Swiss) German-speaking telephone support provided by Bank Cler.
Who is Zak not suitable for?
If you value one or more of the following four services, we can’t recommend Zak to you:
- Foreign currency accounts: Zak only offers a private account in CHF. This means foreign currency transactions at Zak always go through the CHF account with automatic currency conversion.
- Dollar transfers: Zak only allows outgoing payments in CHF and EUR. However, incoming payments in dollars and other foreign currencies are no problem.
- Worldwide transfers: Zak’s payments are limited to the European SEPA area. (This doesn’t apply to the Visa debit card, which can of course be used globally.)
- Trading: Zak doesn’t offer any trading functions. However, Zak combines perfectly with established brokers such as Interactive Brokers or DEGIRO (get a CHF 100 bonus with this link).
You might also be interested in
Updates
2023-10-31: Added a note on the end of the partnership and on neobank alternatives.
2023-05-05: Interest rate updated to 0.75%.
2023-02-16: Added the “In a nutshell” text block; mentioned the new interest rate of 0.4%.
About the authors

Stefan Huser
Stefan has been investing in the stock market himself since 2015. He has been shaped by Markowitz’s portfolio theory and Gerd Kommer’s book “Souverän investieren”. He follows a core-satellite strategy: a global equity portfolio of ETFs forms the core, complemented by alternative investments. At the blog, he mainly takes care of the writing. Stefan lives with his family in Zurich and is interested in literature, photography and financial freedom.

Antun Brcina
Antun (“Toni”) has been investing in the stock market since 2015. Financially, he has been particularly inspired by Gerd Kommer’s book “Souverän investieren” and the Fama-French five-factor model. His money is invested in a broadly diversified, long-term global equity portfolio of ETFs. At the blog, he mainly works on the calculators and the code. Toni lives with his family in the Zurich area and is interested in sports, technology and entrepreneurship.








2 Comments
Vielen Dank für den Artikel. Ich wollte mir Zak schon länger mal anschauen. Ich nutze aktuell ‚immer noch’ Neon und bin damit eigentlich auch zufrieden. Sehe aktuell aufgrund des Artikels auch keine gravierenden Vor- oder Nachteile die jetzt klar und eindeutig für das eine oder andere Angebot sprechen.
Grüsse
Martin
ZAK macht vieles gut, aber was ich echt nervig finde, das man jede einzelne Transaktion mit einem mTAN SMS bestätigen muss. Und für die Sicherheit bringt das doch eh nichts, denn wenn jemand Zugriff auf mein Natel hat, kann man auch die SMS lesen.