 Newsletter

As climate change and its enormous costs take hold, ever stricter environmental laws are coming into force around the world. Sustainability has long since become a megatrend that permeates society and the economy alike.
In this in-depth article, we show you what impact buying “green stocks” actually has on the environment, whether you have to accept lower returns, and which “green stocks” in the form of sustainable ETFs we consider particularly attractive for Swiss investors.
Focus on ETFs
If you know our blog, you know that we follow a passive, low-cost, broadly diversified buy-and-hold investment strategy. We are convinced that this kind of strategy is best implemented with ETFs. That is why we have deliberately chosen not to analyse and rate individual stocks.
– P a r t n e r o f f e r –
“Green stock” ETFs are still niche ETFs. The largest range for Swiss investors, including the products analysed here, is offered by the Swiss pioneer broker Swissquote (review).
– – – – –
Which type of investor is this article for?
This report is aimed in particular at the following groups of people:
- Committed environmentalists: You already place great value on sustainable products when you shop, and it only makes sense for you to do the same with your investments. We show you a wide range of “green stocks” in the form of sustainable ETFs.
- Green stock pickers: You are already invested in “green stocks”, whether because you want to support the green idea behind them and/or because you expect above-average returns from your investment. You are aware of the risk of total loss that comes with a single-stock strategy, which is why you are open to more broadly diversified, sustainable ETFs – the focus of this report.
- Rational return hunters and trend followers: Green issues are not your main focus, and/or you consider the environmental effect of green investments to be negligible. Still, you are convinced that companies with an environmentally sound business model and/or above-average efforts against climate change are better prepared for the future and will deliver higher returns – be it because their business model has a future, because they pay fewer environmental levies and fines, or simply because they take on smaller reputational risks. Later on, we show you how selected sustainable indices have performed against their reference market over a longer period of ten years or more.
How big is the effect on the environment when I buy “green stocks”?
Before we take a closer look at the Swiss market and compare products and returns, let’s turn to the altruistic side of investing in “green stocks”: what do my sustainable investments actually do for the environment?
Big effects as a consumer
As a consumer, things are clear: if you buy organic product A from green company B, which sources its raw materials from organic farmer C, both the company and the farmer benefit financially from your conscious buying decision in the form of higher sales. At the same time, your money does not go to a conventionally produced agricultural product X from company Y, which sources its raw materials from farmer Z.
We therefore consider the influence you exert as a consumer on the sustainable company (and thus on the environment) to be direct and significant.
When investing in “green stocks”, you need to distinguish between the initial purchase and the trading that follows.
If you are one of the first buyers in an initial public offering (IPO), the purchase price you pay goes straight into the equity of the newly listed company. The company can use “your” money to invest in production facilities, for example, allowing it to pursue its strategic growth and expansion goals.
For investments made in connection with the IPO of a green company, we also consider the effect to be direct and significant.
But what about after the IPO, i.e. in regular stock market trading? In this case, the “green stock” merely changes hands. The money flows from the buyer of the share to the seller. In other words, the company itself does not benefit financially from your investment directly.
And yet: even after the IPO, there are advantages for the sustainable company that should not be underestimated. As demand for “green stocks” rises, so does the market value of these companies. And this brings the following five positive effects, which can be seen clearly in the case of electric car pioneer Tesla, for example:
- Easier fundraising: The green company can carry out a capital increase with a relatively small number of new shares. In other words, a rising share price makes it easier for companies to raise capital through a capital increase.
- Cheaper loans: The company gets more attractive terms on the credit market, because a high share price points to a thriving company with solid key figures and positive business development.
- Better image: A company’s reputation usually grows as its share price rises. It is a sign that the underlying business model is successful. A good image is important not only for expanding the customer base, but also for recruiting the best talent on the job market.
- Protection against hostile takeovers: The higher the share price, the deeper an interested buyer has to dig into their pockets. Thanks to strong demand for Tesla shares, for example, the electric car pioneer has made it into the top 10 of the world’s largest companies by market capitalisation. So the takeover candidate is no longer Tesla, but rather traditional carmakers such as Daimler & Co.
- Stability thanks to happy shareholders: When owners are rewarded with steadily rising share prices, shareholders tend to be more conciliatory at the annual general meeting and are less likely to challenge management or its proposals. This effect should not be underestimated, because unrest and disputes always damage a company’s reputation and disrupt its operations. Take Tesla as an example: anyone who invested in the company a few years ago has been rewarded with incredible price gains. A Tesla investor will therefore usually put up with the regular escapades of Elon Musk, a CEO as brilliant as he is “difficult”, without complaining.
Conclusion
When you buy “green stocks” or sustainable ETFs on the stock exchange, you increase demand, which in turn makes the share price rise, stabilise or fall less sharply. However, the purchase price does not go to the green company, but to the shareholder who is selling (exception: IPO).
In the short term, we therefore see no effect at all for the company or the environment. In the medium to long term, however, rising share prices give the green company advantages that should not be underestimated in raising capital and debt financing, in terms of reputation, protection against hostile takeovers, and the relationship between management and shareholders.
What categories of “green stocks” are there?
Shedding light on the ESG jungle
While researching this article, we realised just how complex and opaque the labels associated with “green stocks” are. It would probably take a doctoral thesis to get a truly in-depth understanding. We’ll spare you (and ourselves) such a dry, detailed analysis and focus instead on the general direction of the individual labels.
Above everything stands the ESG triad “Environment, Social, Governance”. Whether a share is included in a sustainable index therefore depends mainly on how well it meets these three ESG criteria. Below, we show some examples of the specific practices this can involve:
“E” for Environmental
- investments in renewable energy
- efficient use of energy and raw materials
- environmentally friendly production
- low emissions into air and water
“S” for Social
- compliance with core labour rights
- high standards of occupational safety and health protection
- fair working conditions, appropriate pay, and training and development opportunities
- freedom of assembly and freedom to form trade unions
- enforcement of sustainability standards at suppliers
“G” for Governance
- transparent measures to prevent corruption and bribery
- anchoring sustainability management at executive board and supervisory board level
- linking executive board pay to the achievement of sustainability targets
- how whistleblowing is handled
However, the individual companies are not only rated against these criteria using a points system – there are also exclusion criteria.
For example, manufacturers of civilian firearms, controversial weapons, nuclear weapons, oil sands, thermal coal and tobacco are consistently screened out from the outset, even if they were the most socially minded employer with the best corporate governance.
Within the “ESG” label, there are different levels and variants. As a rule of thumb: the higher the exclusion rate, the stricter the underlying selection process.
So if, for example, a sustainable index contains 400 companies and the conventional reference index 1,000, the exclusion rate is 60%. This means that 60% of the companies do not meet the ESG criteria of this sustainable index and are screened out.
Green thematic funds
Naturally, green thematic funds have the highest exclusion rate and the lowest diversification, because they usually focus on a single sector such as “renewable energy”.
Cross-sector funds
For sustainable, cross-thematic ETFs and their underlying indices, the best-in-class approach takes centre stage. This means that within each sector, only those companies are selected that meet the ESG criteria on which the index is based.
Depending on the index, these criteria vary in strictness. Below, we take a closer look at the most important ESG categories of the leading index provider MSCI. (Note: important in the sense that there are ETFs you can buy that track them.)
“SRI”
The abbreviation “SRI” (Socially Responsible Investment) indicates a particularly strict selection. This is shown by the fact that the corresponding indices (e.g. MSCI World SRI) screen out around 75% of the companies that belong to the parent index (e.g. MSCI World).
“SRI” indices are always subject to strict selection, but their content can differ in nuances. There are also SRI indices with a 5% cap, as we will see later.
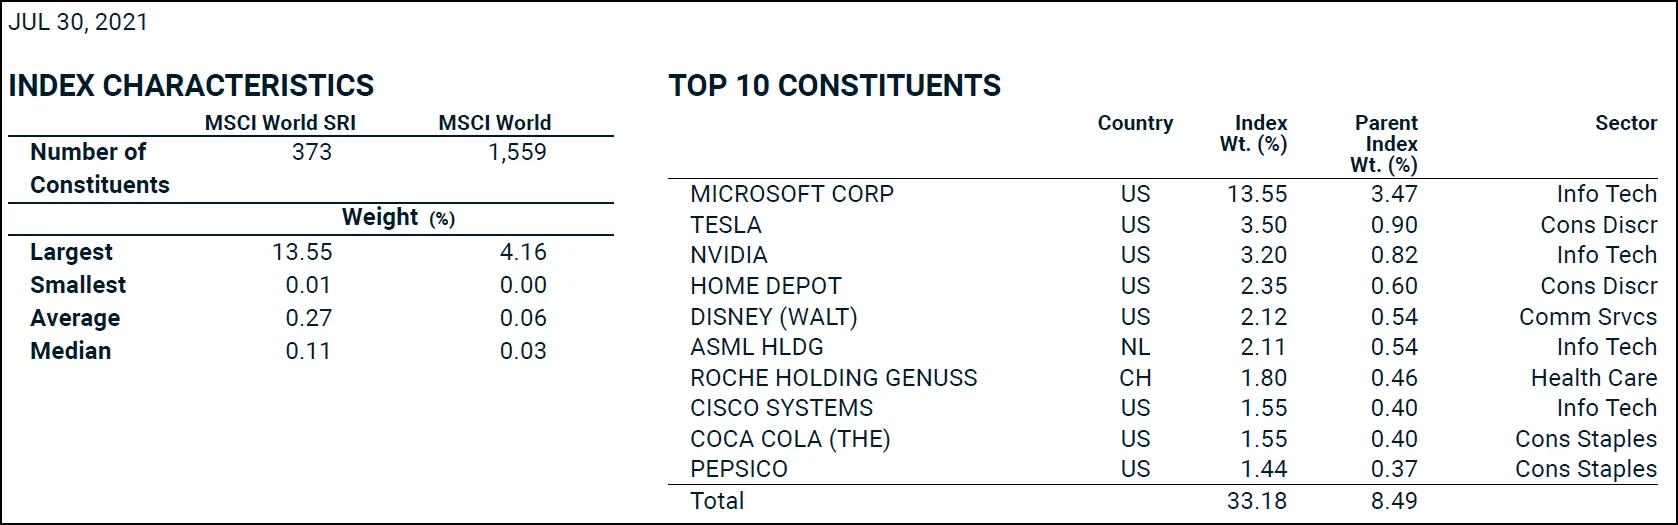
As Figure 1 shows, 373 of 1,559 companies remain in the index, which corresponds to an exclusion rate of 76%. A certain diversification problem becomes apparent when you look at the 10 largest positions: just ten “green stocks” make up a third of the index’s market capitalisation, with Microsoft by far the biggest weighting at over 13 percent. (Its competitor Apple, which is even slightly larger by market capitalisation, apparently does not meet the underlying ESG criteria, which is why it is not included in this index.)
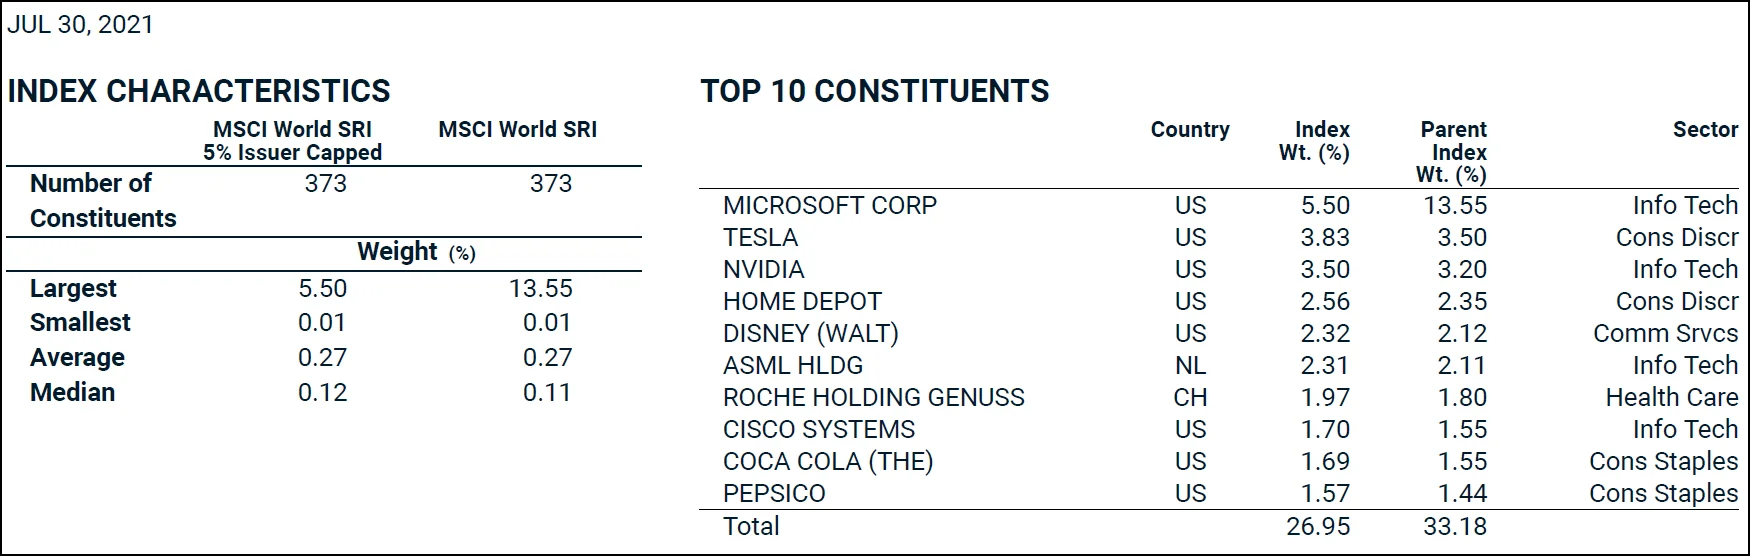
If you want to reduce the concentration risk of individual stocks such as Microsoft, choose an SRI index with a 5% cap. This means the number and selection of companies stay the same, but no company may have a weighting of more than 5%. In this index, Microsoft’s share drops significantly to around 5% (see Figure 2).
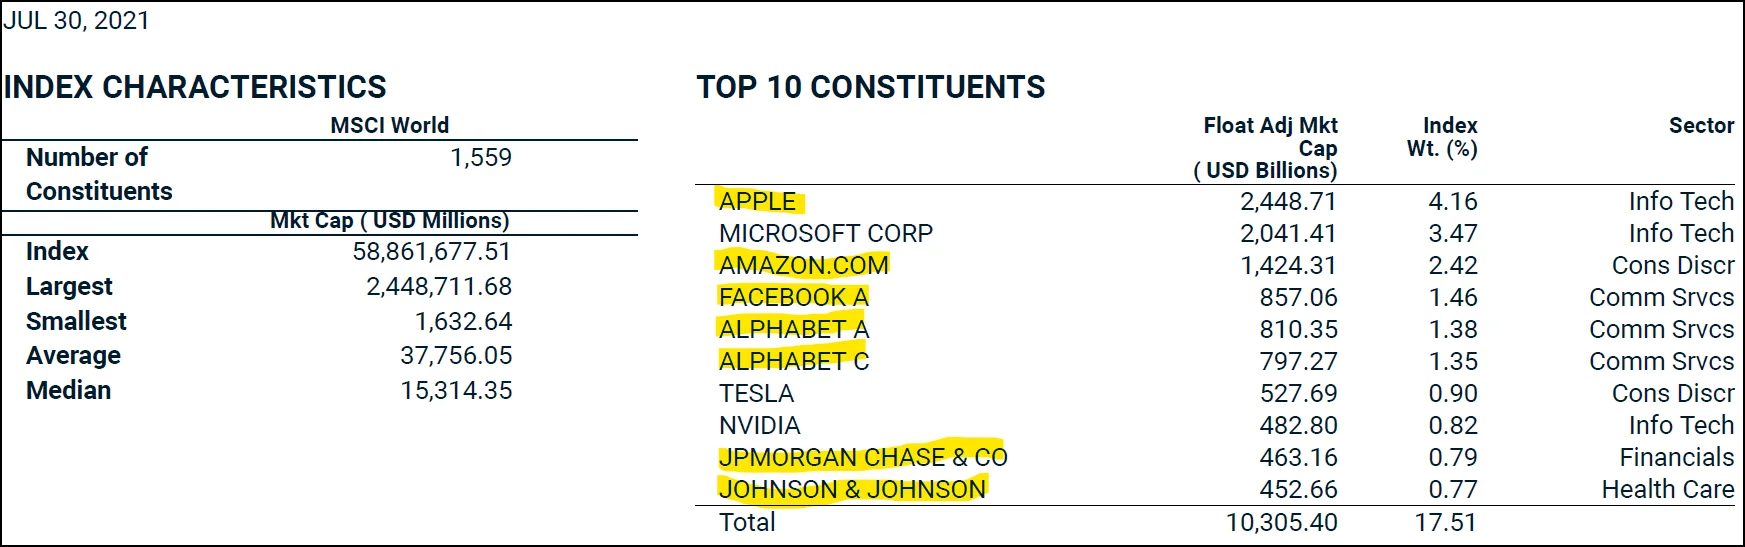
With Figure 3, we want to show once more how strict the SRI selection is by highlighting all companies that are listed in the top 10 of the parent index but not in the “SRI” sub-index. No fewer than seven out of ten companies drop out of the race – or rather, out of the SRI index.
If this selection is too strict for you, or the resulting diversification too low, you can still invest in “green stocks”. In that case, simply choose one of the following ESG options.
“ESG Leaders”
With a target of 50%, the selection for these indices is somewhat less strict.
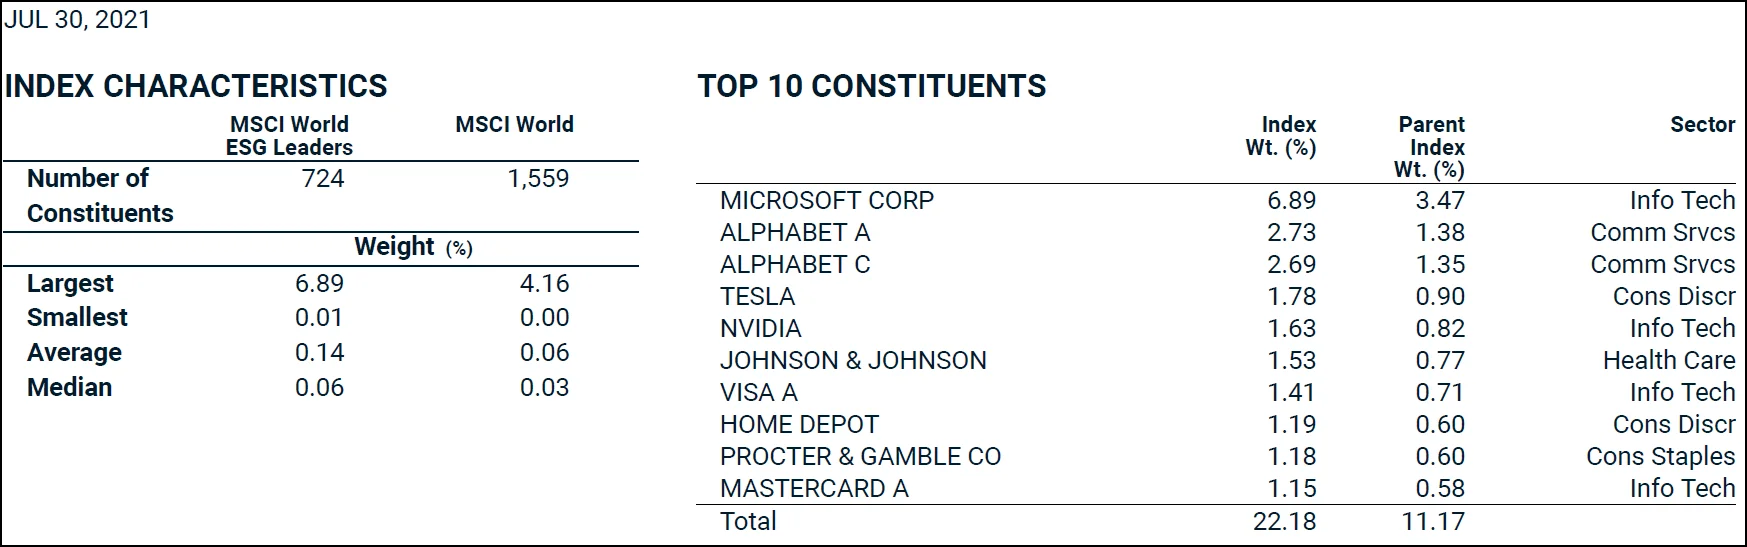
If you compare it with the top 10 of the parent index (see Figure 4), you will notice that the heavyweights Apple, Amazon and Facebook are also missing from “ESG Leaders”.
“ESG Enhanced Focus” and “ESG Screened”
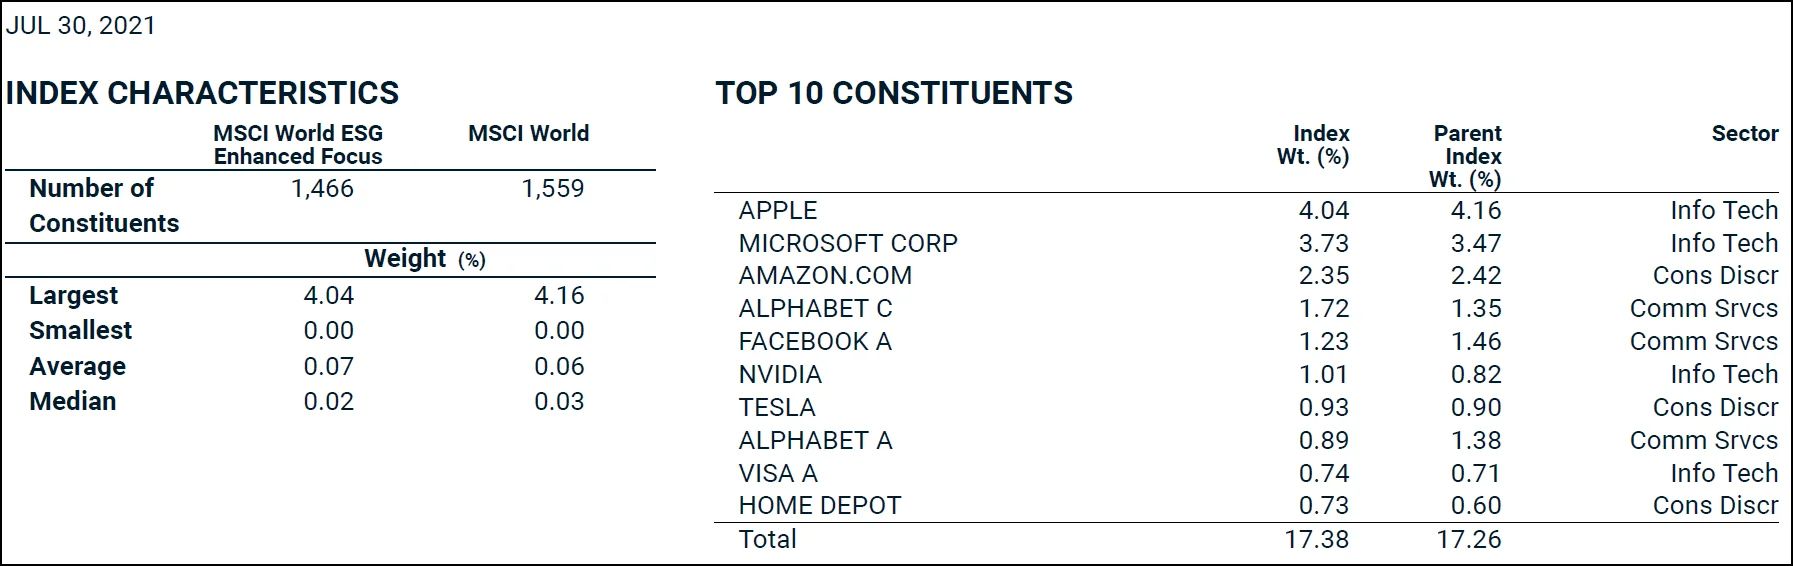
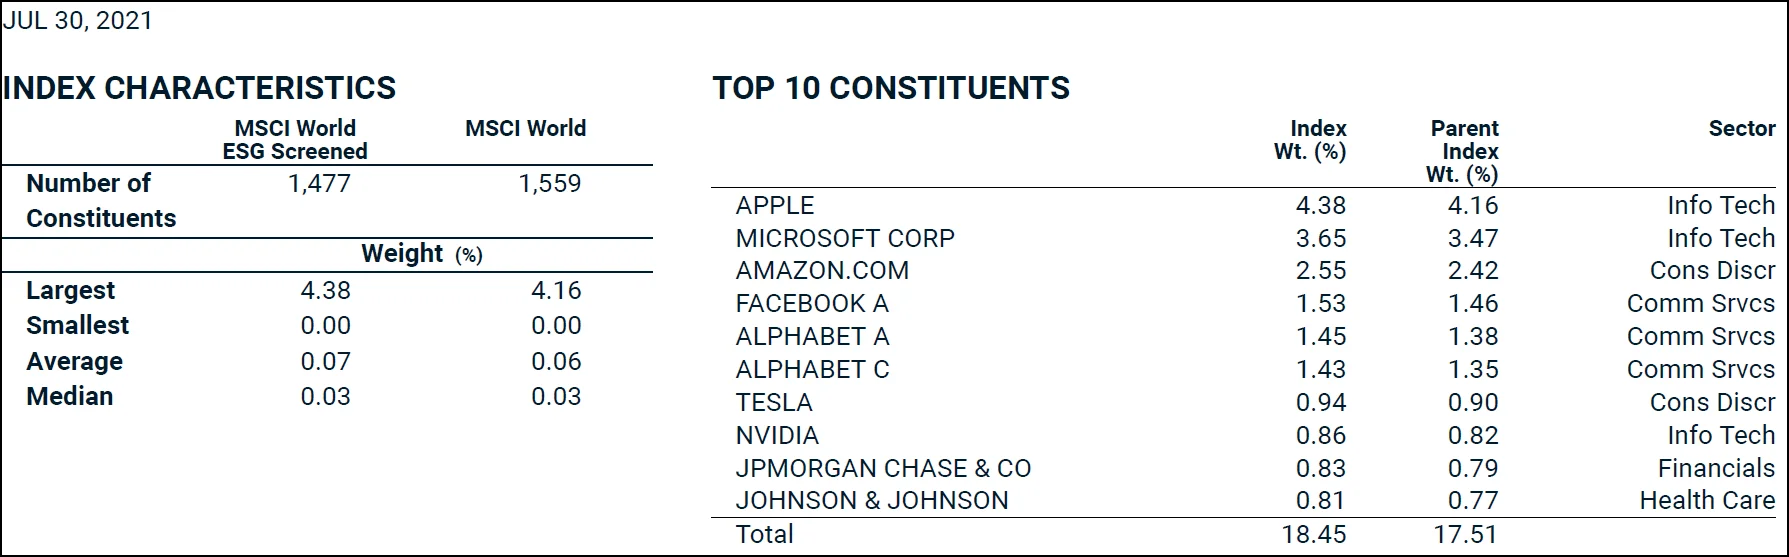
As Figures 5 and 6 show, the exclusion rate for both the “ESG Enhanced Focus” and the “ESG Screened” approach is moderate at 6.0% and 5.3% respectively, so diversification remains very high.
In addition to the exclusion criterion (93 companies have dropped out of the index), the “ESG Enhanced Focus” approach applies an extra weighting for companies with high ESG ratings. Apparently, this is why graphics processor and chipset developer NVIDIA overtakes Tesla, the larger company by market capitalisation, and is weighted more heavily. Apple is also interesting: it is included in these two ESG indices for the first time. In the stricter “Enhanced Focus Index”, however, the world’s largest company is penalised with an underweighting.
Market overview and performance of ETFs with “green stocks”
According to the justETF portal, exactly 1,000 ETFs were tradable on the Swiss stock exchange SIX as of 16 August 2021, 176 of which are listed under the “Social/Sustainable” category.
From these, we filtered out the most established ETFs on the market (fund volume over CHF 500 million) and grouped them by the regions “Global”, “Developed World”, “Emerging Markets”, “Europe”, “North America” and “Asia-Pacific”. Within each group, the ETFs are sorted in descending order of exclusion rate. In other words, the “greenest” ETF is always listed at the top (see Figure 7).
| # | Region | ESG focus / exclusion rate | Fund name / ISIN / Reference index | No. of index const. | Fund curr. | Fund size in CHF million | Costs TER p.a. |
|---|---|---|---|---|---|---|---|
| 1.01 | Global | very strong / > 97% | Lyxor New Energy (DR) UCITS ETF / FR0010524777 / World Alternative Energy Total Return Index | 40 | EUR | 1276 | 0.60% |
| 1.02 | Global | very strong / > 97% | iShares Global Clean Energy UCITS ETF / IE00B1XNHC34 / S&P Global Clean Energy Index | 81 | USD | 5412 | 0.65% |
| 1.03 | Global | strong / 82% | UBS ETF (IE) MSCI ACWI Soc Res UCITS ETF / IE00BDR55F85 / MSCI ACWI SRI Low Carbon Select 5% Issuer Capped Index | 524 | CHF | 646 | 0.33% |
| 1.04 | Global | moderate / 13% | Vanguard ESG Global All Cap UCITS ETF / IE00BNG8L278 / FTSE Global All Cap Choice Index | 7957 | CHF | 70 | 0.24% |
| 1.05 | Global | moderate / 13% | Vanguard ESG Global All Cap UCITS ETF / IE00BNG8L385 / FTSE Global All Cap Choice Index | 7957 | CHF | 61 | 0.24% |
| 1.06 | Global | moderate / 4% | UBS ETF (IE) MSCI ACWI ESG Universal UCITS ETF / IE00BDQZN774 / MSCI ACWI ESG Universal Index | 2859 | CHF | 883 | 0.33% |
| 1.07 | Global | none | SPDR MSCI ACWI UCITS ETF / IE00B44Z5B48 / MSCI ACWI | 2965 | USD | 2666 | 0.40% |
| 1.08 | Global | none | UBS ETF (IE) MSCI ACWI SF UCITS ETF / IE00BYM11L64 / MSCI ACWI | 2965 | CHF | 1408 | 0.21% |
| 2.01 | Developed world | strong / 76% | iShares MSCI World SRI UCITS ETF / IE00BDZZTM54 / MSCI World SRI Index | 373 | USD | 914 | 0.20% |
| 2.02 | Developed world | strong / 76% | UBS ETF (LU) MSCI World Soc Res UCITS ETF / LU0950674332 / MSCI World SRI Low Carbon Select 5% Issuer Capped Index | 373 | USD | 756 | 0.22% |
| 2.03 | Developed world | strong / 76% | UBS ETF (LU) MSCI World Soc Res UCITS ETF / LU0629459743 / MSCI World SRI Low Carbon Select 5% Issuer Capped Index | 373 | USD | 3354 | 0.22% |
| 2.04 | Developed world | strong / 76% | iShares MSCI World SRI UCITS ETF / IE00BYX2JD69 / MSCI World SRI Select Reduced Fossil Fuels Index | 381 | EUR | 3326 | 0.20% |
| 2.05 | Developed world | medium / 63% | Xtrackers MSCI World ESG UCITS ETF 1C / IE00BZ02LR44 / MSCI World Low Carbon SRI Leaders Index | 577 | USD | 2376 | 0.20% |
| 2.06 | Developed world | medium / 54% | CSIF (IE) MSCI World ESG Leaders Blue UCITS ETF B / IE00BJBYDQ02 / MSCI World ESG Leaders Index | 724 | USD | 850 | 0.15% |
| 2.07 | Developed world | moderate / 6% | iShares MSCI World ESG Enhanced UCITS ETF / IE00BHZPJ569 / MSCI World ESG Enhanced Focus Index | 1466 | USD | 1253 | 0.20% |
| 2.08 | Developed world | moderate / 5% | iShares MSCI World ESG Screened UCITS ETF / IE00BFNM3J75 / MSCI World ESG Screened Index | 1477 | USD | 1256 | 0.20% |
| 2.09 | Developed world | none | iShares Core MSCI World UCITS ETF / IE00B4L5Y983 / MSCI World Index | 1559 | USD | 36386 | 0.20% |
| 3.01 | Emerging countries | strong / 88% | UBS ETF (LU) MSCI EM Soc Res UCITS ETF / LU1048313891 / MSCI Emerging Markets SRI Low Carbon Select 5% Issuer Capped Index | 170 | USD | 1031 | 0.27% |
| 3.02 | Emerging countries | strong / 87% | iShares MSCI EM SRI UCITS ETF / IE00BYVJRP78 / MSCI Emerging Markets SRI Select Reduced Fossil Fuels Index | 179 | USD | 2195 | 0.25% |
| 3.03 | Emerging countries | strong / 74% | Xtrackers MSCI Emerging Markets ESG UCITS ETF 1C / IE00BG370F43 / MSCI Emerging Markets Low Carbon SRI Leaders Index | 364 | USD | 1335 | 0.25% |
| 3.04 | Emerging countries | moderate / 9% | iShares MSCI EM ESG Enhanced UCITS ETF / IE00BHZPJ239 / MSCI Emerging Markets ESG Enhanced Focus Index | 1277 | USD | 953 | 0.18% |
| 3.05 | Emerging countries | moderate / 4% | iShares MSCI EM IMI ESG Screened UCITS ETF / IE00BFNM3P36 / MSCI Emerging Markets IMI ESG Screened Index | 3111 | USD | 1361 | 0.18% |
| 3.06 | Emerging countries | none | Xtrackers MSCI Emerging Markets UCITS ETF 1C / IE00BTJRMP35 / MSCI Emerging Markets Index | 1406 | USD | 5734 | 0.18% |
| 3.07 | Emerging countries | none | iShares Core MSCI Emerging Markets IMI UCITS ETF / IE00BKM4GZ66 / MSCI Emerging Markets IMI Index | 3227 | USD | 17501 | 0.18% |
| 4.01 | Europe | strong / 77% | UBS ETF (LU) MSCI EMU Soc Res UCITS ETF / LU0950674761 / MSCI EMU SRI Low Carbon Select 5% Issuer Capped Index | 53 | EUR | 1220 | 0.22% |
| 4.02 | Europe | strong / 77% | UBS ETF (LU) MSCI EMU Soc Res UCITS ETF / LU0629460675 / MSCI EMU SRI Low Carbon Select 5% Issuer Capped Index | 53 | EUR | 1288 | 0.22% |
| 4.03 | Europe | strong / 73% | iShares MSCI Europe SRI UCITS ETF / IE00B52VJ196 / MSCI Europe SRI Select Reduced Fossil Fuels Index | 117 | EUR | 3659 | 0.20% |
| 4.04 | Europe | strong / 73% | iShares MSCI Europe SRI UCITS ETF / IE00BGDPWW94 / MSCI Europe SRI Select Reduced Fossil Fuels Index | 117 | EUR | 713 | 0.20% |
| 4.05 | Europe | medium / 53% | Lyxor MSCI Europe ESG Leaders (DR) UCITS ETF / LU1940199711 / MSCI Europe ESG Leaders Index | 201 | EUR | 900 | 0.20% |
| 4.06 | Europe | medium / 40% | Lyxor Net Zero 2050 S&P Eurozone … (DR) UCITS ETF / LU2195226068 / S&P Eurozone LargeMidCap Paris-Aligned Climate Index | 148 | EUR | 830 | 0.20% |
| 4.07 | Europe | moderate / 10% | iShares MSCI EMU ESG Screened UCITS ETF / IE00BFNM3B99 / MSCI EMU ESG Screened Index | 228 | EUR | 1758 | 0.12% |
| 4.08 | Europe | moderate / 5% | iShares MSCI Europe ESG Enhanced UCITS ETF / IE00BHZPJ783 / MSCI Europe ESG Enhanced Focus Index | 411 | EUR | 547 | 0.12% |
| 4.09 | Europe | moderate / 4% | iShares MSCI Europe ESG Screened UCITS ETF / IE00BFNM3D14 / MSCI Europe ESG Screened Index | 414 | EUR | 949 | 0.12% |
| 4.10 | Europe | none | UBS ETF (LU) MSCI EMU UCITS ETF / LU0950668870 / MSCI EMU Index | 236 | EUR | 1822 | 0.18% |
| 4.11 | Europe | none | iShares Core MSCI Europe UCITS ETF / IE00B1YZSC51 / MSCI Europe Index | 432 | EUR | 7017 | 0.12% |
| 5.01 | North America | strong / 80% | UBS ETF (LU) MSCI USA Soc Res UCITS ETF / LU0629460089 / MSCI USA SRI Low Carbon Select 5% Issuer Capped Index | 124 | USD | 1696 | 0.22% |
| 5.02 | North America | strong / 79% | iShares MSCI USA SRI UCITS ETF / IE00BYVJRR92 / MSCI USA SRI Select Reduced Fossil Fuels Index | 133 | USD | 6584 | 0.20% |
| 5.03 | North America | medium / 65% | Xtrackers MSCI USA ESG UCITS ETF 1C / IE00BFMNPS42 / MSCI USA Low Carbon SRI Leaders Index | 218 | USD | 2816 | 0.15% |
| 5.04 | North America | medium / 56% | CSIF (IE) MSCI USA ESG Leaders Blue UCITS ETF B / IE00BJBYDP94 / MSCI USA ESG Leaders Index | 276 | USD | 1694 | 0.10% |
| 5.05 | North America | medium / 50% | UBS ETF (IE) S&P 500 ESG UCITS ETF / IE00BHXMHL11 / S&P 500 ESG Index | 314 | USD | 617 | 0.12% |
| 5.06 | North America | moderate / 9% | Invesco MSCI USA ESG Univ. Screened UCITS / IE00BJQRDM08 / MSCI USA ESG Universal Select Business Screens Index | 568 | USD | 861 | 0.09% |
| 5.07 | North America | moderate / 7% | iShares MSCI USA ESG Enhanced UCITS ETF / IE00BHZPJ908 / MSCI USA ESG Enhanced Focus Index | 582 | USD | 2727 | 0.07% |
| 5.08 | North America | moderate / 6% | iShares MSCI USA ESG Screened UCITS ETF / IE00BFNM3G45 / MSCI USA ESG Screened Index | 588 | USD | 3466 | 0.07% |
| 5.09 | North America | none | iShares Core S&P 500 UCITS ETF / IE00B5BMR087 / S&P 500 Index | 500 | USD | 44205 | 0.07% |
| 5.10 | North America | none | Xtrackers MSCI USA UCITS ETF 1C / IE00BJ0KDR00 / MSCI USA Index | 625 | USD | 5706 | 0.07% |
| 6.01 | Asia- Pacific | strong / 76% | iShares MSCI Japan SRI UCITS ETF / IE00BYX8XC17 / MSCI Japan SRI Select Reduced Fossil Fuels Index | 65 | USD | 639 | 0.20% |
| 6.02 | Asia- Pacific | strong / 76% | UBS ETF (LU) MSCI Pacific Soc Res UCITS ETF / LU0629460832 / MSCI Pacific SRI Low Carbon Select 5% Issuer Capped Index | 94 | USD | 952 | 0.40% |
| 6.03 | Asia- Pacific | medium / 60% | Xtrackers MSCI Japan ESG UCITS ETF 1C / IE00BG36TC12 / MSCI Japan Low Carbon SRI Leaders Index | 110 | USD | 1878 | 0.20% |
| 6.04 | Asia- Pacific | moderate / 3% | iShares MSCI Japan ESG Screened UCITS ETF / IE00BFNM3L97 / MSCI Japan ESG Screened Index | 265 | USD | 743 | 0.15% |
| 6.05 | Asia- Pacific | none | Xtrackers MSCI Japan UCITS ETF 1C / LU0274209740 / MSCI Japan Index | 272 | USD | 2372 | 0.20% |
| 6.06 | Asia- Pacific | none | iShares Core MSCI Pacific ex Japan UCITS ETF / IE00B52MJY50 / MSCI Pacific ex Japan Index | 127 | USD | 2946 | 0.20% |
You can find a more detailed version with additional performance data in the following Excel file: 40_green_stock_ETFs_2021_compared (in German)
For the following three reasons, we have also included Vanguard with two ETFs, even though these products have only been around since March of this year and their fund volume is still modest:
- Vanguard is the pioneer par excellence when it comes to passive, index-based investments that are also extremely cheap. There are plenty of “Bogleheads” in Switzerland too, for whom Vanguard is always the first choice.
- Our research showed that the range of established ETFs in the “Global” cluster, i.e. “Developed World” and “Emerging Markets” combined, is still rather thin. The two Vanguard products fill this gap perfectly.
- The fact that Vanguard has finally woken up from its deep sleep when it comes to “green stocks” deserves to be duly rewarded.
In total, we have therefore analysed 40 sustainable ETFs in Figure 7. This overview also includes eleven selected conventional ETFs (i.e. without an ESG focus) for comparison.
All the sustainable ETFs listed in Figure 7 comply with the European UCITS Directive. This means these ETFs are subject to minimum regulatory requirements, such as independent supervision or rules on the mandatory information provided to investors.
The 40 sustainable ETFs are spread across seven providers, with market leader iShares (18 ETFs) and Switzerland’s own UBS (10) taking the lion’s share. They are followed at a greater distance by Xtrackers (4), Lyxor (3), Credit Suisse (2), Vanguard (2) and Invesco (1).
In the following chapters, we look at one region after another, discuss the particular features of individual ETFs, suggest possible combinations and compare their performance (after costs/TER) with conventional ETFs.
Speaking of combinations and conventional ETFs: if you don’t want to compromise on diversification but still want to add a green touch, your best option is to combine the sustainable ETF with the conventional one. This way, you are invested in the overall market with a higher weighting of “green stocks”. We won’t mention this option again for each region in the detailed analysis below.
“Green stocks” – Global
If you want to cover the whole world with one sustainable ETF, you have – based on our selection criteria – six products to choose from (see Figure 8).
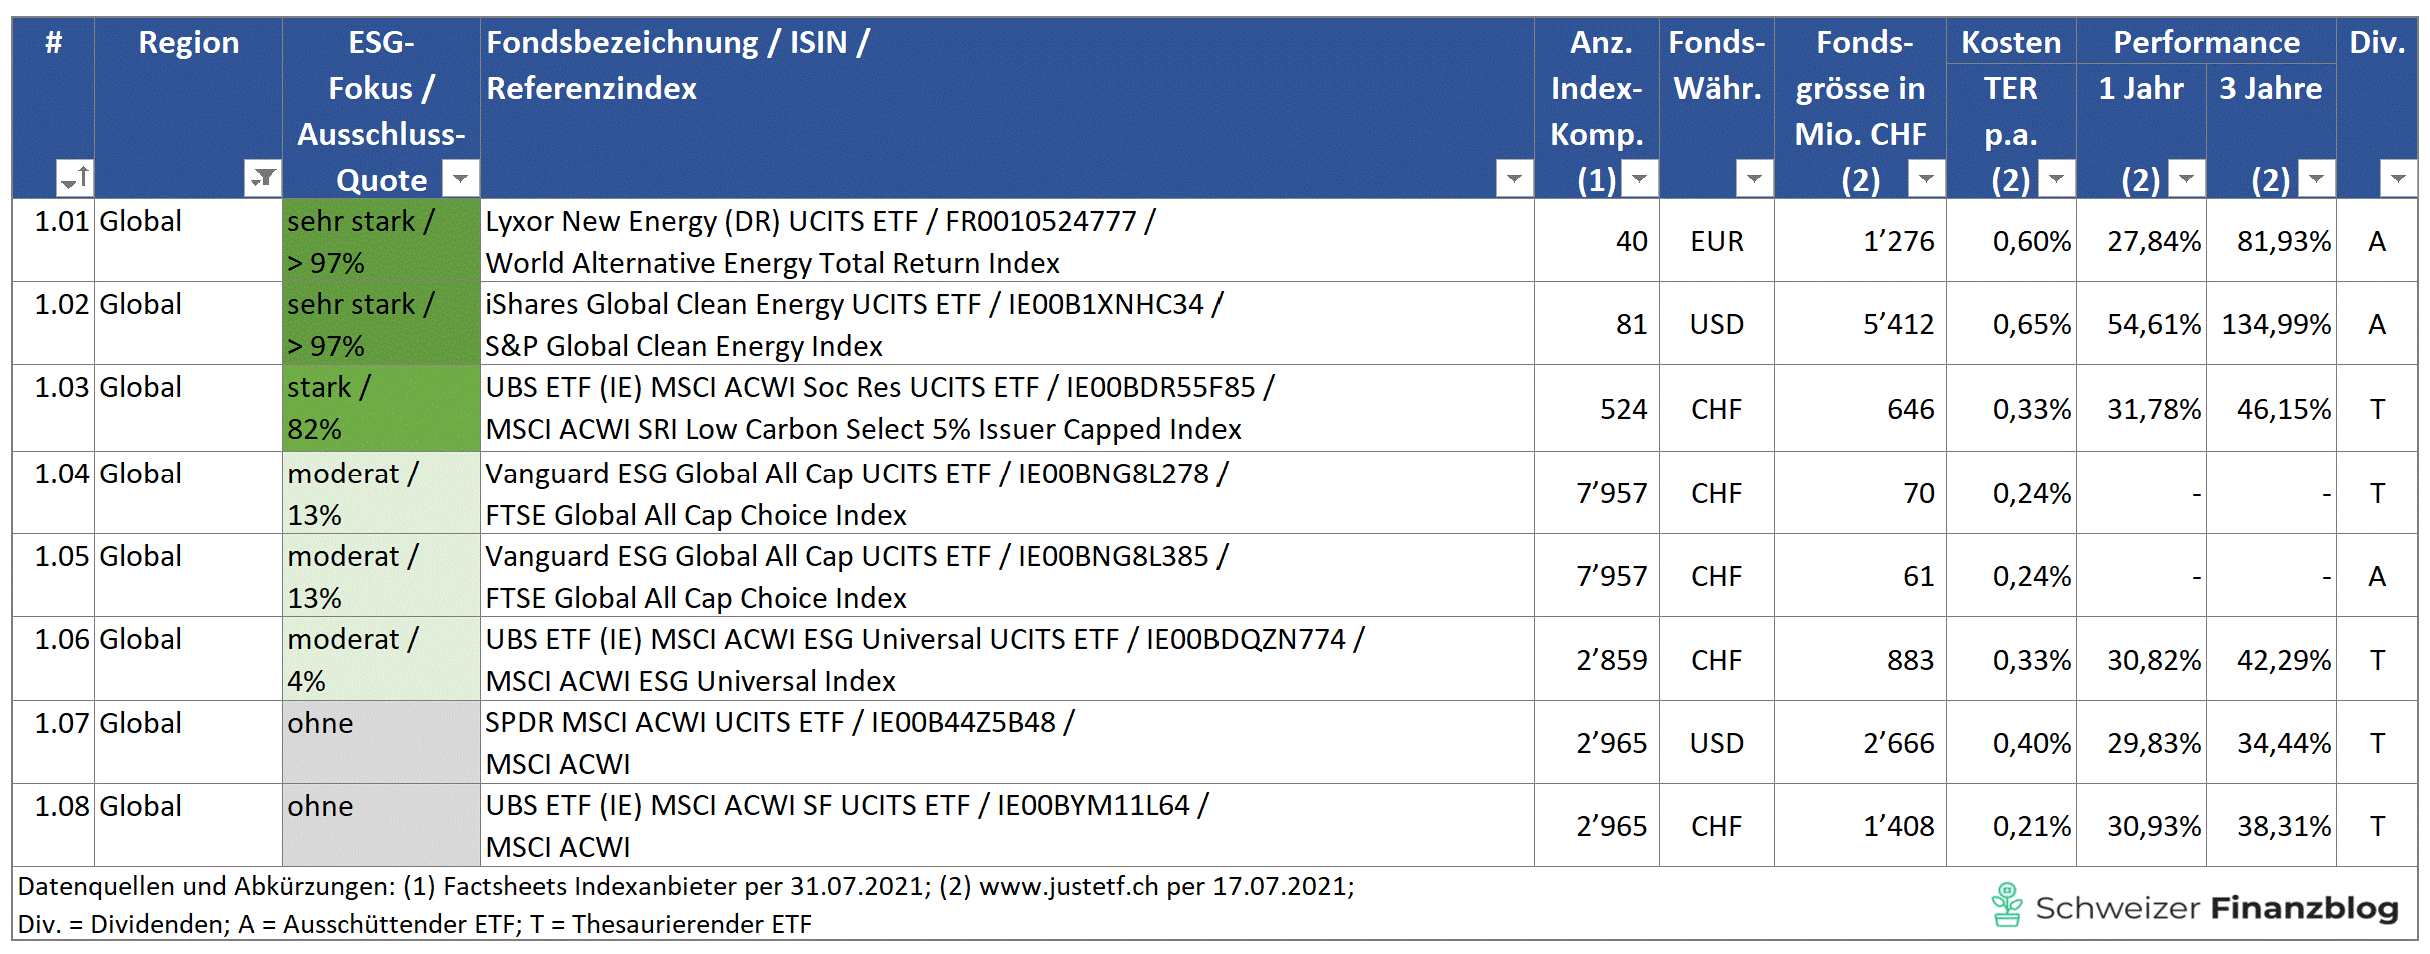
The first two ETFs are weakly diversified funds focused on “renewable energy”. With a TER of 0.60% and 0.65% respectively, they are also the most expensive products in our comparison.
We don’t like the reference index of the Lyxor product. It looks as though the product and the index come from the same company, which undermines the usual separation of powers between index provider and ETF provider.
The iShares ETF “Global Clean Energy” stands out for its huge fund size of over CHF 5 billion (and the same again for the US market). In recent years, the fund has attracted so much money that some of the originally only 30 “green stocks” saw enormous price increases.
At the beginning of this year, index provider S&P was finally forced to pull the emergency brake: the previously strict inclusion criteria were relaxed, allowing additional companies to be added to the index from 19 April 2021 (currently 81; medium-term target 100).
This ETF has had a very turbulent history anyway. In contrast to the last three years, when it performed sensationally, it stood out in the first phase after its launch in 2007 for a disastrous price performance (see Figure 9). It lost over 80% of its value within a few months, and to this day it has not recovered from this crash.
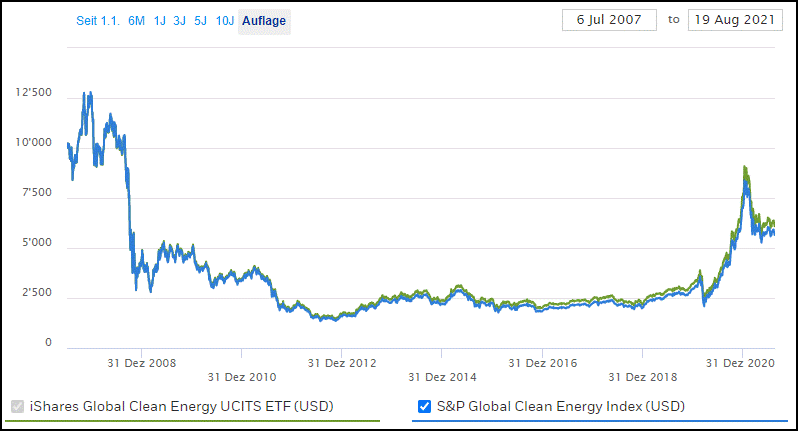
So anyone who invested back then because they wanted to be an ecological pioneer and/or (rightly) saw renewable energy as a megatrend paid a high price for the lesson. Because megatrend or not, between 2008 and 2012 there was a Nokia effect that swept through an entire industry.
Chinese companies pushed into the market, while established European top dogs such as Solarworld slid deep into the red and eventually went bust one after another. The immense drop in prices was therefore the result of a rigorous market shakeout.
This example clearly shows that thematic funds can be exposed to very large fluctuations. We therefore recommend such ETFs only as an add-on (the salt in the soup, so to speak; also known as a core-satellite strategy) to a broadly diversified global portfolio.
The two Vanguard products, for example, which come in a distributing and an accumulating version, are extremely broadly diversified with around 8,000 index constituents (i.e. large, mid and small caps) and therefore combine well with the thematic funds mentioned above. We expect these two young products to grow their fund volume quickly thanks to their attractive value for money.
If you have higher standards for “green stocks”, go for the SRI product from UBS. Unlike thematic funds, it covers all important sectors. Its 524 index constituents correspond to an exclusion rate of over 80 percent. We consider the costs fair. Compared with its two direct (conventional) competitors, this SRI ETF has performed better over the last three years.
“Green stocks” – Developed World
As Figure 10 shows, the classic “MSCI World” is available in various sustainable sub-indices. The costs of all the sustainable ETFs are very moderate and comparable with the conventional ETF.
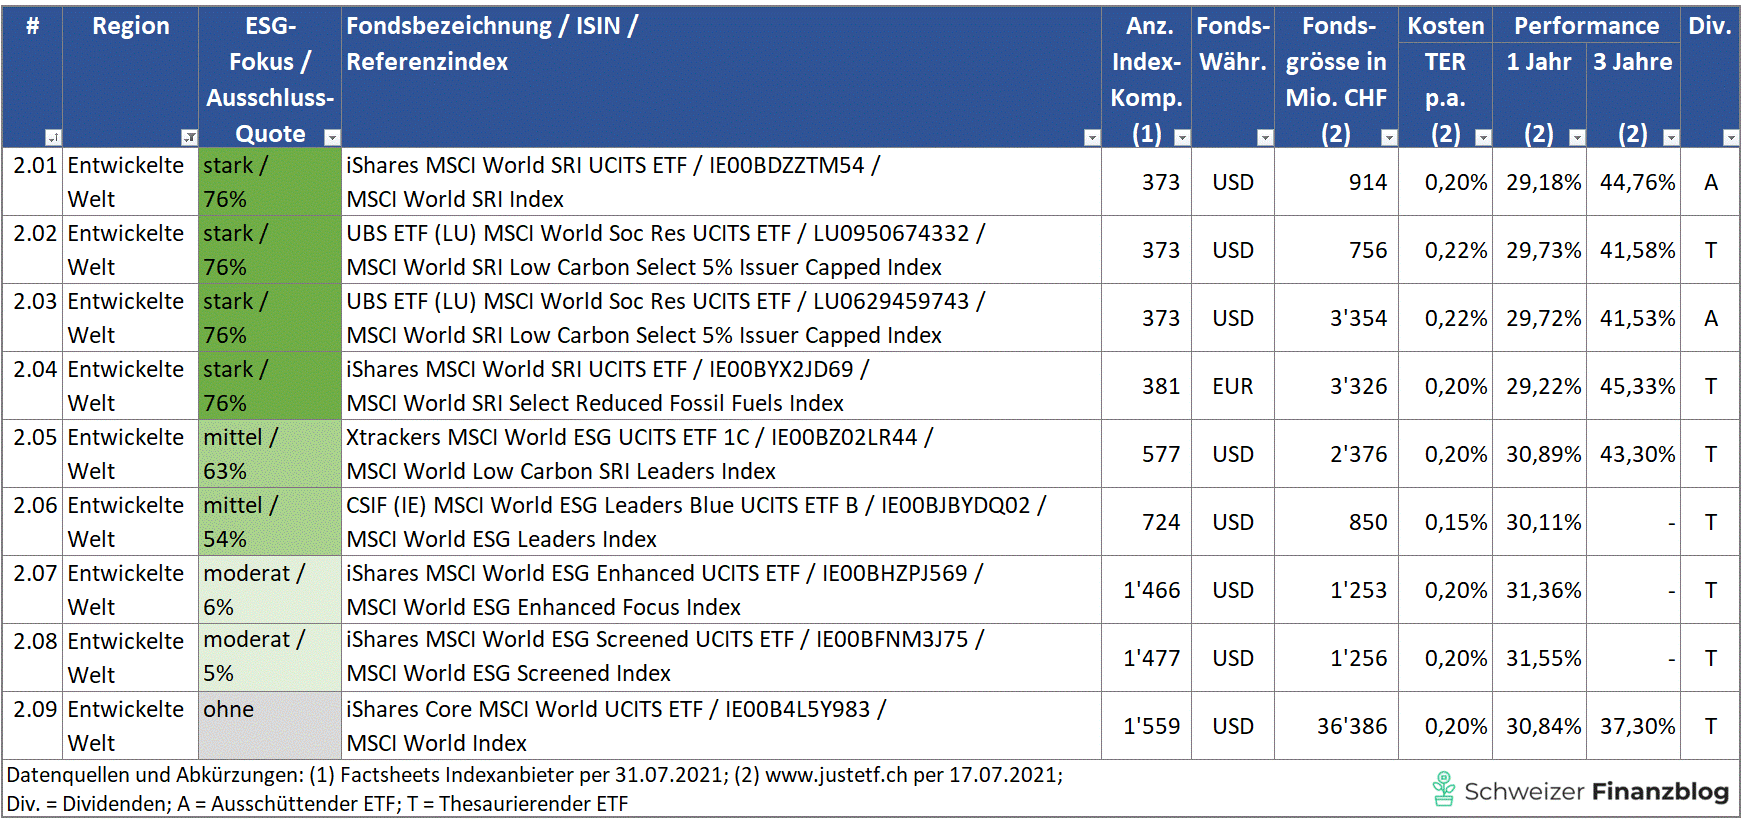
In the 3-year performance comparison, the sustainable ETFs come out ahead.
The good news is that as an investor who wants to add a green touch, you have a wide range of sustainable ETFs to choose from in the “Developed World” region: from the SRI products with strict selection, to the two Leaders ETFs with a medium ESG focus, to the broadly diversified “Enhanced” and “Screened” products.
The underlying index of the first-listed iShares ETF differs from that of the two UBS products that follow only in that it has no 5% cap (see also this chapter, subheading “SRI”).
Even though the index name in Figure 10, item 2.04 doesn’t say so, this index is also based on a 5% cap according to the MSCI factsheet. Currently, this cap is applied in both indices and all three ETFs (see Figure 10, items 2.02 – 2.04) only to the stock market heavyweight Microsoft.
A good match for a sustainable “MSCI World” ETF is an ETF covering the emerging markets (see next chapter).
“Green stocks” – Emerging Markets
As Figure 11 shows, the range of sustainable ETFs for emerging markets is fairly limited. Nevertheless, competition is working well, as prices have fallen sharply in recent years. The first-listed UBS product, for example, cost about twice today’s price (0.53% TER) when it was launched.
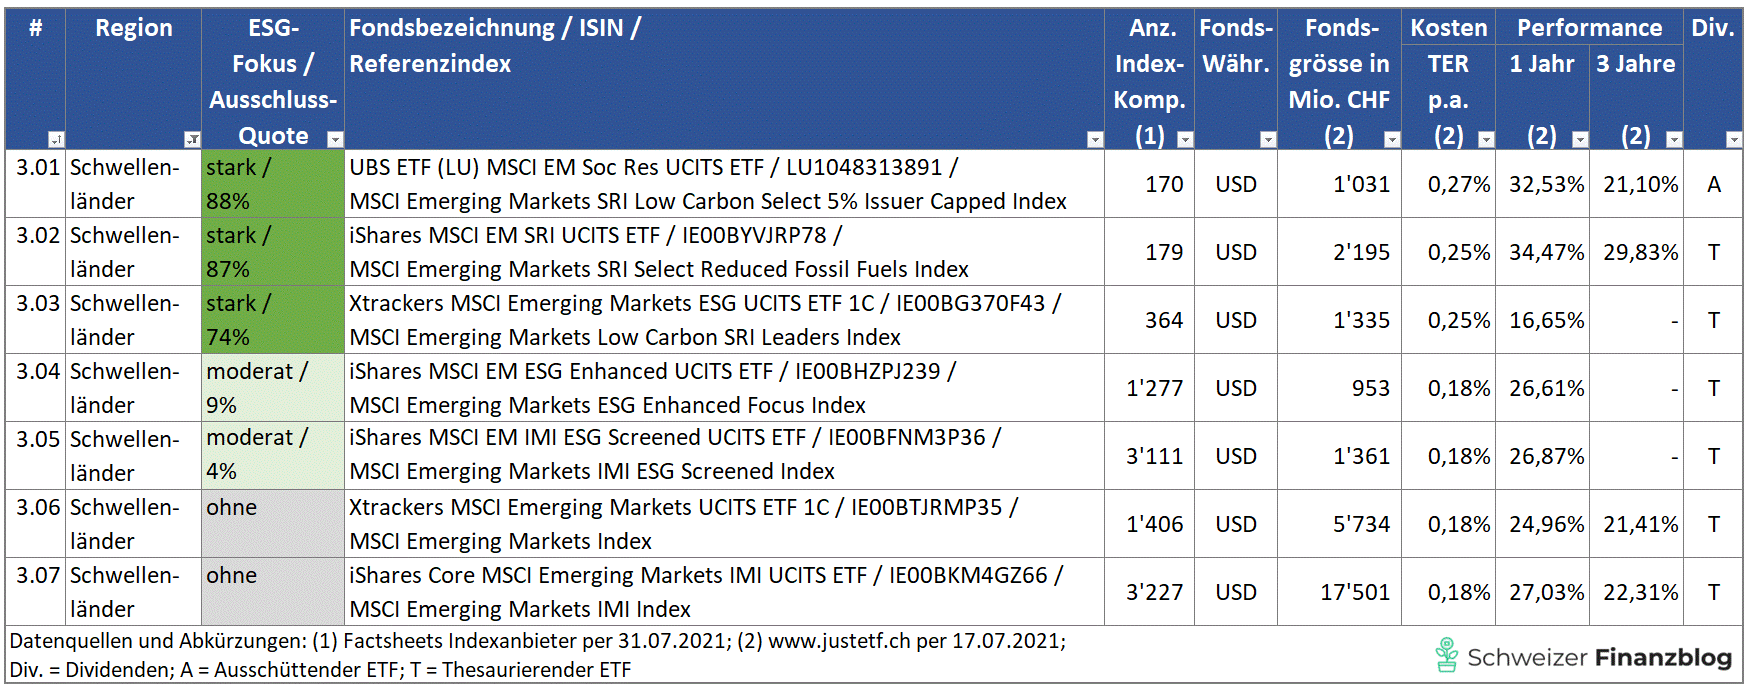
In the 3-year performance comparison, the second-listed iShares product comes out on top and also clearly beats both conventional ETFs.
A good match for a sustainable “Emerging Markets” ETF is either an ETF covering the “Developed World” (see previous chapter) or ETFs with regional coverage (see the next three chapters).
“Green stocks” – Europe
As Figure 12 shows, the “Europe” region has a fairly large range of sustainable ETFs. Note that, besides the varying strength of the individual ETFs’ ESG focus, one group covers all of Europe, while the other only includes eurozone countries (EMU, European Monetary Union) – meaning that countries such as Switzerland, the UK and Norway are missing.
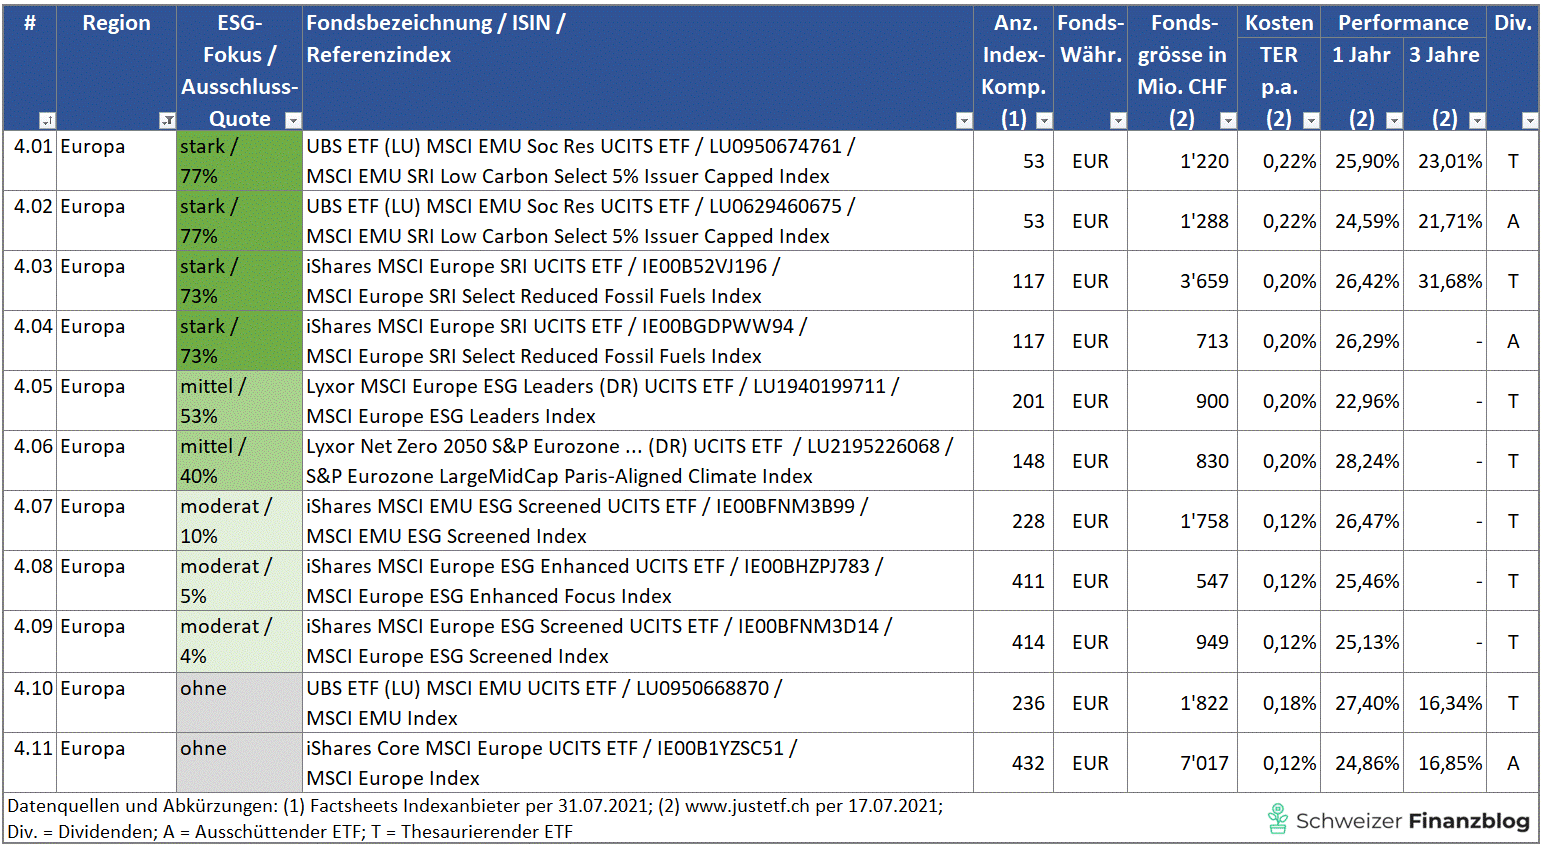
With a TER of around 0.2%, prices are low. In the 3-year performance comparison, the three sustainable ETFs do better than their conventional counterparts.
If you want to set your own regional weighting in your portfolio, pick one of the sustainable Europe ETFs and combine it with the regions “North America” (see this chapter) and “Asia-Pacific” (see this chapter) as well as an emerging markets ETF (see this chapter).
“Green stocks” – North America
As Figure 13 shows, there is also a fairly large range of sustainable ETFs for the “North America” region.
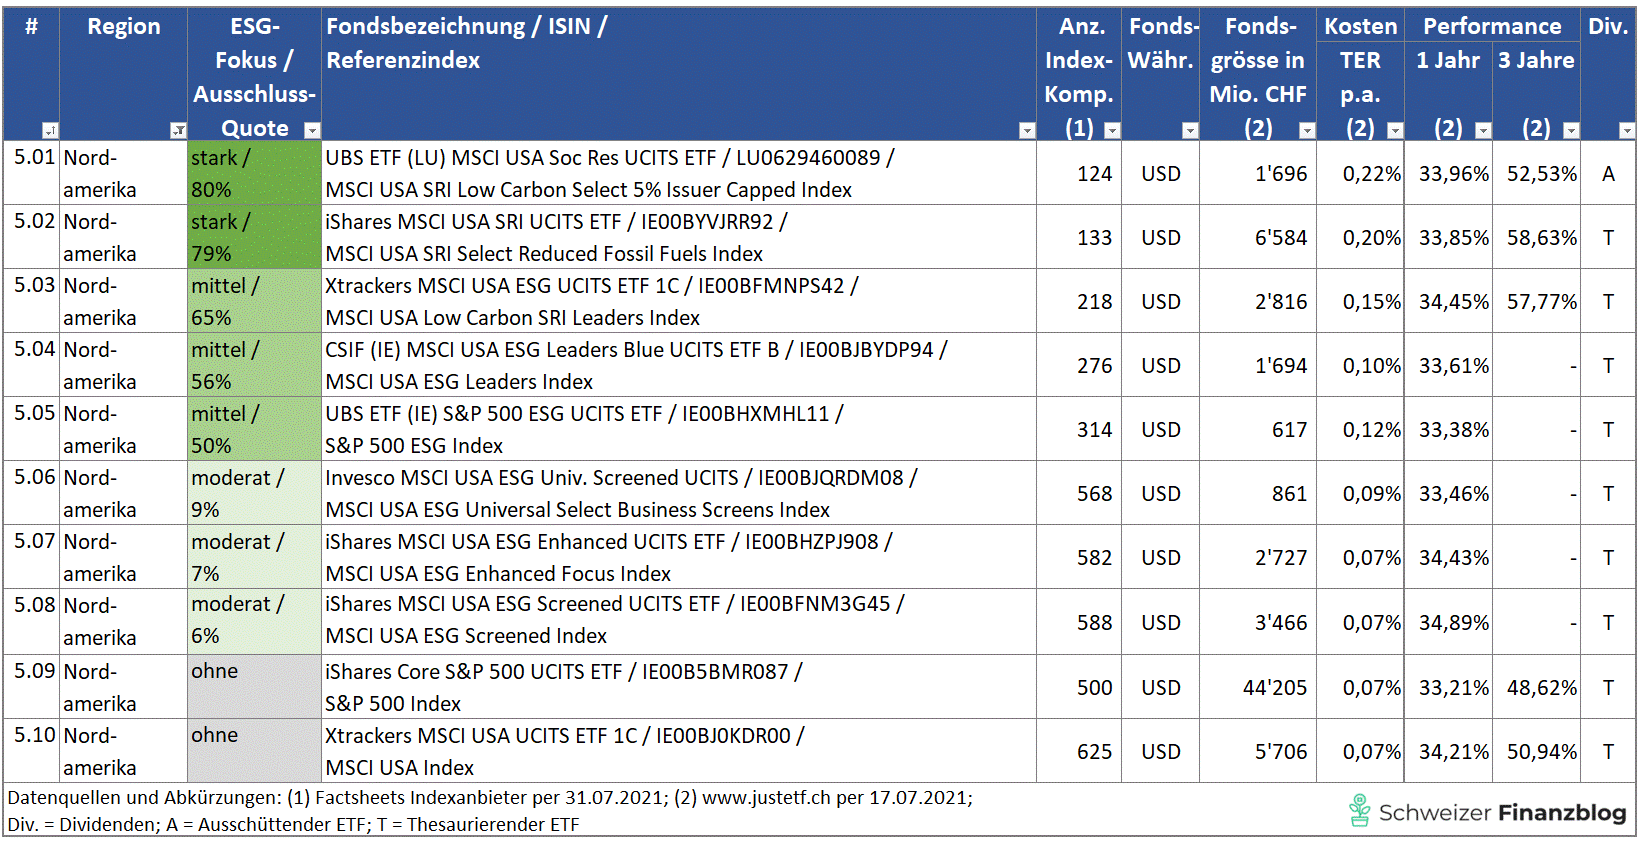
One drawback, however, is that there are no sustainable ETFs that also include Canadian companies. The selection shown therefore only covers US companies.
Apparently, none of the ETF providers has so far seen the need to close this “gap in the market”. It would be great if a sustainable ETF covering the entire North American region were launched in the near future. MSCI created the corresponding ESG indices long ago.
Prices are low to very low across the board (0.07%!). In the 3-year performance comparison, the sustainable ETFs do slightly better than their conventional counterparts.
If you want to set your own regional weighting in your portfolio, pick one of the sustainable US ETFs (unfortunately without Canada) and combine it with the regions Europe (see this chapter) and Asia-Pacific (see this chapter) as well as an emerging markets ETF (see this chapter).
“Green stocks” – Asia-Pacific
As Figure 14 shows, the “Asia-Pacific” region offers only a small range of sustainable ETFs. Note that only the second-listed SRI product from UBS – probably also the most expensive due to the lack of competition – covers the entire region. Otherwise, you need two ETFs to cover the Asia-Pacific region.
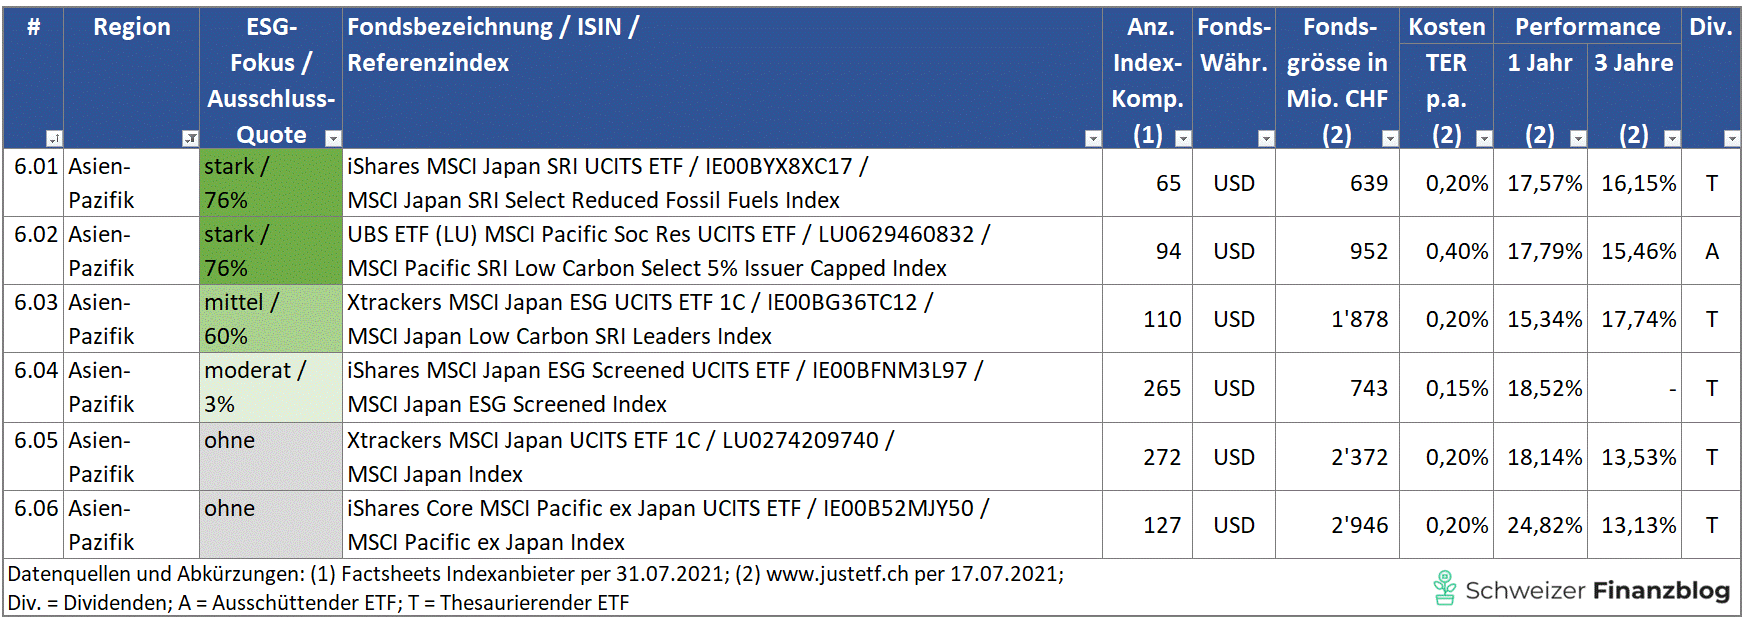
Apart from the UBS outlier mentioned, prices here are also low with a TER of around 0.2%. In the 3-year performance comparison, the sustainable ETFs do slightly better than their conventional counterparts.
If you want to set your own regional weighting in your portfolio, pick one or two of the sustainable Asia-Pacific ETFs and combine them with the regions Europe (see this chapter) and North America (see this chapter) as well as an emerging markets ETF (see this chapter).
How do “green stocks” perform in the long run?
So far, we have found that over the past three years – after costs (TER) – sustainable ETFs have tended to deliver better returns than conventional ETFs tracking the respective overall market (Global, Europe, etc.).
38 of the 40 selected ETFs have fund assets of over CHF 500 million (exception: two Vanguard ETFs). Even so, the vast majority of these sustainable products have only been on the market for a few years.
To still be able to make a long-term performance comparison, in this chapter we no longer rely on real ETFs but on a few selected indices whose performance and risk data have been compared with those of the parent index (without an ESG focus) over a period of at least ten years (see Figure 15).
These are gross returns (total return index), i.e. including dividends and before costs. The data refer to the reference currencies USD or EUR (I08 – I10).
Overview of sustainable indices over 10 years
Figure 15 compares the return and risk of selected sustainable indices over ten years.
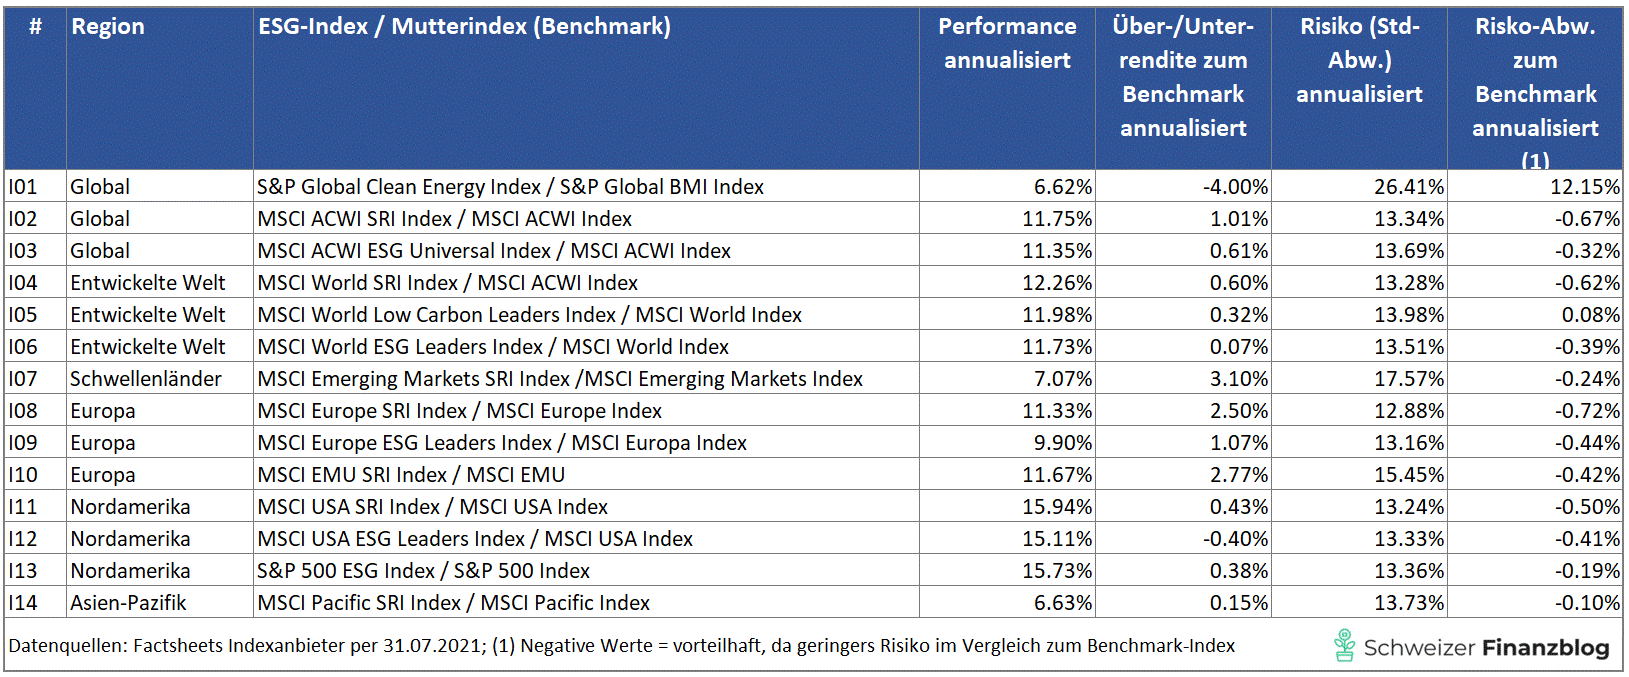
Apart from the first-listed thematic fund, which performed worse with higher risk over the last ten years (for the reasons, see this chapter and the chart in Figure 9), the cross-sector indices paint a positive picture. The sustainable indices achieved comparable or better performance and risk figures than their conventional counterparts.
In the following chapters, we take a closer look at the three SRI indices “MSCI ACWI SRI” (Global), MSCI World SRI (Developed World) and “MSCI Emerging Markets SRI”.
MSCI ACWI SRI vs. MSCI ACWI
Over the last ten years, the MSCI ACWI SRI has performed better than its parent index, the MSCI ACWI (10.74%), with an annualised return of 11.75%. Notably, the outperformance only really took off from 2019 (see Figure 16).
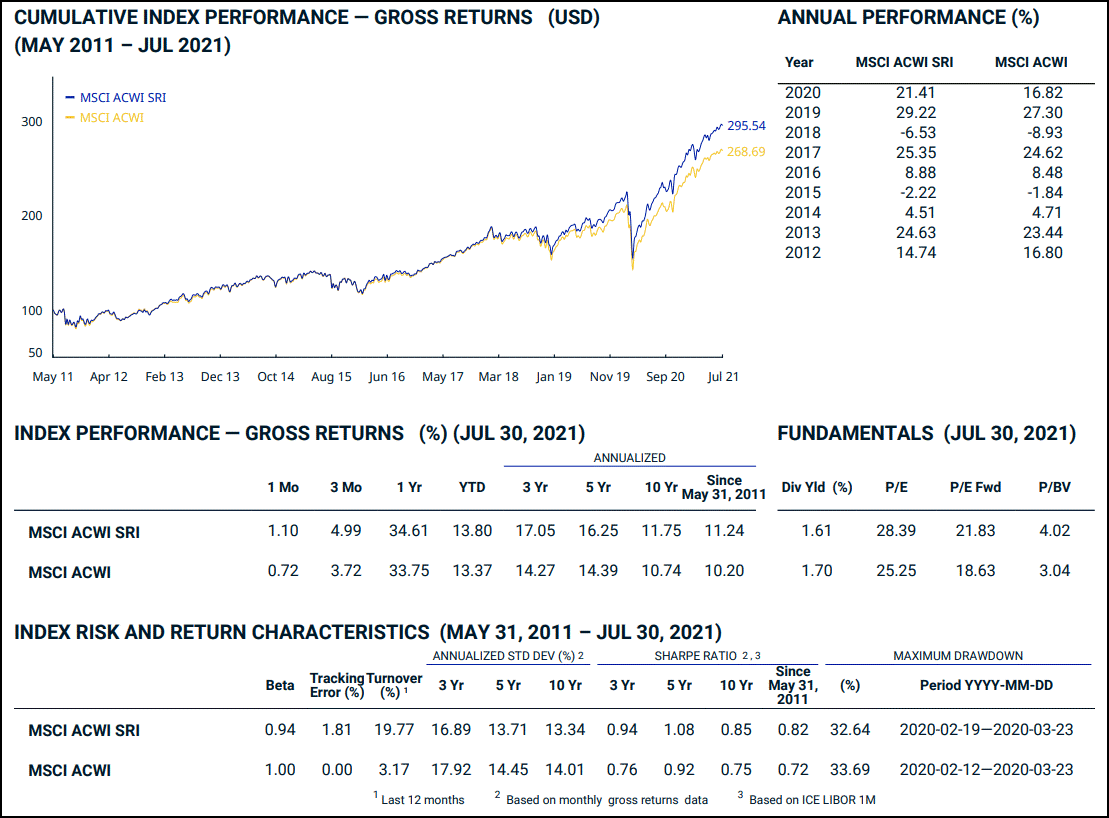
Despite lower diversification, the MSCI ACWI SRI has lower risk, measured by annualised standard deviation (volatility), at 13.34 compared with the MSCI ACWI (14.01).
It comes as little surprise, then, that the Sharpe ratio, which relates the excess return over a “risk-free” investment to the risk taken (volatility), is also better for the MSCI ACWI SRI at 0.85 than for the MSCI ACWI (0.75).
MSCI World SRI vs. MSCI World
For “green stocks” in the developed world, we can even look back over a comparison period of almost 14 years. And here too, the performance and risk figures of the sustainable MSCI World SRI index are better than those of the conventional MSCI World (see Figure 17).
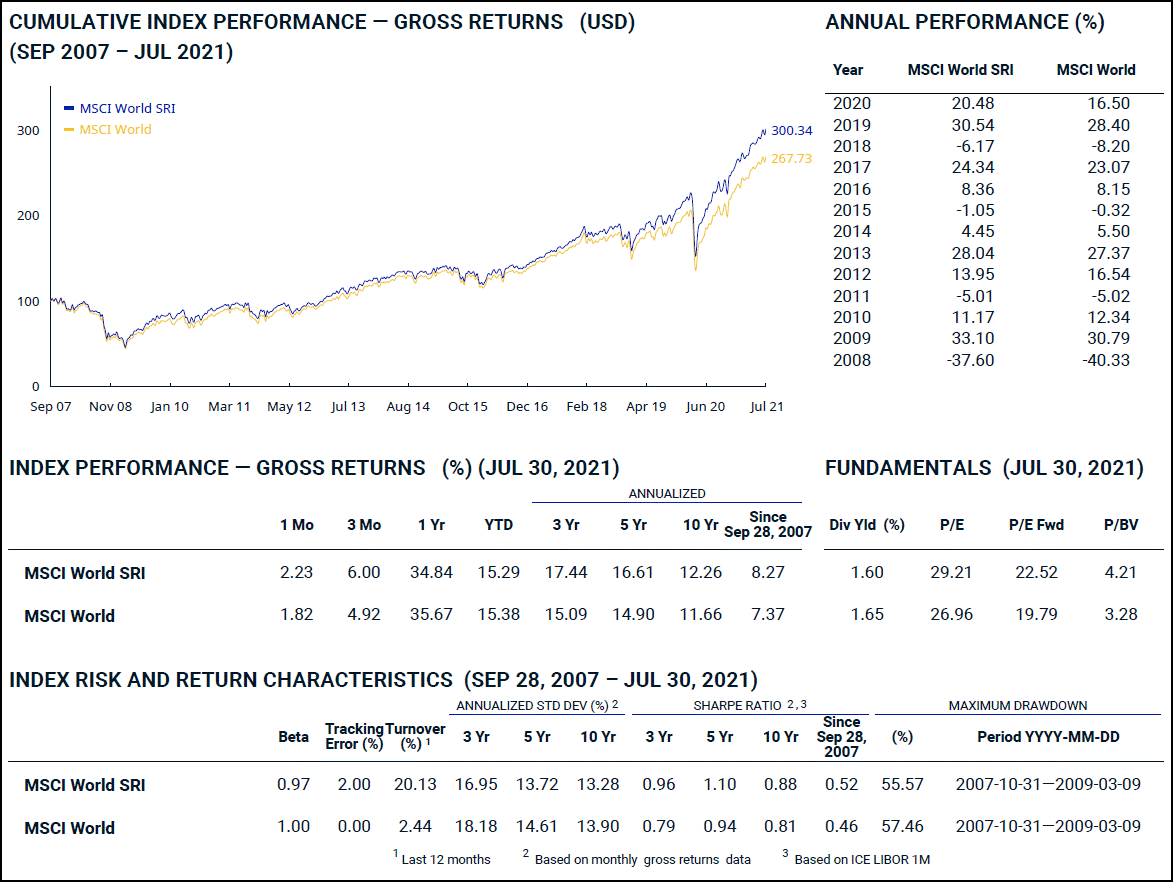
MSCI Emerging Markets SRI vs. MSCI Emerging Markets
In emerging markets, the annualised performance of the MSCI Emerging Markets SRI (7.07%) over the last ten years is significantly better than that of its parent index (3.97%). This outperformance was achieved with comparable risk (volatility) (see Figure 18).
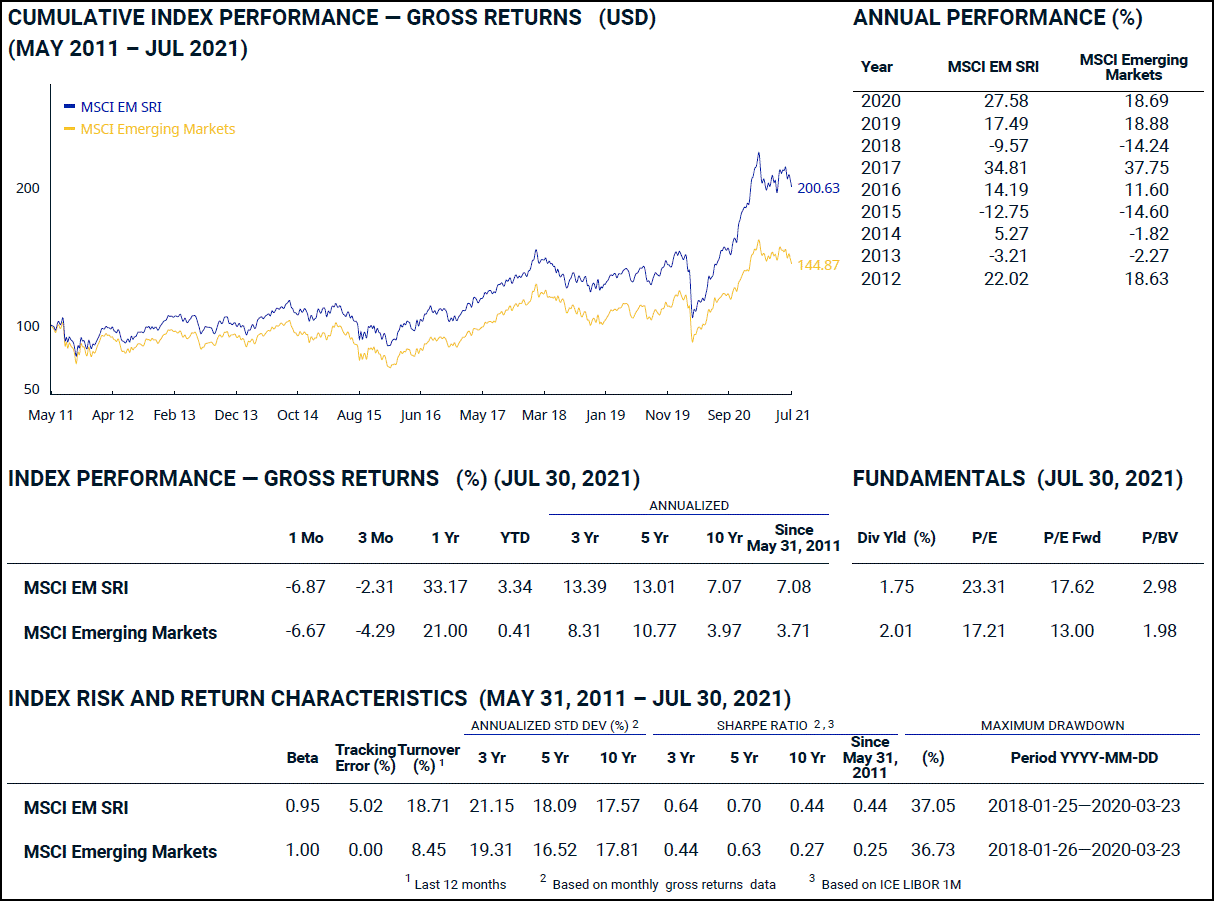
Conclusion
Most of the sustainable indices analysed here have done better in terms of return and risk over the long term than their more broadly diversified parent indices. Bear in mind, though, that these positive figures only reflect the past and are not a reliable forecast of future performance.
In our article “Is factor investing worth it?…” we looked at what sets factor investments apart and which five factors (including small cap and value) have been scientifically confirmed so far.
As we saw so strikingly in the previous chapter, ETFs with “green stocks” have performed better than the corresponding reference market without an ESG focus.
From a scientific point of view, sustainable investing is not (yet) a new factor. That would only be the case if the outperformance persisted over several decades.
Unlike the scientifically confirmed factors, it is also difficult to pin down a clear filter criterion given the current, rather opaque selection of “green stocks”. With the “small cap” factor, for example, it’s child’s play: you simply filter companies by their market capitalisation.
Final conclusion
We sum up the key findings in the following six points:
- Indirect effect on the environment: When you invest in “green stocks”, whether through sustainable ETFs or individual stocks, your money does not go to the companies concerned (exception: IPO). In the short term, you therefore have no effect at all, neither on the company nor on the environment. In the medium to long term, however, rising share prices give the sustainable company advantages that should not be underestimated in raising capital and debt financing, in terms of reputation, protection against hostile takeovers, and the relationship between management and shareholders.
- Label jungle: Much like the food sector, the sustainable investment market is rather complex and opaque. Complex, because the overarching “ESG” label comes in various forms such as “SRI”, “ESG Leaders”, “Enhanced Focus” or “Screened”, each with selection processes of completely different strictness. Opaque, because the underlying points system is not transparent. Why, for example, is Microsoft included in the MSCI World SRI, but not Apple? In the end, it probably simply comes down to trust – just like with the Bio Suisse Bud organic label.
- Wide choice of products: You can already buy over 170 sustainable ETFs on the Swiss stock exchange SIX. 38 of the 40 ETFs analysed in this report have fund assets of over CHF 500 million. Such products have established themselves successfully on the market, so the risk of an ETF being closed is very small. You can easily build a sustainable global portfolio with the ETFs analysed, whether with one (Global), two (Developed World and Emerging Markets) or four to five ETFs (Europe, North America, Asia-Pacific and Emerging Markets). With the latter option, however, Canada would not be covered. A green “renewable energy” thematic fund could also be added as a satellite.
- Fair prices: Thanks to healthy competition, the prices of sustainable ETFs have fallen sharply in recent years. A TER of around 0.20% is completely normal today. We therefore no longer consider the price argument against sustainable investments to be valid. The cheapest product we analysed even comes at a rock-bottom price of 0.07%. At the other end of the scale are the two thematic ETFs with a TER of 0.60% and 0.65% respectively.
- Good performance and acceptable risk: Anyone who has invested in sustainable, cross-sector ETFs so far has achieved a better return in the short to medium term than with the conventional counterpart, without taking on more risk in the form of higher volatility. Over the longer term, i.e. in the 10-year comparison of selected indices, the picture is equally positive. Emerging markets in particular delivered a clear outperformance over the last ten years. Thematic ETFs, however, are much more volatile because of their sector focus and comparatively small number of companies, and are therefore only recommended as an add-on to a cross-sector global portfolio (see also the point “Wide choice of products” above).
- No factor investing: Despite their outperformance, investments in “green stocks” are not (yet) factors from a scientific point of view. One requirement for this would be a proven outperformance over a period of several decades. The green investment market is still too young for that.
We hope this in-depth report has given you a useful basis for deciding whether to invest in “green stocks”. What do you think? We look forward to your comment!
You might also be interested in
Disclaimer
Disclaimer: Investing involves the risk of loss. You have to decide for yourself whether or not you want to bear these risks.
Errors excepted: We have written this article to the best of our knowledge and belief. Our goal is to give you, as a private investor, information on finance that is as objective and meaningful as possible. If we have nevertheless made mistakes, forgotten important aspects and/or if information is no longer up to date, we would be grateful if you let us know.
Transparency note: At the time of publication, the Schweizer Finanzblog team is invested in the following investments mentioned in the article:
iShares Global Clean Energy UCITS ETF / UBS ETF (LU) MSCI Emerging Markets Socially Responsible UCITS ETF (USD) A-dis / UBS ETF (LU) MSCI EMU Socially Responsible UCITS ETF (EUR) A-dis / UBS ETF (LU) MSCI Pacific Socially Responsible UCITS ETF (USD) A-dis / UBS ETF (LU) MSCI World Socially Responsible UCITS ETF (USD) A-dis / Tesla Inc. (TSLA)
Apart from these investments, there are no business relationships (commissions or similar) with any of the index or ETF providers mentioned in this report.
About the authors

Stefan Huser
Stefan has been investing in the stock market himself since 2015. He has been shaped by Markowitz’s portfolio theory and Gerd Kommer’s book “Souverän investieren”. He follows a core-satellite strategy: a global equity portfolio of ETFs forms the core, complemented by alternative investments. At the blog, he mainly takes care of the writing. Stefan lives with his family in Zurich and is interested in literature, photography and financial freedom.

Antun Brcina
Antun (“Toni”) has been investing in the stock market since 2015. Financially, he has been particularly inspired by Gerd Kommer’s book “Souverän investieren” and the Fama-French five-factor model. His money is invested in a broadly diversified, long-term global equity portfolio of ETFs. At the blog, he mainly works on the calculators and the code. Toni lives with his family in the Zurich area and is interested in sports, technology and entrepreneurship.









7 Comments
Vielen Dank für den informativen und interessanten Artikel.
Leider scheint die ISIN von dem folgendem von Ihnen genannten globalen ETF falsch zu sein:
UBS ETF (IE) MSCI ACWI Soc Res UCITS ETF / IE00B1XNHC34 /
MSCI ACWI SRI Low Carbon Select 5% Issuer Capped Index
Könnten Sie die ISIN für diesen ETF korrigieren und bestätigen?
Merci für den Hinweis. Die korrekte ISIN lautet gemäss UBS Produkt-Factsheet IE00BDR55F85. Wir haben die ISIN im Beitrag korrigiert.
Hi
Mit dem aktuellen Krieg vor unseren Toren hat sich die Performance SRI/ESG deutlich zu Gunsten ungrüner Werte wie zur Waffen- und fossilen Energie-industrie verschoben. Wäre toll die Performance-Werte aktualisiert bis und mit 2023 zu publizieren.
Den durchaus auch fraglichen “Greenwashing-Prozess” mal ganz aussen vor gelassen – Die Zahlen präsentieren sich anders. 😉
Grüsse
Hallo,
Was hält Ihr in der jetztigen Situation vom Kauf von ETFs oder Aktien im Bereich Wasserstoff?
Danke
Peter
Hoi Peter
Nicht viel. Wir bevorzugen breiter diversifizierte ETFs, weil sie in der Regel ein besseres Risiko-/Renditeverhältnis aufweisen.
Beste Grüsse
SFB
Liebes Schweizer Finanzblog Team
Vielen Dank für den ausführlichen Bericht zum Thema grüne Aktien
Hoi zäme
Wow, was für ein informativer Bericht. Herzlichen Dank dafür!
LG Eli