
 Newsletter
How much of your money belongs in equities – and how much stays in your bank account? The answer is the most important decision you’ll make when investing. Not picking the right ETF, not the perfect moment to get in – but how you structure your assets. In this fourth lesson of our financial guide, you’ll learn how to determine your personal asset allocation step by step and what role your risk profile, your liquidity reserve and the third pillar play in it.
< Lesson 3 | Overview | Lesson 5 >

In a nutshell
- Asset allocation – splitting your assets into a high-risk and a low-risk portion – is the most important decision you make when investing.
- Before you invest, you need a liquidity reserve of three to six months’ expenses. It sits outside your asset allocation.
- Your risk profile – made up of risk tolerance and risk capacity – determines the weighting. Whichever of the two factors is more cautious sets the limits.
- In the high-risk portion, broadly diversified equity ETFs form the core. The simplest solution: a single global ETF. If you like, you can add to it using the core-satellite principle.
- The low-risk portion – bank deposits and possibly high-quality bonds – brings hardly any return, but provides stability, flexibility and rebalancing ammunition.
- Write down your target allocation. It’s your guiding star – and in the next market crash it’s worth more than any hot investment tip.
Contents
What is asset allocation?
Behind the term asset allocation lies a simple idea: structuring your assets. In concrete terms, it’s about how you spread your money across different asset classes – how much goes into equities, how much stays in your bank account and how much, if any, you put into real estate or other investments.
If diversification is the blueprint, then asset allocation – in other words, the structure of your assets – is the foundation of your house. It determines how solidly the building stands, not the colour of the walls or the model of the kitchen. Numerous studies confirm exactly this: it isn’t the choice of individual products but the way you split your assets that has the greatest impact on long-term investment success. Your asset allocation is what you align every other investment decision with.
Before we get into the details, it’s worth looking at the big picture. Your assets can be divided into three areas, each with a different job: the liquidity reserve as a safety net, the low-risk portion as an anchor of stability and the high-risk portion as the engine of returns.
The liquidity reserve: your safety net
Every sound financial plan includes a liquidity reserve – an emergency fund of three to six months’ expenses in your bank account. This reserve is there to cushion unforeseen expenses such as job loss, illness or major repairs without you having to touch your investments.
Even though the liquidity reserve also sits in your bank account at low risk, it is not part of your asset allocation. The difference: the low-risk portion of your investments is a deliberate strategic decision within your portfolio. The liquidity reserve, by contrast, is a prerequisite that has to be in place before you even think about investing. It’s reserved for emergencies – and therefore off-limits for investment purposes. Paying off any consumer loans also takes priority – their interest exceeds any realistic investment return.
Only what’s left after your emergency fund and paying off debt is your freely available investment capital. And it’s exactly this capital that you now structure through asset allocation.
Your risk profile determines the split
How you split your freely available assets depends on your individual risk profile – that is, on the interplay between your risk tolerance and your risk capacity, which we covered in detail in Lesson 2.
A quick reminder: risk tolerance describes how much of a price loss you can stomach without lying awake at night or selling in a panic. Risk capacity describes how much loss your wallet can absorb without putting you in financial difficulty – determined by your financial situation and your investment horizon.
Both factors need to be in line. An example: you’re young, earn a good salary and could easily cope with a 50% price loss financially. But at minus 20% you get nervous and sell. In that case it’s not your risk capacity that counts but your risk tolerance – it sets the tighter limit. Conversely, if you see yourself as a risk-taker but want to buy a flat in three years, you should stick to your lower risk capacity. In short: whichever of the two factors is more cautious sets the limits.
From theory to practice: splitting your assets
Based on your risk profile, you divide your freely available investment capital into two parts: a high-risk portion and a low-risk portion. As a rule of thumb: the higher the equity share, the riskier – but also the higher-yielding – your portfolio.
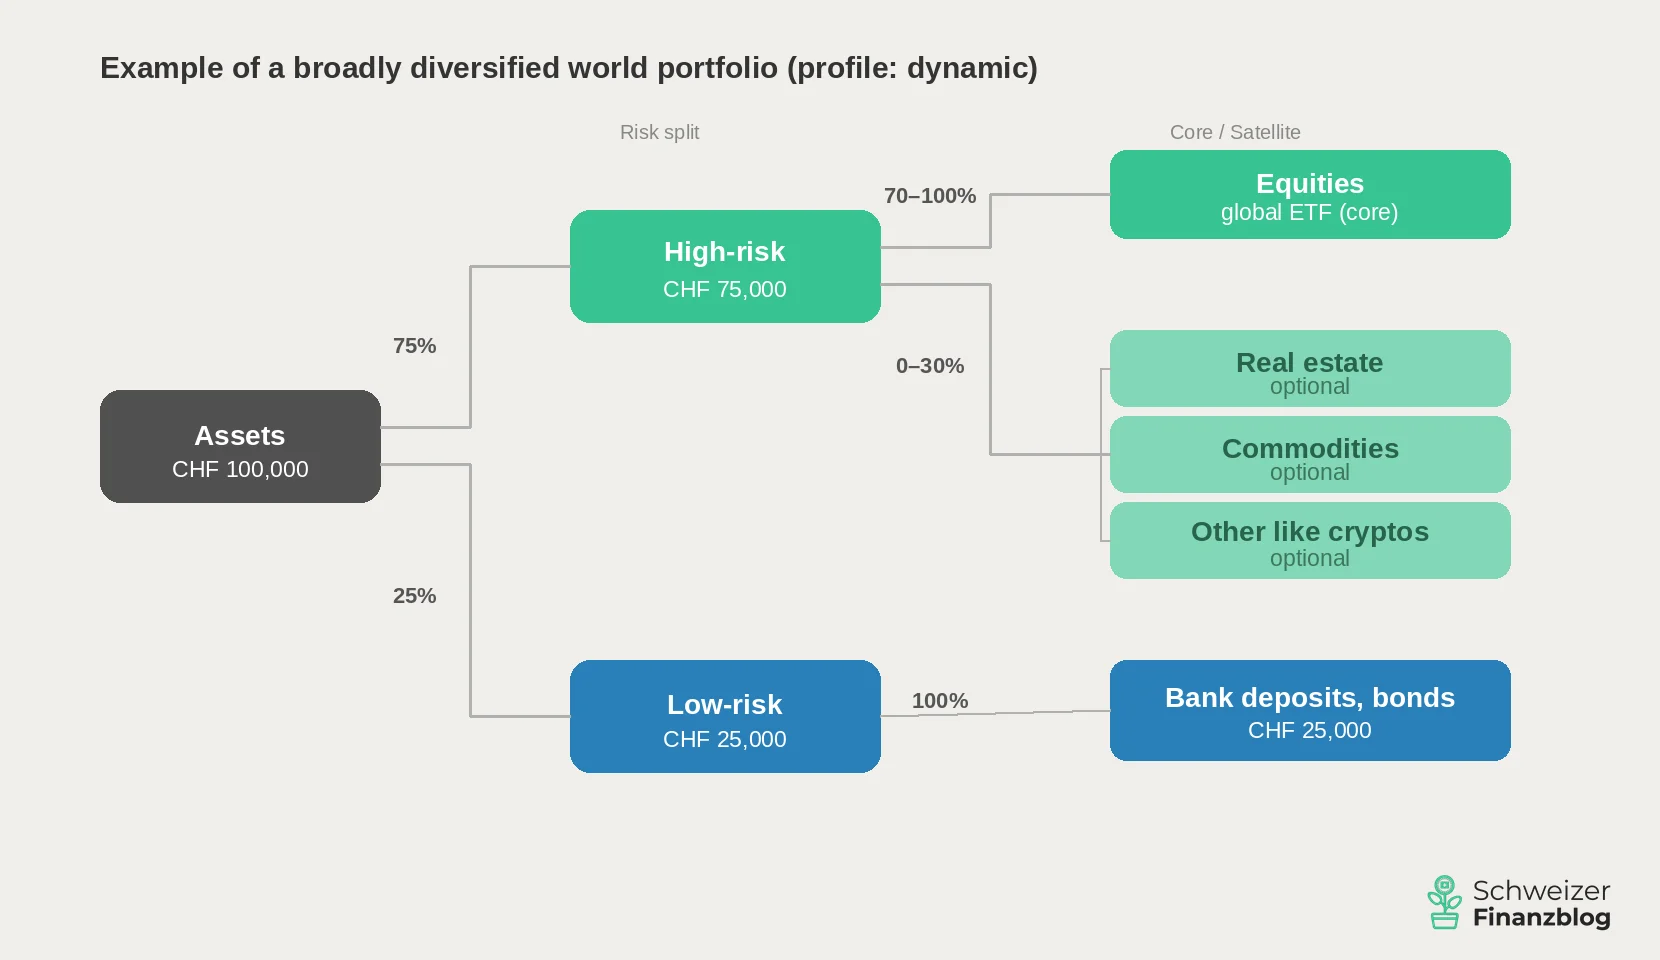
Let’s assume a fictitious investment capital of CHF 100,000 – your emergency fund is already in place. You have a regular income and your running costs under control. Five typical ways to split your assets:
| Risk profile | High-risk* | Low-risk** | Historical return p.a.*** | Max. loss*** | Min. investment horizon |
|---|---|---|---|---|---|
| Defensive | 0–20% | 80–100% | 1–2% | up to –12% | 0–2 years |
| Conservative | 20–40% | 60–80% | 2–3% | up to –23% | 3–4 years |
| Balanced | 40–60% | 40–60% | 3–4% | up to –35% | 5–7 years |
| Dynamic | 60–80% | 20–40% | 4–5% | up to –46% | 7–9 years |
| Aggressive | 80–100% | 0–20% | 5–6% | up to –58% | 10+ years |
For the aggressive profile, we recommend an investment horizon of at least 10 years because of its high volatility. More conservative models with a low equity share, on the other hand, are also suitable for shorter periods.
The high-risk portion: equities at the core, add-ons as satellites
The high-risk portion is the return engine of your portfolio – and its most important building block is equities.
“In the high-risk portion, there’s no way around equities.”
In concrete terms, it does four jobs:
- Long-term wealth building: Equities are the asset class with the highest historical return – and compounding makes your money grow exponentially over decades.
- Inflation protection: While bank deposits lose value in real terms, equities offer effective long-term protection against inflation.
- A stake in the global economy: With a global ETF, you benefit from the growth of thousands of companies – without having to analyse a single one.
- Passive income: Broadly diversified equity ETFs pay out dividends regularly – depending on the fund, either straight to your account or automatically reinvested, which boosts the compounding effect.
ETFs that track broad market indices across all regions of the world are particularly well suited as investment vehicles. You’ll find out why we consider ETFs especially attractive for investing in Lesson 6.
A global ETF as the foundation
The simplest and at the same time most elegant solution: with a single global ETF – such as the Vanguard FTSE All-World or an MSCI ACWI ETF – you invest in thousands of companies from developed and emerging markets, weighted by market capitalisation. One purchase, global diversification, minimal effort. That’s the core idea of passive investing – and the ideal starting point for most investors.
Targeted add-ons using the core-satellite principle
If you want to go beyond this foundation, you can apply the core-satellite approach from Lesson 3. The core – 70 to 100% of the high-risk portion – remains a broadly diversified equity ETF. If you like, you can fill the rest, up to a maximum of 30%, with targeted add-ons in the satellite:
- Real estate via globally diversified REITs (real estate investment trusts) can improve the risk-return ratio thanks to their partly lower correlation with the stock market.
- Commodities such as gold can act as an inflation hedge and crisis buffer – but don’t generate any ongoing income.
- Cryptocurrencies such as Bitcoin are among the most volatile asset classes of all – if you invest here, you should be able to withstand sharp swings and only use money you could do without in an extreme case.
- Other options such as collectibles, crowdlending, factor ETFs or individual stocks are conceivable for risk-takers – as a small add-on, not as a core building block.
Rule of thumb: the more exotic the investment, the smaller its weighting.
The low-risk portion: security and availability
The low-risk portion is the anchor of stability in your portfolio – and a sedative for your nerves. When stock markets drop 30% yet again, this is the part that keeps you calm. In concrete terms, it does three jobs:
- Psychological anchor: When not everything is in the red, it’s easier to hold on and make better decisions.
- Flexibility: If your circumstances change unexpectedly – a new job, a move, unplanned expenses beyond your emergency fund – you have room to manoeuvre.
- Rebalancing ammunition: After a crash, you can buy equities cheaply and bring your portfolio back into balance (more on this in Lesson 5).
Bank deposits – in a savings or personal account – are the simplest and most liquid option. You can access them at any time. In Switzerland, deposits of up to CHF 100,000 per person and bank are protected by deposit insurance. The expected return is clear: at best some protection against inflation, but no real growth in wealth. That’s not this portion’s job anyway – it’s meant to give you security and room to act.
High-quality bonds – such as Swiss federal government bonds with a top “AAA” rating – also offer a high level of security. Historically, however, their return in Switzerland has been close to inflation. If you’re hoping for a meaningful return after inflation, Swiss bonds will usually disappoint you. Still, they can play a role as a stabiliser in a portfolio – especially for investors with a balanced or conservative profile.
Other options such as medium-term notes or fixed-term deposits offer a bit more return than a savings account, but tie up your capital for a fixed term. You’ll find an overview in Lesson 2.
“Setting your individual asset allocation, tailored to your risk profile, is the be-all and end-all of investing.”
And what about Pillar 3a?
A question we get again and again: where in my asset allocation does my 3a money actually belong – low-risk or high-risk?
Our answer: neither. Your 3a assets are tied-up retirement savings – you can’t simply withdraw them whenever you want. Early withdrawals are only possible in a few cases, such as buying a home, emigrating or becoming self-employed. That’s why Pillar 3a doesn’t belong in the same drawer as your freely available assets but follows its own rules.
That doesn’t mean you should ignore it, though – quite the opposite. If you still have 10, 20 or more years until retirement, you’re sitting on a huge compounding lever. And that’s exactly why we recommend investing your third pillar in equities. The biggest return killer? Fees. Traditional bank products often charge 1% or more per year – sounds like little, but over the long term it can add up to tens of thousands of francs in lost returns. Low-cost online providers with fees below 0.5% make a huge difference here.
– Partner offers –
Still looking for the right financial solution? Our recommendations – with attractive sign-up bonuses.
– – – – –
Conclusion
Asset allocation is the most important decision you make when investing – more important than the choice of individual products, more important than the timing of your entry, more important than whether you buy ETF A or ETF B. It’s your guiding star, the point you align every other investment decision with.
The principle is simple: first, secure your liquidity reserve. Then divide your freely available assets into a high-risk and a low-risk portion based on your risk profile. In the high-risk portion, broadly diversified equity ETFs form the core – if you like, you can add to them using the core-satellite principle. In the low-risk portion, bank deposits provide stability and a good night’s sleep. You look at your 3a assets separately – invested in equities and at low cost.
Write down your target allocation – so that you can monitor it periodically and take corrective action when needed. Because when equities rise or fall, the weighting shifts automatically. How to restore your original portfolio structure easily and at low cost is the topic of our next lesson: Rebalancing.
You’ll find an overview of all lessons here: Learn to invest – in eight lessons.
You might also be interested in
Updates
2026-06-12: Minor adjustments made.
2026-05-19: Table of historical returns and losses adapted to Swiss conditions (adjusted for inflation and currency).
2026-04-10: Article completely revised and updated.
Disclaimer
Disclaimer: Investing involves the risk of loss. You have to decide for yourself whether or not you want to take on these risks.
Errors excepted: We have written this article on asset allocation to the best of our knowledge and belief. Our goal is to provide you, as a private investor, with information on financial topics that is as objective and meaningful as possible. If we have nevertheless made mistakes, or if important aspects have been forgotten and/or are no longer up to date, we’d be grateful if you let us know.
About the authors
Stefan Huser
Stefan has been investing in the stock market himself since 2015. He has been shaped by Markowitz’s portfolio theory and Gerd Kommer’s book “Souverän investieren”. He follows a core-satellite strategy: a global equity portfolio of ETFs forms the core, complemented by alternative investments. At the blog, he mainly takes care of the writing. Stefan lives with his family in Zurich and is interested in literature, photography and financial freedom.
Antun Brcina
Antun (“Toni”) has been investing in the stock market since 2015. Financially, he has been particularly inspired by Gerd Kommer’s book “Souverän investieren” and the Fama-French five-factor model. His money is invested in a broadly diversified, long-term global equity portfolio of ETFs. At the blog, he mainly works on the calculators and the code. Toni lives with his family in the Zurich area and is interested in sports, technology and entrepreneurship.

10 Comments
Hallo, welche tools benutzt Ihr um das Portfolio bei mehreren Positionen aufzuschlüsseln? Konkret: bei mir gibt es zB die Positionen FWRA (Invesco FTSE all world ) , WOSC (State street SPDR MSCI Wrld SmlCap) und SPIA (UBS Core SPI). Mein Depot bei Saxo ermöglicht keine detaillierte Analyse zur Überprüfung, ob sich dabei regional oder spartenmässig Klumpenrisiken verstecken. Schaut Ihr Euch das an? Oder reicht eine grobe Schätzung?
Danke und Gruss
Kathrin
Hoi Kathrin
Für das periodische Prüfen der Asset Allocation verwenden wir in der Praxis ein einfaches Excel-File. Darin führen wir die einzelnen ETFs auf und kategorisieren sie nach Regionen sowie nach Grösse (Standardwerte vs. Nebenwerte).
Die konsolidierten Ist-Werte gleichen wir anschliessend mit den definierten Zielwerten ab (z.B. 80/20% entwickelte Märkte/Schwellenländer sowie 80/20% Standardwerte/Nebenwerte). Die entsprechenden Abweichungen werden dabei mittels Formeln automatisch ausgewiesen und als Grundlage für Anpassungen bzw. fürs Rebalancing genutzt.
Auf weitergehende Analysen – etwa zur genauen Sektorengewichtung – verzichten wir bewusst. Sowohl in deinem (gemäss deinen Beispielen) wie auch in unserem Fall handelt es sich um breit diversifizierte, nach Marktkapitalisierung gewichtete ETFs. Das bedeutet: Einzelne Sektoren können zeitweise ein höheres Gewicht haben, dies ist jedoch eine Folge ihrer aktuellen Marktbedeutung (Marktkapitalisierung) und keine bewusste Übergewichtung einer bestimmten Branche. Es widerspiegelt letztlich die Entwicklung und den Erfolg der jeweiligen Sektoren am Markt.
Beste Grüsse
SFB
Ich habe nur die 4te Edition des Buches, dort wird es bei der Asset Allocation noch gelistet. Interessant, dass das die 5te Edition nicht mehr listet.
Demnach sollte man nur in Aktien ETFs und Immobilien ETFs investieren?
Was ist da so der übliche Split im Portfolio oder was empfehlt ihr/Kommer? 70% ETF entickelte Länder und 30% Emerging Markets? Und mit Immobilien: 60% ETF Entwickelte Länder, 30% ETF Emerging Markets, 10% ETF Immobilien?
Ja, bei Kommer stehen beim risikobehafteten Teil der Asset Allocation klar Aktien-ETFs im Fokus. Als Beimischung kommen für ihn (optional) Immobilien-ETFs in Frage. That’s it.
Der “übliche” Split und die einfachste Variante ist, wenn du mit einem einzigen ETF (z.B. Vanguard FTSE All-World) die entwickelte Welt und die Emerging Markets abdeckst, und zwar nach Marktkapitalisierung gewichtet, einschliesslich der Mid und Small Caps (Gemäss Kommer ist dies Variante 1). Dazu kannst du beispielsweise 10 Prozent Immobilien-ETFs beimischen (Kommer’s Variante 2). Bei Kommer’s Varianten 3 und 4 spielt das Factor Investing eine zentrale Rolle. Faktorbasiertes Investieren ist also das Übergewichten von Faktorprämien in einem Portfolio gegenüber einer marktneutralen Gewichtung (Variante 1). Bei der marktneutralen Gewichtung machen die Schwellenländer rund 11% aus. Wenn du diesen Faktor (“Political Risk”) stärker gewichten möchtest, musst du über diesen Anteil gehen. Stefan und Toni sind innerhalb der risikobehafteten Anlageklassen in Aktien-ETFs (70 – 80%; inkl. Übergewichtung der Faktoren “Small Size” und “Political Risk” sowie Toni zusätzlich “Momentum”), Immobilien-ETFs (10-20%) sowie Crowdlending bzw. sog. P2P-Kredite (ca. 10%) investiert. Letztere Anlageklasse empfiehlt Kommer übrigens nicht.
Hallo zusammen
Gerd Kommer empfiehlt ebenfalls Rohstoffe beizumischen. Was sind hier Eure Erfahrungen? Und was für Rohstoffe würdet Ihr beimischen? Geht das auch über DEGIRO?
Hoi Lena
Vorab: Die Asset Allocation ist für uns ein zentrales Element bei der Geldanlage, welches leider bei vielen Anlegerinnen und Anlegern zu kurz kommt. Denn durch die vordefinierten Zielanteile der unterschiedlichen Assetklassen wird ein regelbasiertes und (weitgehend) unemotionales Investieren ermöglicht, was letztlich der Rendite zugutekommt. Deshalb freut uns deine Anfrage zu diesem wichtigen Thema besonders.
In Kommer’s aktueller 5. Auflage seines Standardwerks “Souverän Investieren…” nimmt er gegenüber Rohstoffen eine sehr differenzierte bis ablehnende Haltung ein. So kommt er in Kapitel 5.7 zu folgendem Fazit: “Ich persönlich finde mich seit 2016 eher im Lager der Skeptiker (wo ich fast immer bin, wenn es keinen starken Konsens in der Wissenschaft gibt) und würde daher dafür votieren, auf Commodities bzw. Commodity-Futures in der Zukunft zu verzichten.”
Auch wir vom Schweizer Finanzblog sind nicht in die Assetklasse “Rohstoffe” investiert – zumindest nicht im herkömmlichen Sinn. (Stefan ist seit vielen Jahren in den Clean Energy ETF von iShares investiert.)
Beste Grüsse
SFB
Hallo zusammen
Wird eigentlich das 3. Säulenkonto, welches auch längerfristig ausgerichtet ist (Bis man halt 65 Jahre alt ist) auch in diese Asset Allocation als “Risikoarmer Teil” mit eingerechnet werden? Hier bezahle ich den jährlichen Maximalbetrag von 6883 CHF jeweils ein. -> Diese Einlage wird allerdings auch in diverse Anlagen investiert von meiner Bank.
Danke für eure Rückmeldung und LG
Hoi Allen
Nein, wir würden die 3. Sàule nicht dem risikoarmen Teil zuordnen, da du ja nicht sofort darauf zugreifen kannst. Vorsorgesparen ist stark reguliert und vorzeitige Auszahlungen sind auf wenige Ausnahmen beschränkt. Aufgrund des oft langen Anlagehorizonts (Pensionsalter) erachten wir es als sinnvoll, die 3. Säule (auch) in Aktien anzulegen. Wichtig: Tiefe Gebühren (<0,5%), wie sie innovative Online-Anbieter wie Viac haben, bedeuten mehr Rendite und im Alter mehr Vermögen.
Beste Grüsse
SFB
Hallo zusammen
Ich hätte noch eine Frage: was sagt ihr zu einem Home Bias im Aktien Teil des Portfolios? Z.b. indem man noch 10-20% auf den SPI setzt? Als Währungsabsicherung.
Danke für eine Antwort 🙂
Sonnige Grüsse
Hoi Eliana
Bei 10 bis 20% Beimischung von CH-Aktien hält sich der von dir erwähnte “Home Bias” in Grenzen. Also alles im grünen Bereich:-) Der SPI ist aus unserer Sicht jedoch ein ausgesprochen schlecht diversifizierter Index (die drei Titel Nestlé, Roche und Novartis sind mit rund 45% (zu) stark gewichtet), weshalb wir darauf basierende ETFs nicht empfehlen. (Der SMI ist bezüglich Klumpenrisiken noch schlechter.) Als bessere Alternative sehen wir den SPI Mid (80 CH-Unternehmungen mit mittlerer Marktkapitalisierung; die drei grössten Positionen machen gesamthaft rund 16% aus). Quelle: https://www.ubs.com/2/e/files/RET/FS_RET_CH0130595124_CH_DE.pdf
Beste Grüsse SFB