By Stefan Huser and Antun Brcina
Updated on
What happens if you leave CHF 10,000 sitting in a savings account for several decades – and what happens if you invest it in a broadly diversified range of stocks? Saving feels safe. Investing sounds risky. But once you know the numbers, you might see things differently. In this article, we compare the long-term performance of a savings account with the best-known global equity index, the MSCI World – using real data, concrete examples and explained as clearly as possible. You’ll see why the seemingly safe choice can turn out to be the more expensive one in the long run – and what role compound interest plays in all this. Welcome to the first lesson of our finance guide!

In a nutshell
Imagine two people. Both have saved CHF 10,000 – and neither of them needs the money for the next few decades.
Anna puts her money in a savings account. Safe, convenient, no surprises.
Beat decides differently: he invests in stocks – specifically in a fund that holds the largest companies in all industrialised countries, the MSCI World. In one go, he is essentially buying a small piece of Apple, Nestlé, Toyota and hundreds of other companies.
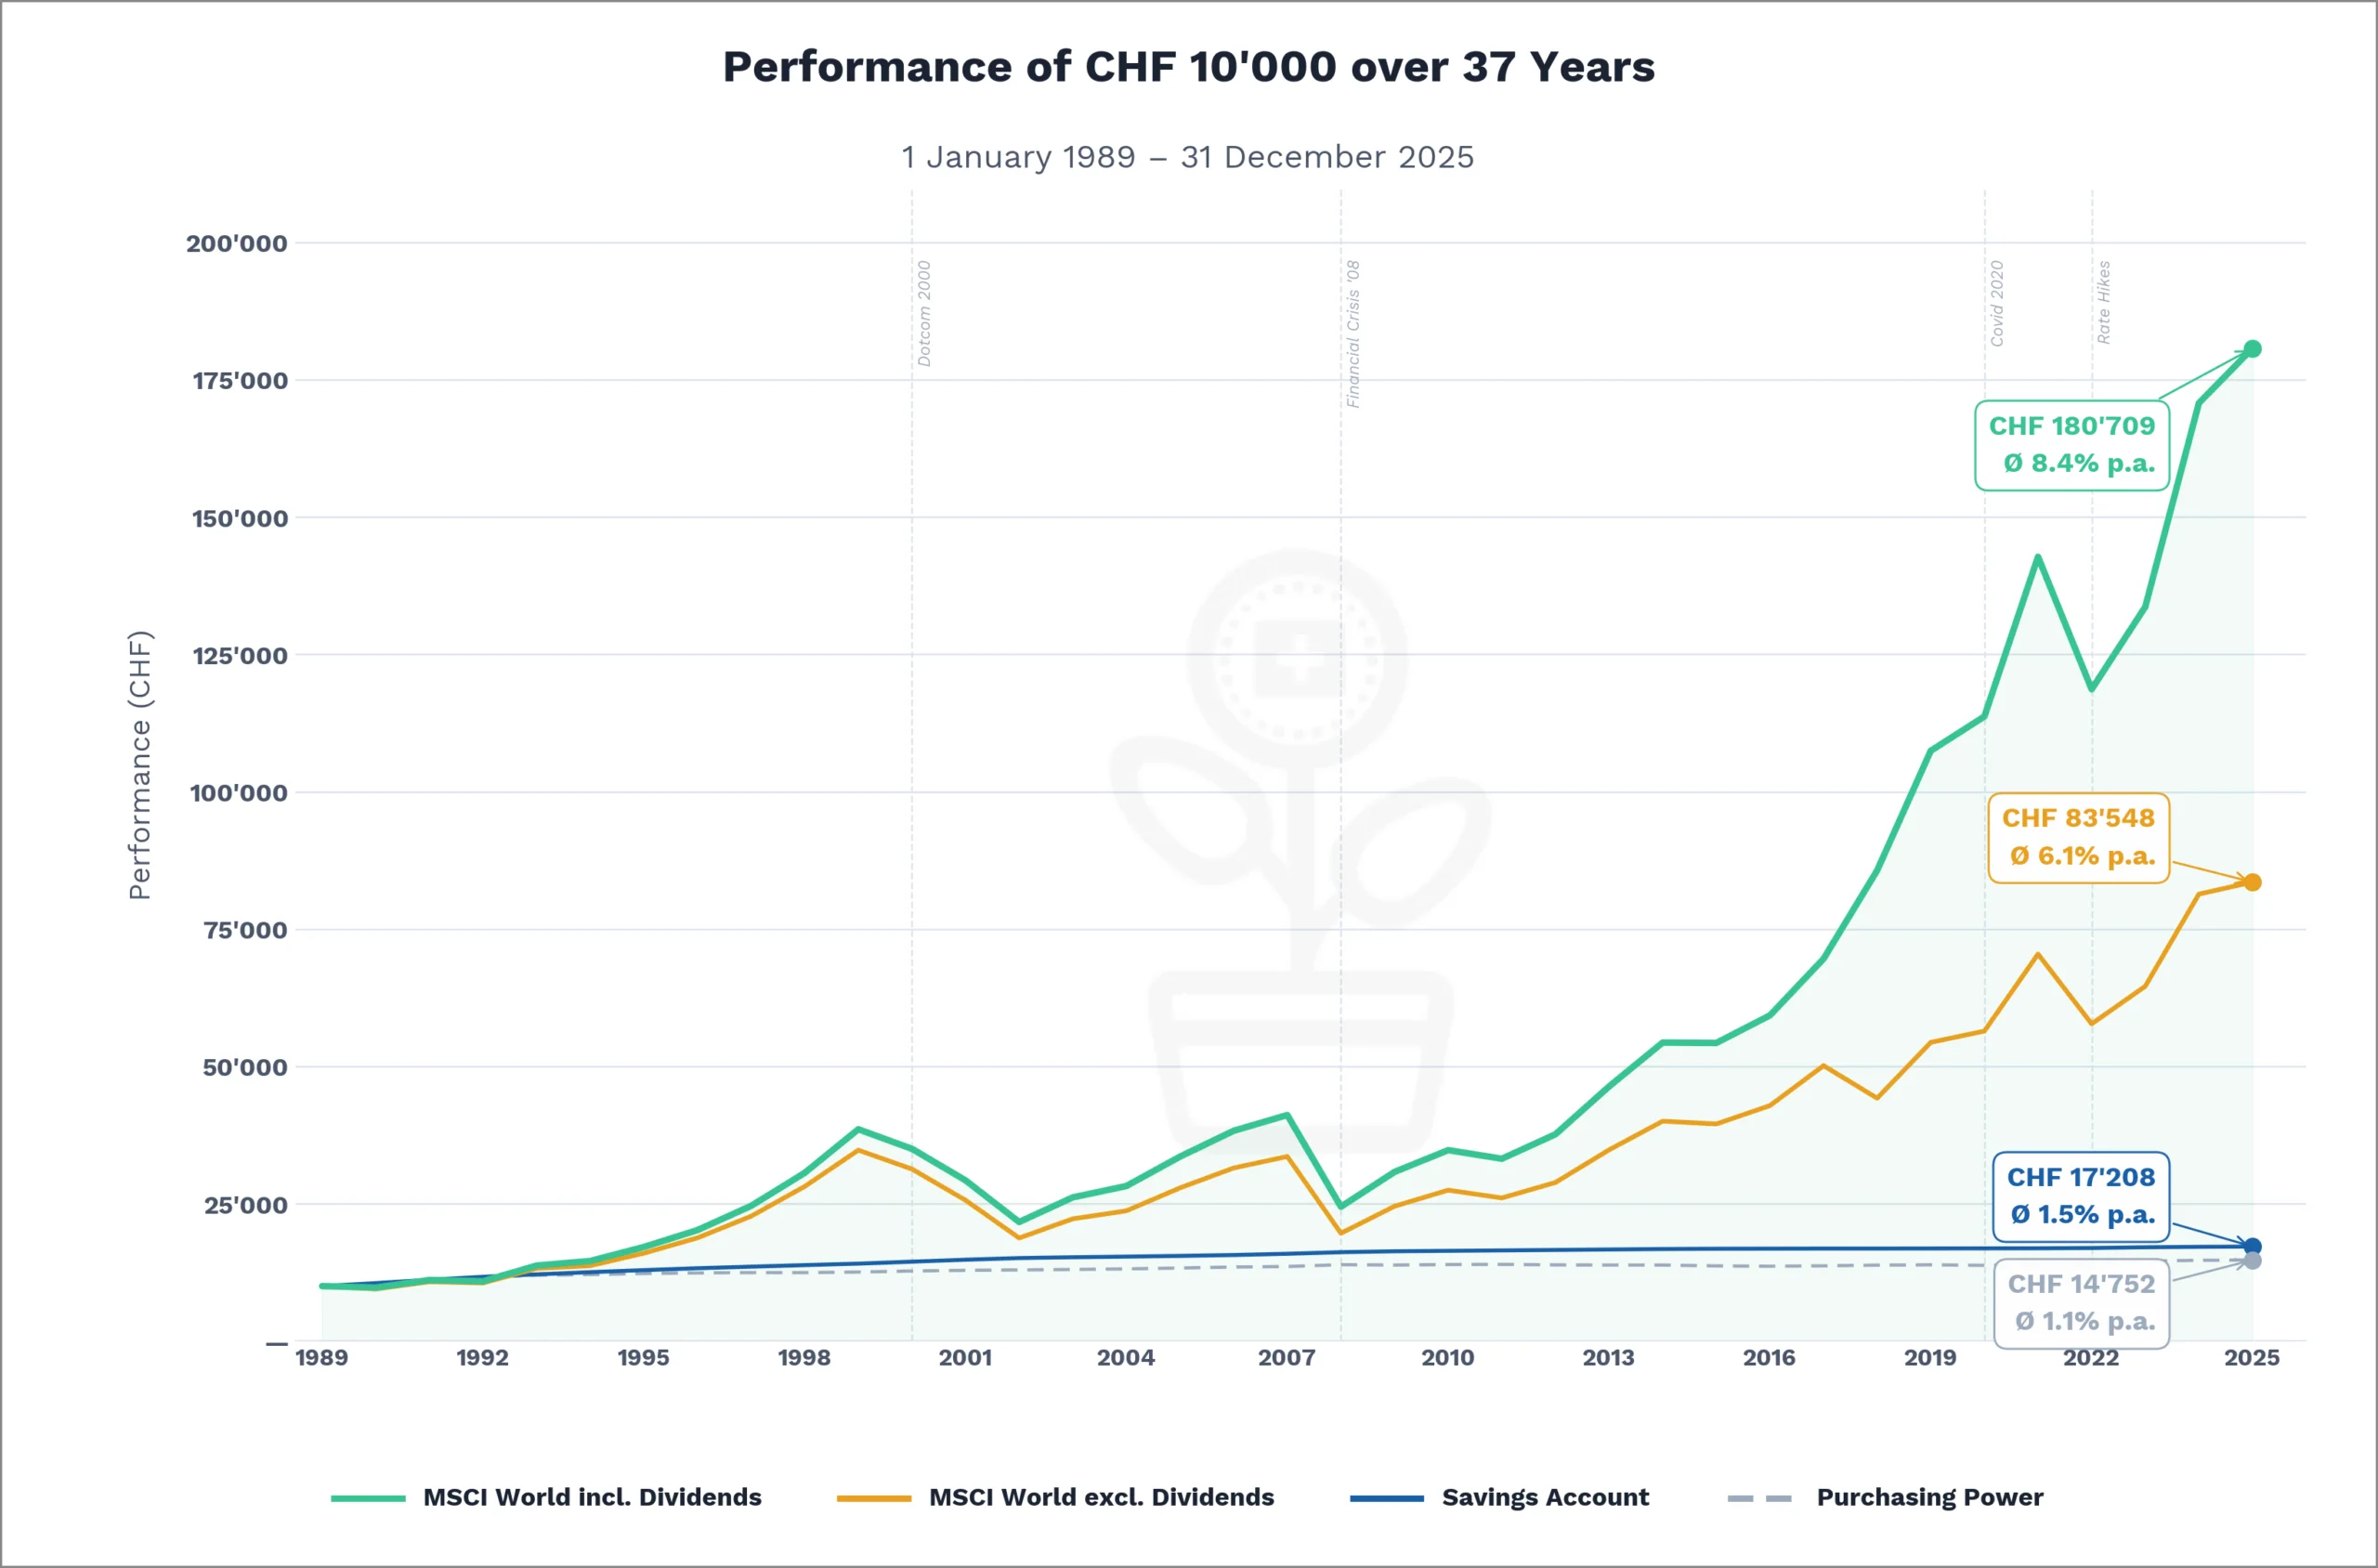
In the end, Anna looks at her account: her CHF 10,000 has grown to around CHF 17,000. Not bad – if it weren’t for inflation, which has quietly eaten up a large part of it.
Beat, on the other hand, has over CHF 180,000 in his account over the same period – 18 times his original stake, at an average annual return of 8.4%.
How is that possible? The answer lies in three factors – one of which is particularly underestimated:
What really matters is what happens to the gains. If the dividends paid out are spent every year, Beat ends up with around CHF 83,000. If, however, they are automatically reinvested, the money keeps working and in turn generates new gains. Gains on gains. Year after year. The result: over CHF 180,000.
The chart shows the difference clearly: in the upper line, dividends are reinvested – compound interest works at full strength. In the lower line, they are paid out – compound interest only has a limited effect, namely via price gains. The gap between the two widens every year.
This effect is called compound interest. Albert Einstein is said to have once called it the eighth wonder of the world – and the numbers prove him right.
Now you might object: I don’t have that many decades. Fair enough.
So let’s assume a shorter investment horizon – say ten years. In our view, that’s the minimum for investing in stocks. After all, stocks can fluctuate very strongly in the short term: in a single year (2008), the MSCI World lost more than 40% of its value!
That brings us to the next tough nut to crack: the supposedly right time to get in.
To find out, we have Anna and Beat invest their starting capital of CHF 10,000 in every possible 10-year period since 1989 – and look at the results.
We also assume that both Anna and Beat leave the income – interest or dividends respectively – in their investment. That way, both benefit from compound interest.
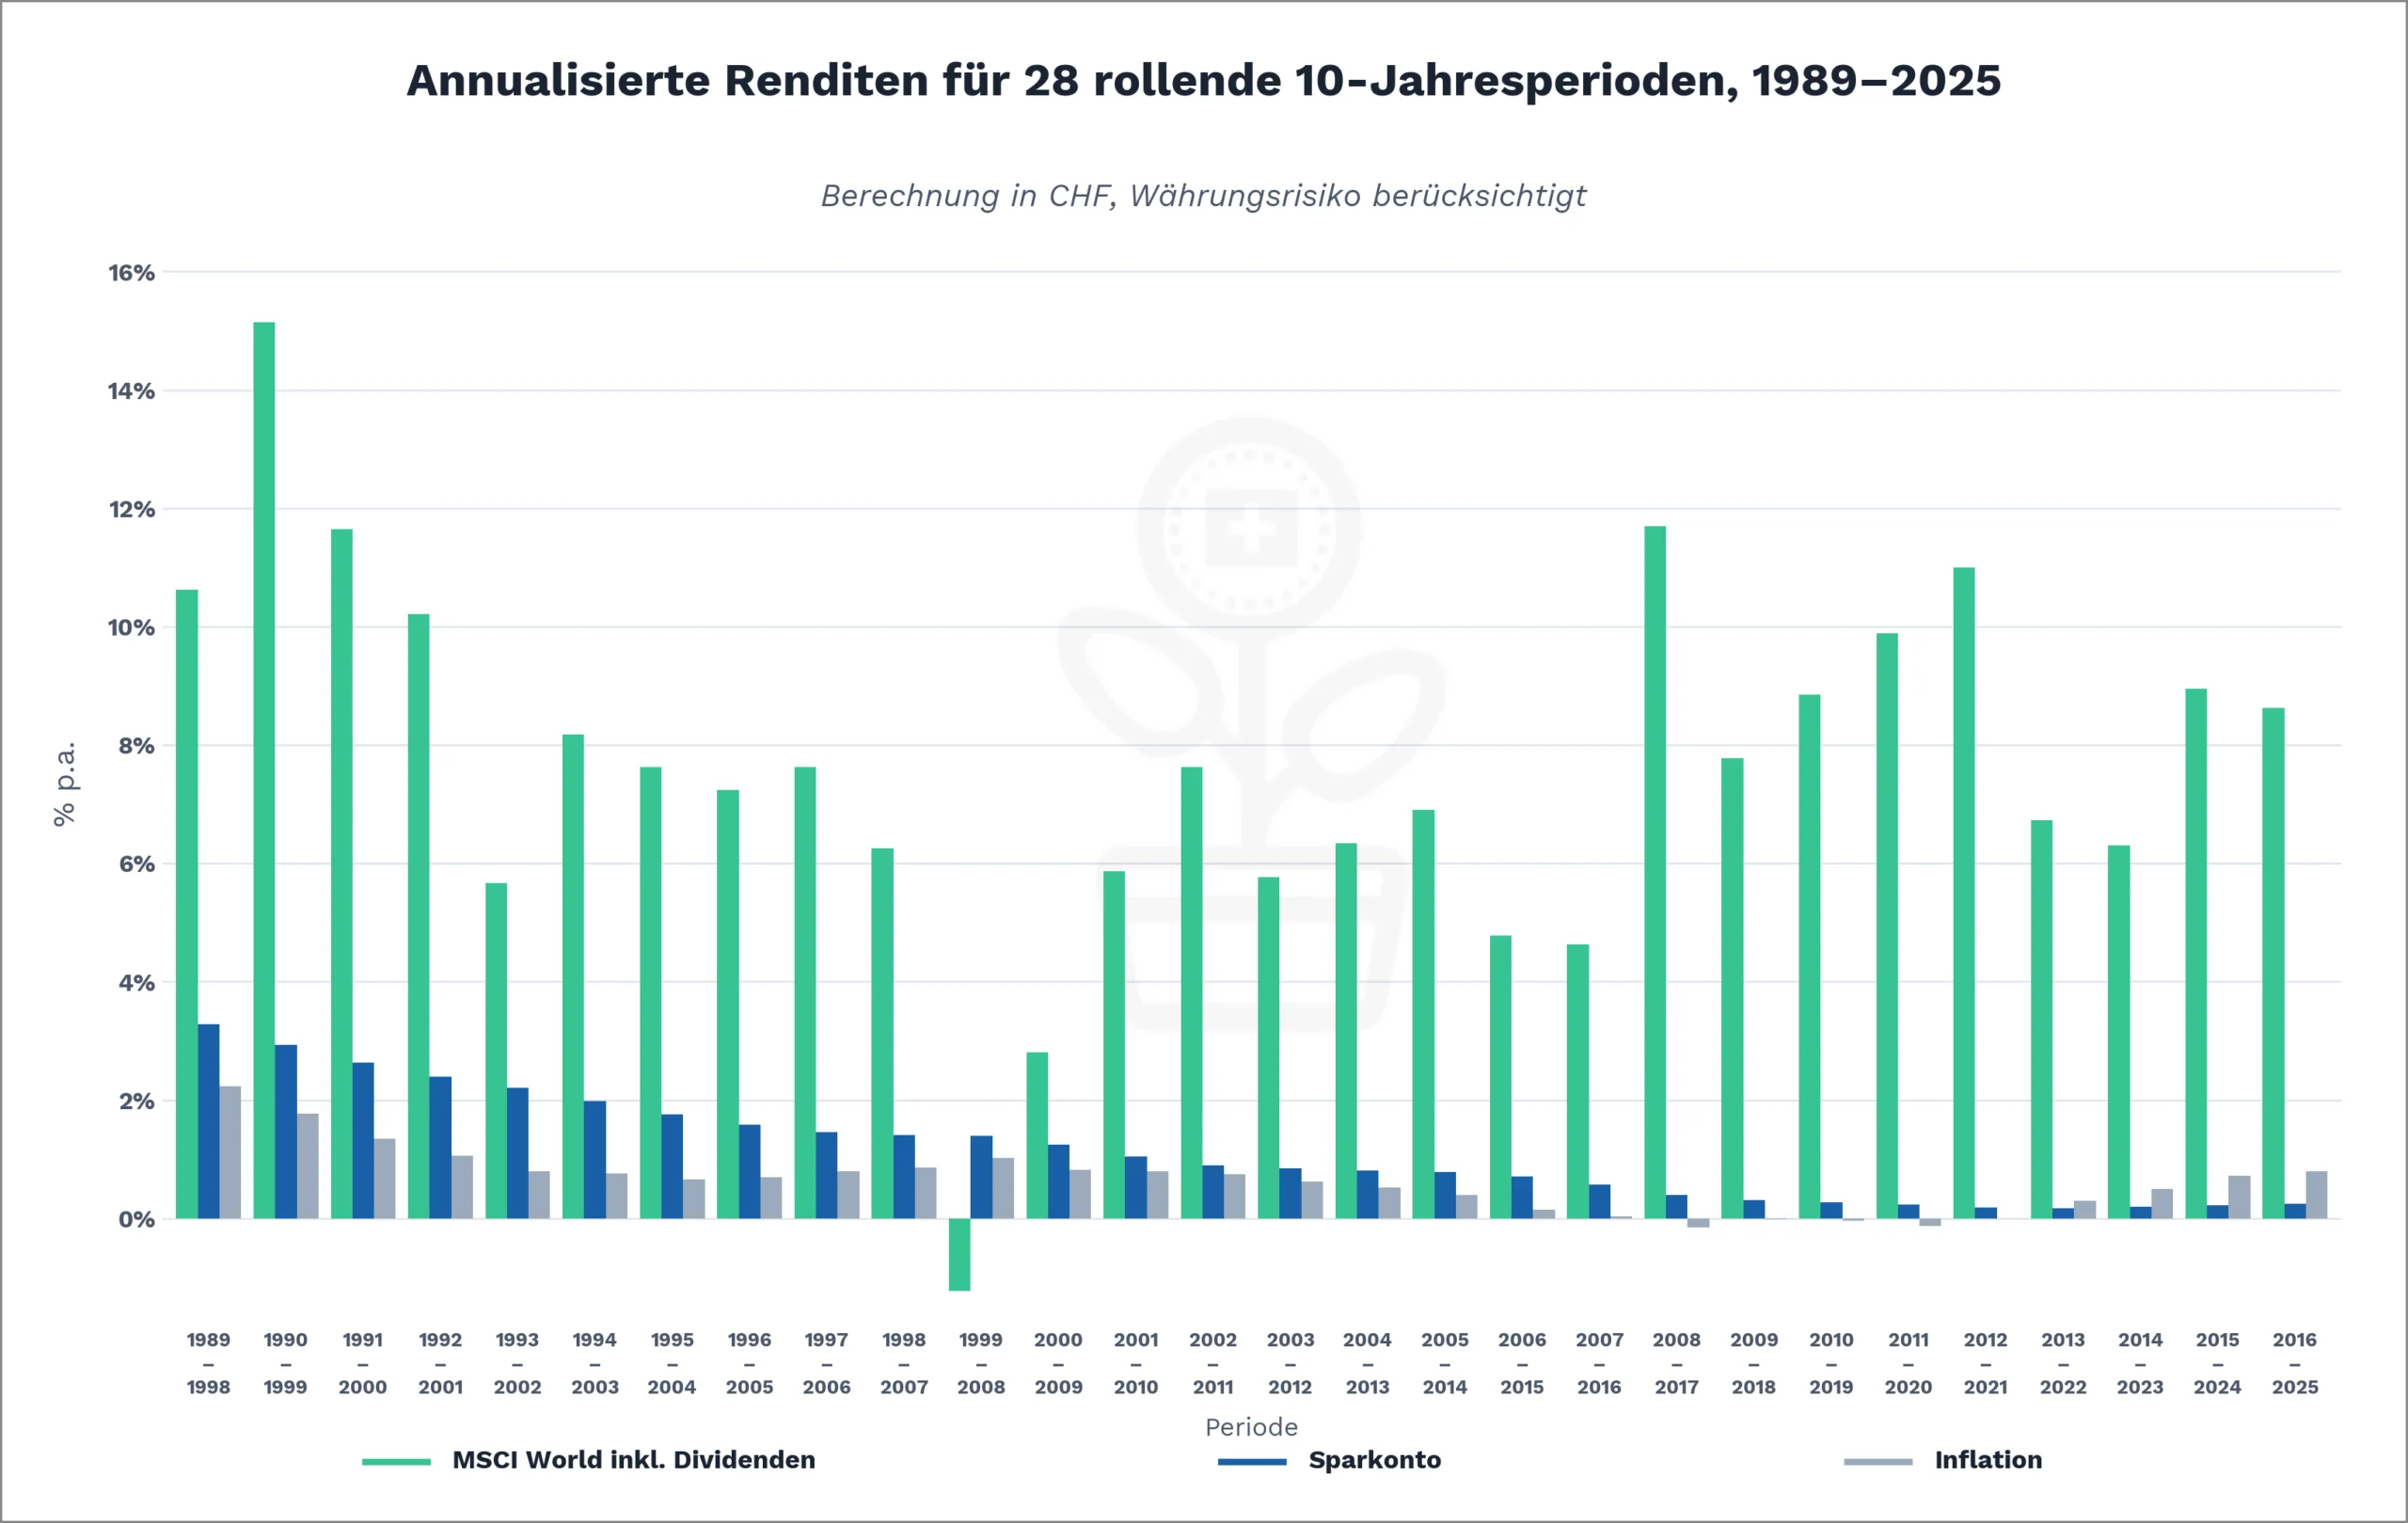
In almost every 10-year period, investing in stocks yields a much higher return than the savings account – with one single exception.
For Anna, the period 1989–1998 shines with 3.28% a year. The worst is 2013–2022: a measly 0.17% nominal.
Beat achieves his best return in the period 1990–1999: a hefty 15.14% a year. Things go worst in the period 1999–2008 – a loss of 1.23% a year. A double stroke of bad luck: Beat got in right at the peak of the dot-com bubble, of all times, and the 2008 financial crisis spoiled his performance shortly before the end of the ten years.
The problem: we don’t know the right time to get in – and those who wait for it often wait too long. The solution is as simple as it is effective: invest regularly instead of speculating on the perfect moment. If you invest monthly, you sometimes buy high and sometimes low – and over time this smooths out the impact of price fluctuations.
Particularly striking: from the 2013–2022 period onwards, the savings account no longer makes up for inflation. Anyone who left their money there lost purchasing power despite nominal interest.
Please note: our calculations do not take currency risks, costs or taxes into account.
Costs hardly make a difference: the savings account is free, and ETF fees are minimal today – often below 0.2% a year. We cover currency risks and taxes in later lessons.
– Partner offers –
Still looking for the right financial solution? Our recommendations – with attractive sign-up bonuses.
– – – – –
The numbers are clear: investing – long-term and broadly diversified in stocks – delivers much higher returns than a savings account. Compound interest quietly does its job – the longer, the more powerful. There is no such thing as the “right” time to get in – and if you wait for it, you lose valuable time.
This lesson has shown what was possible historically – not what is guaranteed. Whether and how you invest yourself depends on your personal situation and your risk profile. That’s what the next lessons are about.
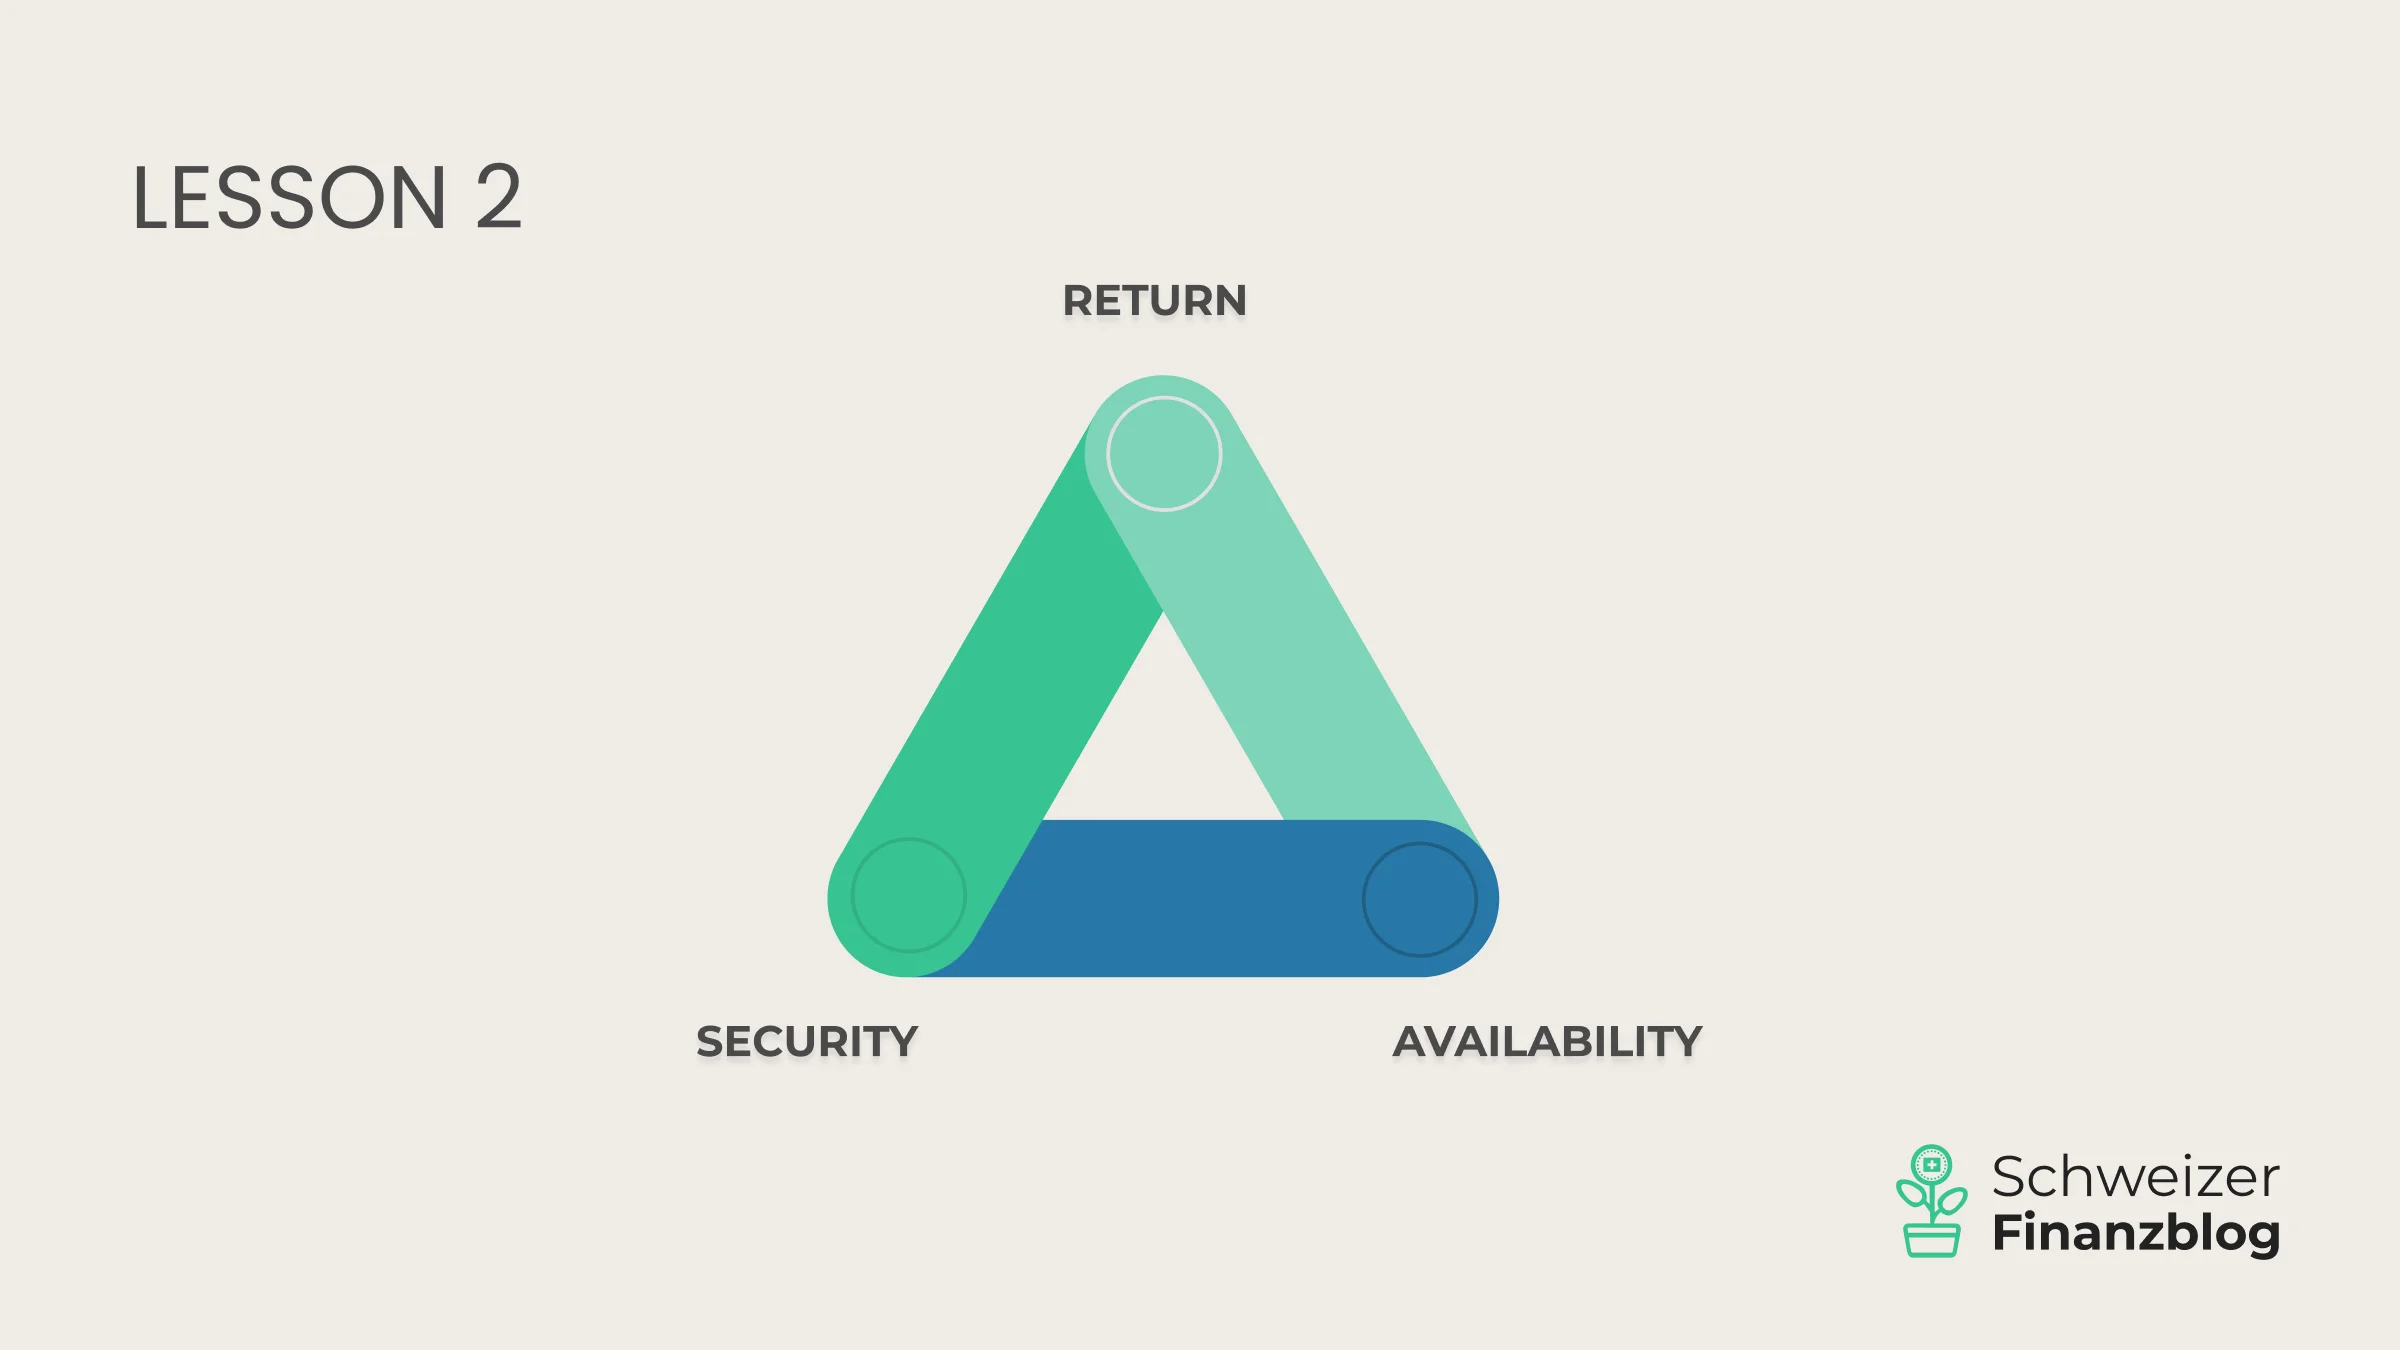
In Lesson 2, we take a closer look: what’s behind the relationship between risk and return – and why can you never have one without the other?
You’ll find an overview of all lessons here: Learn to invest – in eight lessons.
2026-06-12: Minor adjustments made.
2026-03-27: Text and data updated.
Disclaimer: Investing involves the risk of loss. You have to decide for yourself whether or not you want to bear these risks.
Errors excepted: We have written this article about investing to the best of our knowledge and belief. Our aim is to provide you as a private investor with information on finance that is as objective and meaningful as possible. Should we nevertheless have made mistakes, or should important aspects have been forgotten and/or be out of date, we would be grateful if you let us know.
 X