
 Newsletter
Over 2,000 ETFs on the Swiss stock exchange SIX Swiss Exchange alone – how are you supposed to find the right one? The good news: with a few clear criteria, the range shrinks to a manageable selection. The even better news: for most investors, a single ETF is enough. In this seventh lesson of our finance guide, you’ll find out which criteria really count, how to clear a systematic path through the ETF jungle and how to choose the ETF that’s right for you.
< Lesson 6 | Overview | Lesson 8 >

In a nutshell
- Choosing the right index matters more than choosing the ETF product: a broadly diversified, market-cap-weighted equity index forms the basis.
- For a complete global portfolio, a single global ETF is enough – for example one on the FTSE All-World or the MSCI ACWI.
- The key selection criteria are low costs (TER), a convincing tracking difference, a large fund size and physical replication.
- ETFs on MSCI indices should not be combined with ETFs on FTSE indices – otherwise you risk gaps or overlaps in your portfolio.
- With a long-term investment horizon, you should do without currency hedging for cost reasons.
Contents
Not all ETFs are created equal
In Lesson 6, you learned what ETFs are and why they are the ideal investment vehicle for you. But not all ETFs are created equal. The universe is huge – and covers far more than just shares. On the Swiss stock exchange SIX alone, you’ll find over 2,000 ETFs on a wide range of asset classes: shares, bonds, real estate, commodities or even cryptocurrencies. On top of that, there are ETFs that focus on specific sectors, themes, strategies or factors.
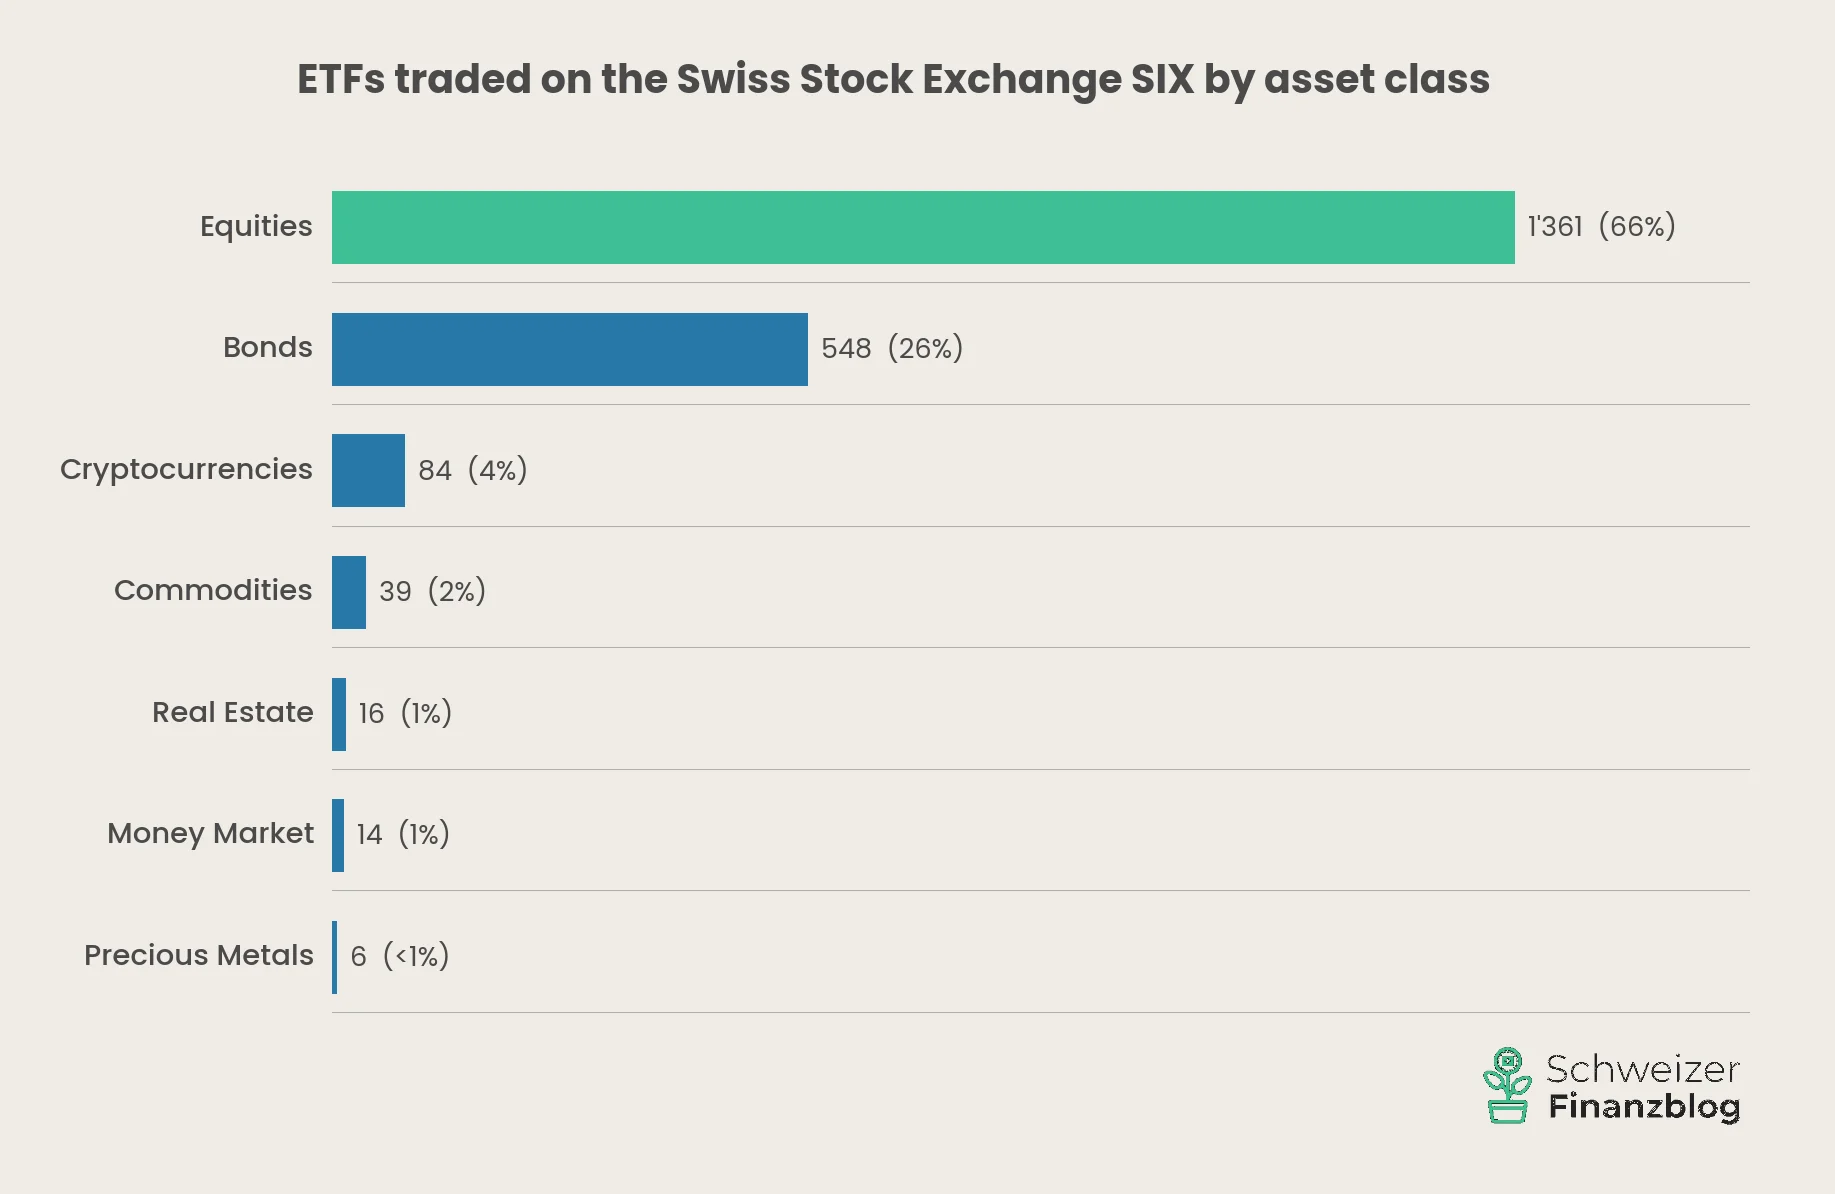
When building your portfolio, it is therefore crucial to choose the right category – before you look at individual products.
Core ETFs as the heart of your portfolio
This guide is about building wealth over the long term. Broadly diversified equity ETFs are best suited to this – specifically, those that track a global index weighted by market capitalisation. That’s exactly what we do too.
These so-called core or “bread-and-butter” ETFs invest in thousands of companies and form the foundation of a solid global portfolio. Some providers even label these products explicitly: iShares, for example, uses the label “Core” for its standard products, as opposed to “Edge” for specialised and thematic ETFs.
In our ETF comparison Best ETFs in Switzerland and globally, we focus exclusively on core products like these – and they are also the focus of this lesson.
Specialist ETFs as satellites
There are also ETFs that invest specifically in individual sectors (e.g. technology), factors (e.g. small caps, value), strategies (e.g. dividends) or themes (e.g. clean energy, artificial intelligence). These products are narrower, less diversified and often more expensive – but they can be interesting as a targeted addition.
This is where the core-satellite strategy comes in, which we introduced in Lesson 3: the core of your portfolio consists of one or a few broadly diversified ETFs. The satellites are optional additions that let you deliberately set accents – for example on a particular region, a theme or an asset class such as real estate. If you’re interested in factor-based approaches such as small caps or value, you’ll find an in-depth analysis in our article Is factor investing worth it?
Important: the satellites are a nice-to-have, not a must. If you want to save yourself the effort, a pure core portfolio will serve you just as well – often even better, because it is simpler and cheaper.
In the following chapters, we focus on the core: which index should you choose, and which criteria can you use to pick the right ETF?
First, find the right index
Choosing the index is the most important decision – ETF criteria such as TER, replication or fund size come afterwards. Or, to put it figuratively: you choose the index like a flat – the ETF criteria are the furnishings. So when choosing an ETF: start with the index, not the product.
As you learned in Lesson 3, broad diversification is the key to a robust portfolio. In concrete terms: indices that cover entire regions or the whole world are preferable to a narrow country or sector index.
One ETF is enough – the simplest solution
If you want to keep things as simple as possible, choose a single global ETF that covers both developed and emerging markets. Two indices are suitable for this:
The FTSE All-World comprises over 4,200 large and mid-sized companies from around 50 countries. Its MSCI counterpart, the MSCI ACWI (All Country World Index), covers a similarly broad market with around 2,500 positions. The even broader MSCI ACWI IMI also includes smaller companies (small caps) and has over 8,000 positions.
With a single ETF on one of these indices, you have a complete, market-cap-weighted global portfolio – without having to worry about the weighting between regions. It doesn’t get any simpler.
Two ETFs – developed world and emerging markets separately
If you want to control the weighting between developed and emerging markets yourself, combine two ETFs: one on the developed world (e.g. MSCI World or FTSE Developed World) and one on emerging markets (e.g. MSCI Emerging Markets or FTSE Emerging Markets).
Regional split – for more control
If you want to reduce the US dominance in the MSCI World – US shares currently make up around 70% of it – you can split the developed world into individual regions: North America, Europe and Asia-Pacific. As there is no single ETF available for the Asia-Pacific region, you need two here: one for Asia-Pacific ex Japan and one for Japan. Together with an emerging markets ETF, this gives you a global portfolio of five to six ETFs – depending on whether you also want to add a Switzerland ETF.
This variant gives you more control over the regional weighting, but also means more work when rebalancing (see Lesson 5).
MSCI or FTSE – but please don’t mix them
The two big index providers – MSCI (USA) and FTSE Russell (UK) – cover the global stock markets differently. Specifically, they don’t always classify individual countries in the same way. FTSE, for example, counts South Korea and Poland as developed markets, while MSCI (still) lists both countries as emerging markets.
That sounds like a detail, but it has practical consequences: if you combine an ETF on the FTSE Developed World with an ETF on the MSCI Emerging Markets, you would have South Korea and Poland in your portfolio twice. Conversely, with the combination MSCI World + FTSE Emerging Markets, these countries would be missing completely.
“Choose one index provider – MSCI or FTSE – and stick with it.”
The simple rule: stick with one index provider. If you use MSCI for the developed world, choose MSCI for emerging markets too – and vice versa. With a single global ETF, the question doesn’t arise anyway. You’ll find a detailed comparison of the two providers’ country classifications in our ETF comparison.
Home bias: why Swiss indices alone aren’t enough
Some people instinctively bet on their home stock market. But the best-known Swiss index, the SMI, contains only 20 stocks – Nestlé, Roche and Novartis together account for around 45%. That is the opposite of diversification. The broader SPI (Swiss Performance Index), with over 200 stocks, is better, but remains a pure country index. What’s more, neither the SMI nor the SPI is UCITS-compliant – the product range and competition are smaller than for global indices.
Swiss indices are therefore not suitable as the sole basis of a portfolio. Swiss shares already make up around 2% of a global ETF such as the FTSE All-World – so you’re already invested. If you still want a Swiss finish, for example to deliberately increase the share of Swiss francs in your portfolio, you can add a Switzerland ETF as a satellite. But that is then a deliberate overweighting – and not a must. You’ll find specific products for this in our ETF comparison.
In Lesson 3, we explained why a strong home bias is one of the most common and most expensive investing mistakes.
Choosing the right ETF: the key criteria
Once you’ve decided on an index, it’s time to choose a specific product. After all, there are often dozens of ETFs from different providers on the same index. The good news: with a few clear criteria, you can narrow the field systematically when selecting an ETF. In our ETF comparison Best ETFs in Switzerland and globally, we apply a strict, multi-stage selection process – in the end, only a handful of products make it to the final. The key criteria at a glance:
Costs (TER)
The total expense ratio (TER) states the ongoing annual costs of an ETF. It is charged directly to the fund’s assets and continuously reduces your return. The lower the TER, the better. For broadly diversified global ETFs, you typically pay between 0.10% and 0.20% per year today. ETFs with a TER above 0.25% are hardly justifiable for broad market indices any more.
Tracking difference – the underrated metric
Even more meaningful than the TER is the tracking difference. It measures how much an ETF’s actual performance deviates from its benchmark index – and thus shows the full picture: including additional income, for example from securities lending, which can partly or fully offset the ongoing costs. A negative tracking difference means that the ETF slightly beat its index despite its costs.
You often won’t find the tracking difference directly on the providers’ factsheets. But you can work it out by comparing the fund’s performance with the index performance. Alternatively, the platform trackingdifferences.com is a good resource. As a rule of thumb, the tracking difference should be in the region of the TER – or even below it. If it is significantly higher, this points to hidden costs.
Fund size
Although the ETF market is growing rapidly, ETFs are regularly closed or merged. Your invested money isn’t lost in the process – it is protected as segregated assets – but the procedure is cumbersome and can incur costs. The main argument for a large fund size is a different one, though: large ETFs are traded more often, which leads to tighter spreads (the difference between the buying and selling price) and therefore lower trading costs every time you buy or sell.
If you want to play it safe, you should choose an established ETF – with a large fund size. In our ETF comparison, we require a minimum fund size of CHF 500 million.
Replication method
Basically, you have two options: physically replicating ETFs actually buy the shares contained in the index – either all of them or an optimised selection (sampling). Synthetic ETFs, on the other hand, replicate the index via a swap with a counterparty, which carries an additional risk. Synthetic ETFs are being phased out; we avoid them.
Launch date
An ETF should have been on the market for at least five years. Only then can you make meaningful performance comparisons and assess the tracking difference over a longer period. A newly launched ETF may be cheap – but whether it keeps its promises over the long term only becomes clear after a few years.
Fund domicile
An ETF’s domicile has tax consequences. For people based in Switzerland, ETFs domiciled in Ireland are generally the most tax-efficient, followed by Luxembourg. The reason lies in the double taxation agreements, which affect the foreign withholding tax burden. In practice, the domicile of the common ETFs on MSCI or FTSE indices is almost always Ireland or Luxembourg – so you rarely need to think about it actively.
You’ll find more in-depth information in our article ETF taxes in Switzerland: optimise your portfolio with these 5 tax-saving tips.
What an ETF’s name tells you
ETF names look cryptic at first glance, but they follow a clear pattern. The following graphic shows what the individual components stand for, using the example of the “Vanguard FTSE All-World UCITS ETF (USD) Accumulating”:
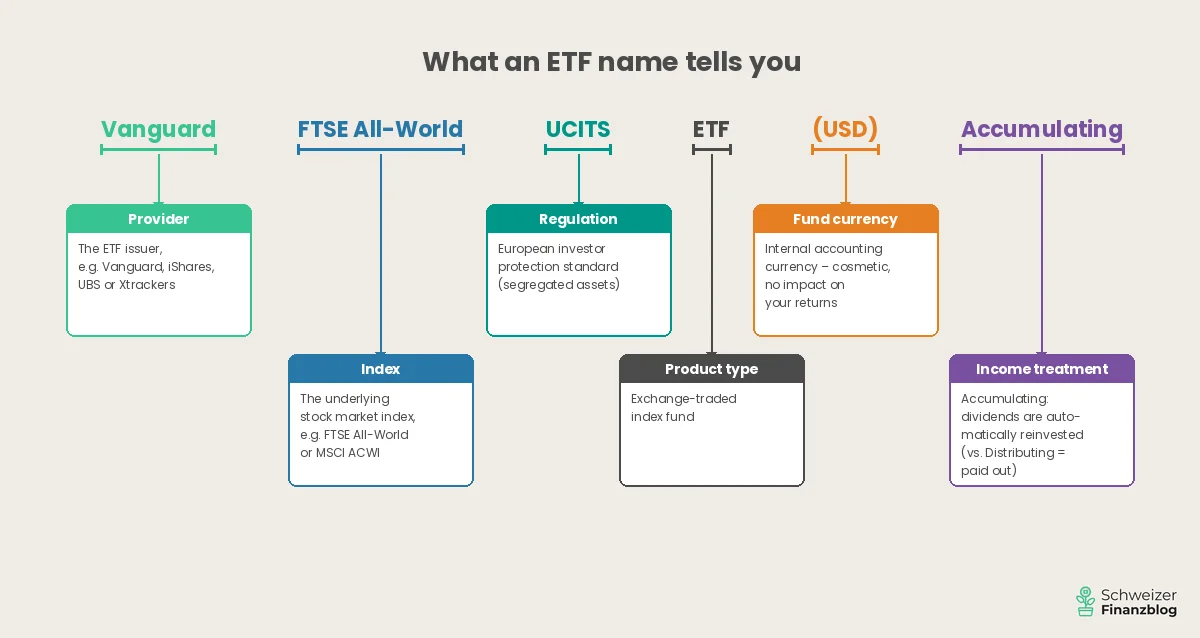
You’ll find a detailed overview of all common abbreviations in our article Understanding ETF abbreviations: 1C, UCITS, MSCI & Co. explained simply.
The currency question
Currency is a topic that regularly raises questions in our community – understandably so, because there are no fewer than three different currency levels:
The fund currency is the ETF’s accounting currency. It often appears in the name (e.g. “USD” or “CHF”). The fund currency is cosmetic: whether the ETF calculates internally in USD or CHF makes no difference to your return. There is one practical difference with distributing ETFs, however: there, the fund currency determines the currency in which dividends are paid out.
The trading currency is the currency in which you buy and sell the ETF on the stock exchange. Many ETFs can be traded on SIX in both CHF and USD. If you buy in CHF, you save yourself the currency exchange fees at your broker.
The security currency is the currency in which the individual shares in the ETF are quoted – US dollars for Apple, euros for ASML, yen for Toyota. You can’t influence this level, and this is exactly where the much-discussed currency risk lies: if the dollar loses value against the franc, the franc value of your US positions falls – even if the share prices in dollars stay stable. Important: this risk is linked exclusively to the security currency, not to the fund or trading currency.
Why currency hedging is unnecessary
Some ETFs offer currency hedging. That sounds like less risk, but it comes at a price: in addition to an often higher TER, there are implicit costs resulting from the interest rate differential between the currencies. For the franc against the dollar, these costs can add up considerably over the years.
For people with a long-term investment horizon, currency hedging generally doesn’t make sense. Experience shows that over periods of ten years or more, currency fluctuations largely even out. You pay the hedging costs every year, however – whether the franc rises, falls or moves sideways.
Our advice: skip currency hedging and save yourself the costs.
Distributing or accumulating?
When it comes to what happens to the income, you have two options:
Distributing ETFs regularly pay out the dividends they collect to your account – typically quarterly or half-yearly. You see the money come in and can decide freely what to do with it.
Accumulating ETFs automatically reinvest the dividends in the fund. The money stays in the ETF and keeps working straight away. You don’t see any payment come in, but the ETF’s price rises accordingly.
For building wealth over the long term, we prefer accumulating ETFs. The reason: automatic reinvestment makes optimal use of the compound interest effect – without you having to do anything. You also save the transaction costs that arise when you reinvest distributions manually.
Distributing ETFs can still make perfect sense, though – for example if you want regular income or want to use the distributions specifically for rebalancing (see Lesson 5).
In Switzerland, the choice makes no difference for tax purposes: dividends are subject to income tax in both cases – regardless of whether they are paid out or reinvested.
Investing sustainably with ETFs
If sustainability matters to you when investing, the ESG aspect (environmental, social, governance) also plays a role in the question “which ETF is right for me?”. There is now a growing range of ETFs that screen companies according to environmental, social and corporate ethics standards.
However, the ESG market is hard to navigate: there is no uniform definition of “sustainable”, and the differences between providers are considerable. Some ESG ETFs only exclude the most obvious offenders (e.g. arms manufacturers, coal), while others screen much more strictly and noticeably shrink the investment universe – with corresponding effects on diversification.
In our guide, we focus on standard ETFs without ESG filters, as these are more broadly diversified and usually cheaper. If you’re interested in sustainable ETFs, you’ll find a detailed analysis in our article Green stocks: 40 ETFs compared.
Which ETF is right for me?
Let’s sum up. If you want to choose an ETF that fits your global portfolio, these are the points that count most:
- Index first: choose a broadly diversified, market-cap-weighted equity index. For most investors, a single global ETF is the best solution.
- Keep costs low: look for a TER of no more than 0.25% and a tracking difference as close to zero as possible – or even negative.
- Size matters: a fund size of CHF 500 million or more provides security and liquidity.
- Physical replication: avoid synthetic ETFs.
- No currency hedging: in the long run, hedged products cost more than they deliver.
- Don’t mix index providers: either MSCI or FTSE – consistently.
This gives you the tools to find the right ETF in the huge range on SIX. In our detailed ETF comparison Best ETFs in Switzerland and globally, we did exactly that: in a strict, multi-stage selection process, we combed through the entire range and picked the best products.
– Partner offers –
Still looking for the right financial solution? Our recommendations – with attractive sign-up bonuses.
– – – – –
Conclusion
Choosing the ETF that’s right for you is no rocket science – as long as you know what matters. The index determines where your money goes; the product criteria make sure as little of it as possible gets lost along the way. And for the simplest option, a single, broadly diversified ETF covering the whole world is enough.
In Lesson 8 things get practical: we show you step by step how to buy your first ETF through an online broker – from opening a securities account to placing your first order.
You can find an overview of all the lessons here: Learn to invest – in eight lessons.
You might also be interested in

Updates
15 June 2026: Article adjusted in places.
24 April 2026: Article completely revised and updated.
Disclaimer
Disclaimer: Investing involves the risk of loss. You have to decide for yourself whether or not you want to bear these risks.
Errors excepted: We have written this article on choosing the right ETF to the best of our knowledge and belief. Our aim is to give you, as a private investor, information on finance that is as objective and meaningful as possible. If we have nevertheless made mistakes, overlooked important aspects and/or if information is no longer up to date, we would be grateful if you let us know.
About the authors
Stefan Huser
Stefan has been investing in the stock market himself since 2015. He has been shaped by Markowitz’s portfolio theory and Gerd Kommer’s book “Souverän investieren”. He follows a core-satellite strategy: a global equity portfolio of ETFs forms the core, complemented by alternative investments. At the blog, he mainly takes care of the writing. Stefan lives with his family in Zurich and is interested in literature, photography and financial freedom.
Antun Brcina
Antun (“Toni”) has been investing in the stock market since 2015. Financially, he has been particularly inspired by Gerd Kommer’s book “Souverän investieren” and the Fama-French five-factor model. His money is invested in a broadly diversified, long-term global equity portfolio of ETFs. At the blog, he mainly works on the calculators and the code. Toni lives with his family in the Zurich area and is interested in sports, technology and entrepreneurship.

24 Comments
Hallo zusammen,
zuerst einmal vielen Dank für eure transparenten und gut recherchierten Artikel!
Ich bin Auslandschweizer (DE) und überlege mir, ob ich mein zZ. in der CH aktiv verwaltetes Depot in ein passives Depot mit ETFs umwandle. Gründe dafür:
– Aktiv verwaltet bedeutet hohe Steuern, da bspw. in DE auch Verkäufe besteuert werden und nicht nur die Renditen.
– Viel Kosten für Steuererklärungen, -auszüge, Doppelbesteuerung etc.
In DE haben wir bereits ein passives Depot und haben gute Erfahrungen damit gemacht. Nun ist meine Frage:
– Ist es “besser”, sich in der CH ein passives Depot z.B. bei Swisspquote aufzubauen und keinen Währungsumtausch zu machen bzw. weiterhin im CHFr. inverstiert zu bleiben, mit weniger Inflation, weniger Währungsschwankungen ODER
– den Währungsumtausch in EUR zu vollziehen, an deutschen Börsen die ETFs kaufen und das Depot in DE aufzubauen – was steuerlich am einfachsten wäre, aber eben mehr Inflation, weniger Stabilität, aber ev. bessere Kaufbedingungen an den dt. Börsen bietet.
– oder spielt es keine oder kaum eine Rolle, da das Kapital einvestiert ist?
Ich bin in diesen Fragen etwas überfragt und freue mich auf Antworten. Beste Grüße,
Heinrich
Hoi Heinrich
Wenn du investiert bist, hängt das Währungsrisiko primär mit der Herkunft der in diesem Fonds befindlichen Unternehmungen zusammen und nicht damit, ob du deinen ETF in EUR oder CHF gekauft hast. Also wenn du beispielsweise in einen ETF investiert bist, der den MSCI World mit rund 70% US-Unternehmen abbildet, so besteht das Währungsrisiko zu einem grossen Teil im Verhältnis USD und deiner Referenzwährung, unabhängig davon, ob deine Handelswährung EUR oder CHF ist.
Beste Grüsse
SFB
Hmmm… man kann selbstverständlich auch zu sehr in die Details gehen, ohne, dass es vermutlich viel bringt. Jedoch bin ich der Meinung, dass mit wenigen (<3-5 Titeln) keine wirklich breite Diversifikation möglich ist; zu sehr gibt es m.E. dann trotzdem Klumpen (z.B. durch zu grossen USA Anteilen). Deshalb gefällt mir dieses Portfolio an ETF mit entsprechenden Portfolio-Anteilen gut und bin gespannt auf eure Meinungen (selbstverständlich erwarte ich keine Anlageempfehlungen, aber kritische Anmerkungen, Alternativvorschläge zur Titelauswahl etc. sind willkommen):
*Nordamerika (25%) – Vanguard FTSE Emerging Markets
*Europa (25%) – iShares Core MSCI Europe
*"Home Bias" (5%) – UBS ETF (CH) SPI Mid (CHF)
*Asien-Pazifik ohne Japan (10%) – Vanguard FTSE Developed Asia Pacific ex Japan
*Japan (5%) – iShares Core MSCI Japan IMI
*Schwellenländer (15%) – Vanguard FTSE Emerging Markets
*Immobilien ohne USA – (10%) Vanguard Global ex-US Real Estate ETF
*Immobilien USA (5%) – iShares US Property Yield
Es sei noch erwähnt, dass weder Courtagen noch Depotführungsgebühren für mich relevant sind, da ich über eine Konzernzugehörigkeit in den Genuss äusserst attraktiver Vorzugskonditionen komme (somit ist das Thema "Trading Bank" auch erledigt)
Freundliche Grüss, Guido
…das scheint uns eine sinnvolle Aufteilung zu sein. Jetzt benötigst du nur noch einen langen Anlagehorizont (>10 Jahre) und die nötige Portion Standfestigkeit bei künftigen Börsenturbulenzen… Viel Erfolg!
Danke. Das wünsche ich uns allen! 🙂
Vielen Dank für diesen wertvollen Artikel. Leider scheint mir bei eurer Entscheidungshilfe kein einziger nachhaltiger ETF dabei zu sein. Gibt es hier eurerseits auch Auswertungen? Ich denke, es handelt sich hierbei um ein wichtiges Kriterium.
Hoi Chelsea
Ja, es gibt unsererseits Auswertungen von nachhaltigen ETFs. Schau’ doch mal in den Artikel “Grüne Aktien: 40 ETFs im Vergleich” rein. Da wirst du bestimmt deine grünen Wunsch-ETFs finden:-)
Beste Grüsse
SFB
Hallo zusammen
Vielen Dank für eure hilfreichen Artikeln!
Ich versuche euren Hinweis am Anfang des Artikels besser zu verstehen, dass “ETFs auch an ausländischen Börsenplätzen erwerben, was jedoch steuerlich etwas aufwändiger sein kann.”
– Was bedeutet “steuerlich etwas aufwändiger sein kann” genau?
– Was sind Beispiele von Vor- und Nachteilen ETFs an der Schweizer Börse zu kaufen?
– Was sind Vor- und Nachteile ETFs an den ausländischen Börsen z.B. Euronext Amsterdam (EAM) und Xetra (XET) im Portfolio zu haben?
Wie würdet ihr die Fragen beantworten um die Auswahl des Börsenplatzes besser verstehen zu können.
Besten Dank und liebe Grüsse
Hoi Larissa
Vielen Dank für deine interessante Mitteilung. Vorweg: In Bälde werden wir das Steuerthema in einem separaten Artikel vertiefen. Zu deinen Fragen:
– Es handelt sich hier um eine Kann-Formulierung und selbst diese scheint uns aus heutiger Sicht zu stark. Steuerlicher Mehraufwand könnte allenfalls resultieren, wenn du an einer Fremdbörse einen ETF kaufst, welcher die Steuerverwaltung (noch) nicht gelistet hat. In diesem Fall ist eine manuelle Eingabe des ETF-Produkts in der Steuererklärung nötig. (Normalerweise ist es ja so, dass die steuerrelevanten ETF-Daten mit Eingabe der Valoren-Nr. automatisch ausgefüllt werden.) Steuerlicher Mehraufwand ist weniger mit der Wahl des Börsenplatzes verbunden, sondern hängt eher mit dem Domizil des ETF zusammen. So werden beispielsweise bei US-ETFs ein Teil der Dividende zurückbehalten, welche mittels Ausfüllen des separatem Steuerformular DA-1 teilweise wieder zurückgefordert werden kann. Voraussetzung für solche Rückerstattungen der Quellensteuern sind Doppelbesteuerungsabkommen zwischen der Schweiz und dem entsprechenden ausländischen Staat.
– Vorteile Heimbörse: Handelswährung bei vielen Produkten (insbes. bei Anbieter Vanguard) in CHF möglich, womit die Wechselgebühren entfallen; oft attraktivere Gebühren (z.B. tiefere Courtagen bei Postfinance, keine jährliche Fremdbörsengebühr bei DEGIRO); Nachteil Heimbörse: oft geringeres Handelsvolumen und deshalb grösserer Spread; ETF-Angebot ist zwar mittlerweile umfassend, aber dennoch beschränkt; aktuell keine Gratis-ETFs bei DEGIRO
– Vorteile ausländische Börsen: Vgl. Punkt oben mit “umgekehrten Vorzeichen”;-)
Beste Grüsse
SFB
An dieser Stelle einfach einmal ein Danke, dass ihr euch die Zeit nehmt verständlich und ausführlich zu antworten.
BG, Larissa
Hallo zusammen
Wie sieht es mit den Steuern aus, wenn man in einen ETF mit Domizil in Irland investiert?
Werden die Steuern automatisch beim Kauf abgezogen? (zb bei Swissquote)
Habit ihr einen Artikel dazu? Habe auf die schnelle nichts gefunden. 🙂
Besten Dank & Liebe Grüsse
Guten Tag Lars
Gute Idee mit dem Steuerartikel, der aktuell in unserer Sammlung noch fehlt. Steuerlich sind die in der Schweiz stark verbreiteten ETFs mit Domizil Irland sehr “pflegeleicht”. So sind Verrechnungssteuer und Rückforderungsanträge anderer Art, kein Thema. Unabhängig des Domizils des ETFs gilt in der Schweiz hingegen:
1) Dividenden, unabhängig davon, ob es sich um einen ausschüttenden oder thesaurierenden ETF handelt, sind als Einkommen zu versteuern.
2) Das in ETFs angelegte Vermögen unterliegt der Vermögenssteuer.
3) Realisierte Kapitalgewinne aus ETF-Verkäufen sind steuerfrei.
Beste Grüsse
SFB
Hallo liebes Finanzblog-Team
Vielen Dank für eure hilfreichen Artikel.
Ich habe auch eine Frage…
Was hält ihr von folgenden ETF?
CSIF FTSE EPRA/NAREIT Developed Green Blue
ISIN: IE00BMDX0K95
Er ist ein mittelgrosser ETF und noch jung, da er erst im 2020 aufgelegt wurde.
Was mich verunsichert, an keinem Tag an dem ich geschaut habe, wurde er an der Schweizer Börse SIX gehandelt. Da ich bei Degiro keine Gebühr zahlen muss, wenn ich an der SWX anstelle der Xetra kaufe, bevorzuge ich diesen eigentlich an der SIX in USD zu kaufen anstelle in Euro an der Xetra.
Was ist eure Meinung dazu? Und allgemein zu diesem ETF?
Ich wäre mega dankbar für eine Antwort.
Liebe Grüsse
Hoi Reto
Hierbei handelt es sich um einen Branchen-ETF “Immobilien” mit Nachhaltigkeitsfokus und breit diversifiziert über diverse Regionen der entwickelten Welt und mit einem Gesamtnettovermögen von rund 170 Mio. USD. Die TER beträgt gemäss CS Factsheet 0.25%, was wir fair finden. (Interessanter wäre dann die Tracking Difference, wofür dieser ETF aber noch zu jung ist.) Als Beimischung spricht unseres Erachtens nicht viel gegen diesen ETF. Einzig das von dir erwähnte, offenbar geringe Handelsvolumen kann dazu führen, dass der Spread etwas grösser ist und somit die Transaktionskurse etwas weniger vorteilhaft sind. (Durch die Market Makers kommt aber auf alle Fälle eine Transaktion zustande.)
Wenn du ganz vorsichtig sein möchtest, dann gibst du diesem ETF noch zwei, drei Jahre Zeit, bevor du in ihn investierst. Wenn dich dieser ETF aber grundsätzlich überzeugt und du für dich keine vergleichbaren Alternativen auf dem Markt siehst, dann ist womöglich jetzt der richtige Zeitpunkt für ein Investment – vorzugsweise in Tranchen. Ob SIX oder Xetra ist für uns nicht matchentscheidend – hier gilt es nach deiner individuellen Präferenz abzuwägen: USD vs. EUR, unterschiedliche Handelsvolumen, (moderate) DEGIRO-Gebühren für ausländische Börsenplätze etc.
Beste Grüsse SFB
Hallo
Super hilfreicher Artikel. Danke.
Ich habe eine Frage u d zwar möchte ich den FTSE EPRA/NAREIT Index besparen. Ich habe zwei ETF‘s zur Auswahl, ein irischer (ausschüttend) oder Luxemburg (thesaurierend). Ich möchte via Degiro Custody eigentlich nur thesaurierende ETF‘s besparen, bin mir aber nicht sicher, ob ich steuerliche Nachteile beim ETF mit Domizil Luxemburg habe.
Ich bedanke mich sehr für eine Antwort.
Liebe Grüsse
Hoi Timo
Beide Domizile (IE + LU) stehen im Ruf, steuerlich für ETF-Anleger sehr attraktiv zu sein. Es hängt letztlich von der Region der Aktien ab. USA: Vorteile IE; Europa und Schwellenländer = etwa gleich attraktiv (Quelle: Hinder Asset Management)
Beste Grüsse SFB
Hallo zusammen
Vielen Dank für diesen tollen, ausführlichen Artikel.
Ihr habt bezgl. Diversifikation noch Rohstoffe und Immobilien erwähnt.
Gibt es hierzu einen weiteren Beitrag? Ich bin seit Tagen am Überlegen ob ich je ein ETF auf Immobilien und ROhstoffe in mein Portfolio zur Diversifikation aufnehmen soll…
Danke für eine Antwort und liebe Grüsse
Hoi Eliana
Ja, zum Immobilien-Thema kommt sicher noch ein Artikel. Immobilien-ETFs sind als Beimischung sicher eine prüfenswerte Option. Die Ausschüttungsquote ist oft überdurchschnittlich hoch, die Kursentwicklung eher moderat. In Rohstoffe sind wir nicht investiert und haben dies auch nicht vor.
Beste Grüsse SFB
Hallo zusammen,
ich habe eine kurze Frage hinsichtlich eines ETF, dessen Fondwährung USD ist. Macht das einen Unterschied, ob ich in über einen Sekundärmarkt in USD oder EUR investiere? Bsp. ich möchte 5000 CHF in den Fonds investieren und kann über die Xetra in EUR oder über die London Exchange in USD investieren.
Danke schonmal.
Toller Artikel. Vielen Dank!
Ich habe ein Konto bei Degiro eröffnet und in den einzigen MSCI World investiert der dort gratis gehandelt werden kann. Dieser wird in Euro geführt. Nun möchte ich gerne noch einen Emerging Markets ETF dazu nehmen.
Beim Emerging Marktes ETF werde ich wohl eher einen wählen bei dessen Handel Gebühren anfallen, da mich jener der gratis gehandelt werden kann nicht sonderlich überzeugt (DE000ETFL342).
Was ich mich generell frage ist: Macht es Sinn gleiche ETF’s in verschiedenen Währungen zu haben um sich gegen Kursschwankungen abzusichern? Oder würdet ihr sowieso immer einen ETF wählen, der in CHF gehandelt wird um Wechselgebühren zu sparen?
kann es sein, dass Vanguard nur ausschüttende ETFs anbietet? Bin auf der Suche nach zwei ETF, welche thesaurierend sind.
ja das ist korrekt (vgl. auch Homepage von Vanguard Schweiz).
LG SFB
Super, danke für eure kurze Einführung, genau was ich gesucht habe!
Frage: Ist das Investieren als Schweizer in zwei ETF, die beide in USD gehandelt sind, nicht ziemlich risikoreich?
Fragen eines Noobs:
– gibt es ähnliche Indizes, die auf CHF basieren? Würdet ihr das empfehlen? Weshalb ja, weshalb nicht?
Hoi Simon
Nein, grundsätzlich erachten wir ETFs, welche in USD gehandelt werden bezüglich des Währungsrisikos als nicht sehr risikoreich. Denn die Handelswährung ist diesbezüglich nicht entscheidend. Vgl. hier auch unseren Artikel ETFs: Die Revolution der Geldanlage, Kapitel 7.
Falls du in ETFs investieren möchtest, deren Handelswährung CHF ist, so könnte der Anbieter Vanguard eine prüfenswerte Option sein. ETF-Pionier Vanguard bietet nicht nur praktisch all seine ETF-Produkte in CHF an, sondern ist auch bekannt für seine fairen Gebühren.
Beste Grüsse
SFB