
 Newsletter
Once almost the only game in town, now surrounded by competition: in this detailed review, we share our Swissquote experience with you. You’ll find out where we see the strengths and weaknesses of Switzerland’s largest online broker, and for which investors switching is particularly worthwhile – and for which it isn’t. Finally, Head of Marketing Romain Le Baud explains the particular challenges Swissquote is currently facing and how the company is positioning itself in an increasingly dynamic market.

In a nutshell
Founded in 1996, the Swiss online bank Swissquote combines security, innovation and a broad product range. If you want trading, banking and saving all in one place, you’ll find one of the most comprehensive solutions on the market here. The key points at a glance:
- Swiss banking license & deposit insurance: Swissquote is regulated in Switzerland and offers protection up to CHF 100,000.
- Comprehensive range: Over 3 million tradable products are available, including a large selection of ETFs on international exchanges.
- Capped fees: ETF trades in the “ETF Leaders” on the Swiss stock exchange SIX cost CHF 3 to a maximum of CHF 9 depending on order size – whether you trade CHF 1,500 or CHF 150,000.
- Automatic ETF savings plan: Regular investments are possible for a fee from CHF 3 per execution – including fractional trading.
- Banking & multi-currency account: The integrated account lets you make payments in several currencies and includes a free virtual debit card.
- Modern platform & app: The trading interface is intuitive and individually configurable – ideal for mobile use, too.
- Foreign currencies & FX costs: The flat currency exchange fee is 0.95%; foreign currency accounts let you reduce or avoid these costs.
- Custody fees with a cap: Depending on your portfolio value, you pay between CHF 80 and CHF 200 per year.
- Invest Easy (optional): The automated asset management is convenient but comes with higher costs.
- Securities lending (optional): Lending out your own securities can earn you passive additional income.
- Support & education: Free support (DE / EN / FR) is available by phone, email or chat, complemented by online courses for beginners.
Our Swissquote experience shows: If you’re looking for an established Swiss platform with a broad range and fair – though not the cheapest – conditions, Swissquote is a strong choice, all in one place.
🎁With the Swissquote promo code MKT_SFB you get CHF 100 in trading credits when you open an account.
Contents
- Swissquote promo code MKT_SFB
- Company history
- Product range
- Security
- Account opening
- App and platform
- Prices
- Securities lending as an additional source of income
- Support
- Suitability
- Interview with Romain Le Baud, Head of Marketing at Swissquote
- Conclusion on our Swissquote experience
- You might also be interested in
- Updates
- Disclaimer
Swissquote promo code MKT_SFB
If Swissquote’s offer appeals to you, enter the promo code MKT_SFB when you open your account to get a welcome bonus in the form of trading credits (fee waiver on trades). You’ll also be supporting our blog.
– Partner offer –
– – – – –
Company history
“We want to be the world’s most advanced and intuitive online bank. Through innovation and technology, we challenge traditional conventions and rethink them.” That is Swissquote’s vision.
Since its founding in 1996, Swissquote’s company history has been shaped by innovation and growth. The latter has come not only organically but also through frequent acquisitions.
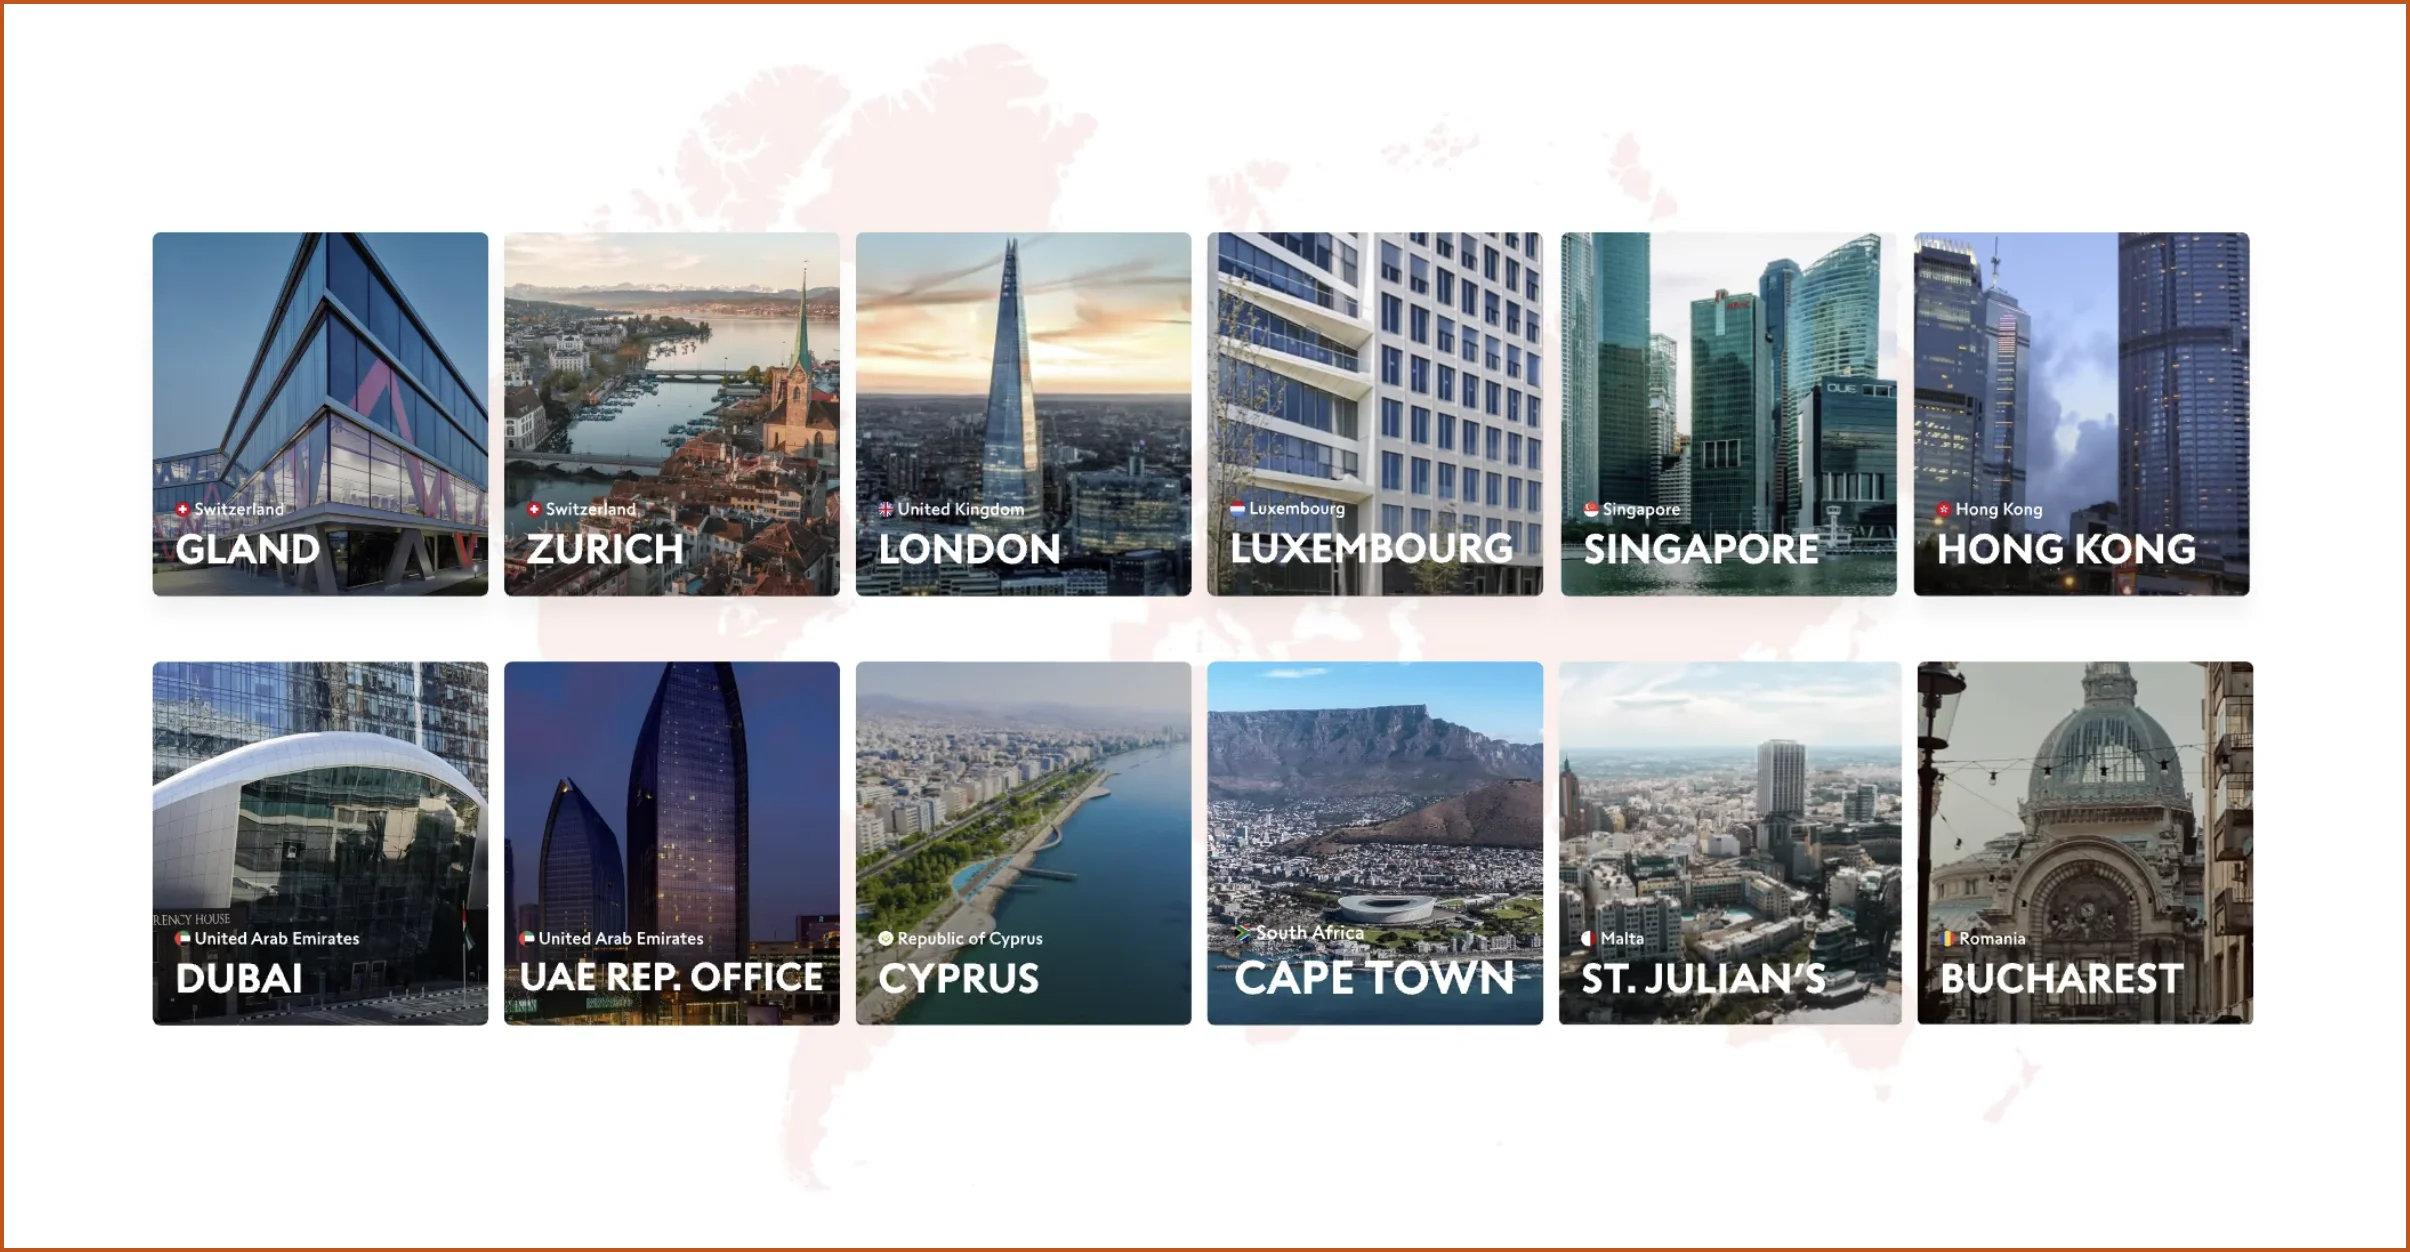
Today, Swissquote has over 700,000 clients and is present in 12 locations around the globe – a clear sign of the bank’s international focus and its growing importance in the global online trading market.
Below, we focus on the milestones that are particularly relevant for private investors.
- 1996: Swissquote is launched
- 2000: Stock exchange listing (symbol: SQN)
- 2001: Swiss banking license obtained
- 2006: Online trading via smartphone
- 2008: Savings accounts introduced
- 2014: Strategic partnership with PostFinance
- 2018: Multi-currency credit card introduced
- 2021: Launch of the neobank Yuh (review) together with PostFinance
- 2023: Launch of a multi-currency debit card and of “Invest Easy” for automated investing in an entire portfolio based on your own risk profile
- 2024: Savings plans introduced from CHF 3
- 2025: Full takeover of the neobank Yuh
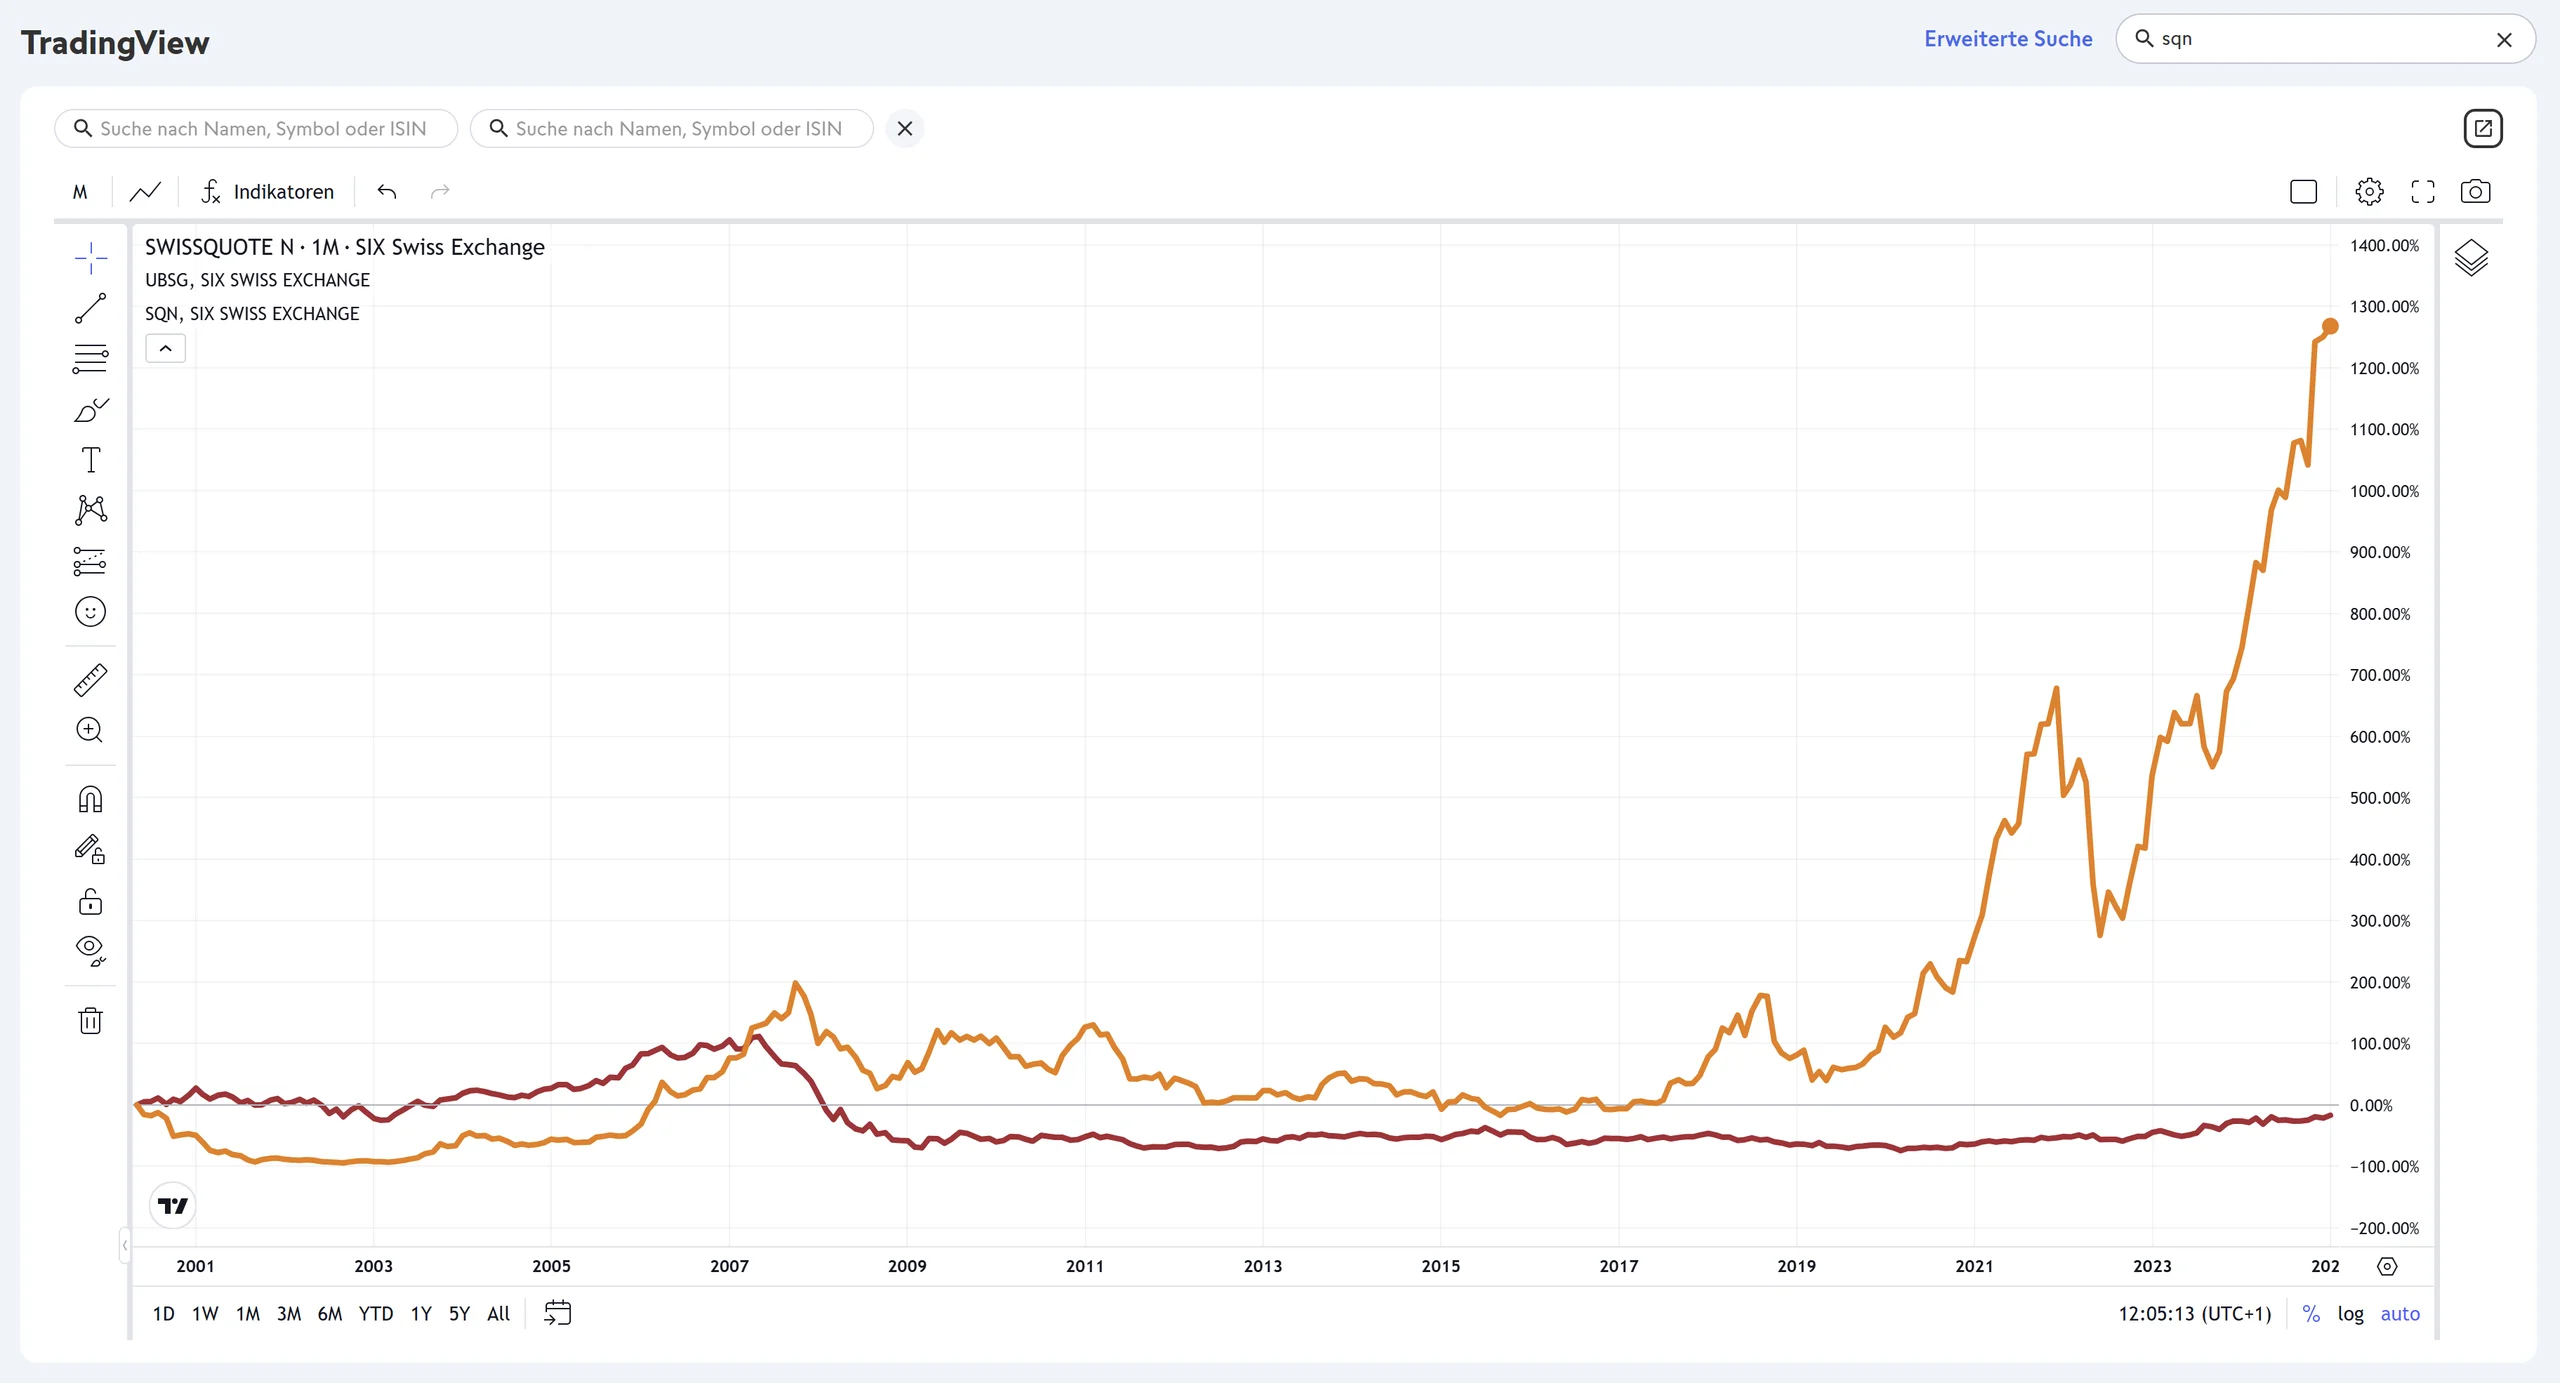
The bank’s pleasing share price performance also shows that Swissquote’s dynamic business model works.
Product range
We consider Swissquote’s offering very comprehensive. In total, Swissquote offers over 3 million products, including a wealth of ETFs, tradable on over 50 exchanges around the world.
Probably the best known is electronic trading in securities such as shares, investment funds (incl. ETFs), options/warrants and bonds, along with account and custody account management for private and corporate clients as well as asset managers. How competitive Swissquote is in its core business is also shown by the fact that the large PostFinance has handled its e-trading exclusively via Swissquote’s platform since 2015.
What’s more, back in 2017 Swissquote was the first online bank to enable trading in the cryptocurrencies Bitcoin, Bitcoin Cash, Ether, Litecoin and Ripple.
Swissquote also offers other traditional banking services such as mortgages, Lombard loans, savings and multi-currency accounts and various payment cards, including the free, purely virtual “Light” debit card.
Finally, extensive analysis tools and an integrated robo-advisory service, “Invest Easy”, round off the broad product range.
Focus on equity ETFs: Swissquote thus offers a versatile multi-asset platform for a wide variety of investor groups. As you know, we consider a passive, low-cost, broadly diversified buy-and-hold investment strategy focused on the equity asset class to be the most promising in the long run. We are also convinced that such a strategy is best implemented with ETFs. That’s why, in this review of our Swissquote experience, we focused on equity ETFs.
Security
In its more than 30-year history, Swissquote has proven to be crisis-resistant. Beyond that, the following arguments are likely to matter in particular to security-conscious investors:
- Regulated by FINMA: Swissquote holds a Swiss banking license and is therefore subject to the requirements of FINMA (Swiss Financial Market Supervisory Authority).
- Swiss deposit insurance: As a member of the Swiss Bankers Association (SBA), Swissquote has signed the depositor protection agreement. This agreement guarantees individual bank creditors (depositors) rapid protection in the event of a bank’s bankruptcy, up to a cash balance of CHF 100,000.
- Segregated custody of securities: Securities such as ETFs are fully protected if Swissquote Bank Ltd goes bankrupt, as they are held at the respective custodians in the client’s name.
- High security standards for account login: 3-level authentication using a username, password and password supplement (optional). According to the support team, these are still printed on laminated paper and sent by post, just like in the early days – which surprised us a little coming from a “digital powerhouse”, which Swissquote undoubtedly is. On the plus side: after your first login, you can choose the purely digital “Tan” option, a one-time numeric code sent to your mobile phone by text message.
Account opening
Opening an account is done entirely digitally in just a few minutes, including by scanning documents. Swissquote does without video recordings for identity verification. Alternatively, Swissquote offers account opening in person at its lounge in Zurich. Either way, account opening is divided into the following three parts:
- Personal data: Here you enter personal information such as marital status, income and assets, and type MKT_SFB into the “Promo code” field to secure trading credits worth CHF 100 (special offer).
- Login details: Here you receive your username and password.
- Completing the application: Here you can check your details once more and sign the application digitally.
App and platform
As you’d expect from a modern online broker, Swissquote offers both web-based access via desktop and an app for mobile devices.
While Swissquote used to present itself in a rather sober, uninviting look, the new design impresses with a clear structure and a modern appearance.
The “Bank” menu shows your cash balances and account transactions on the three standard accounts in CHF, EUR and USD. You also get an overview of your card transactions.
The actual trading platform is in the “Trade” menu, which you can customize: in addition to the positions you already hold, you can create a personal watchlist of securities that matter to you. That way, you always keep an eye on price movements, market data and potential buying candidates.

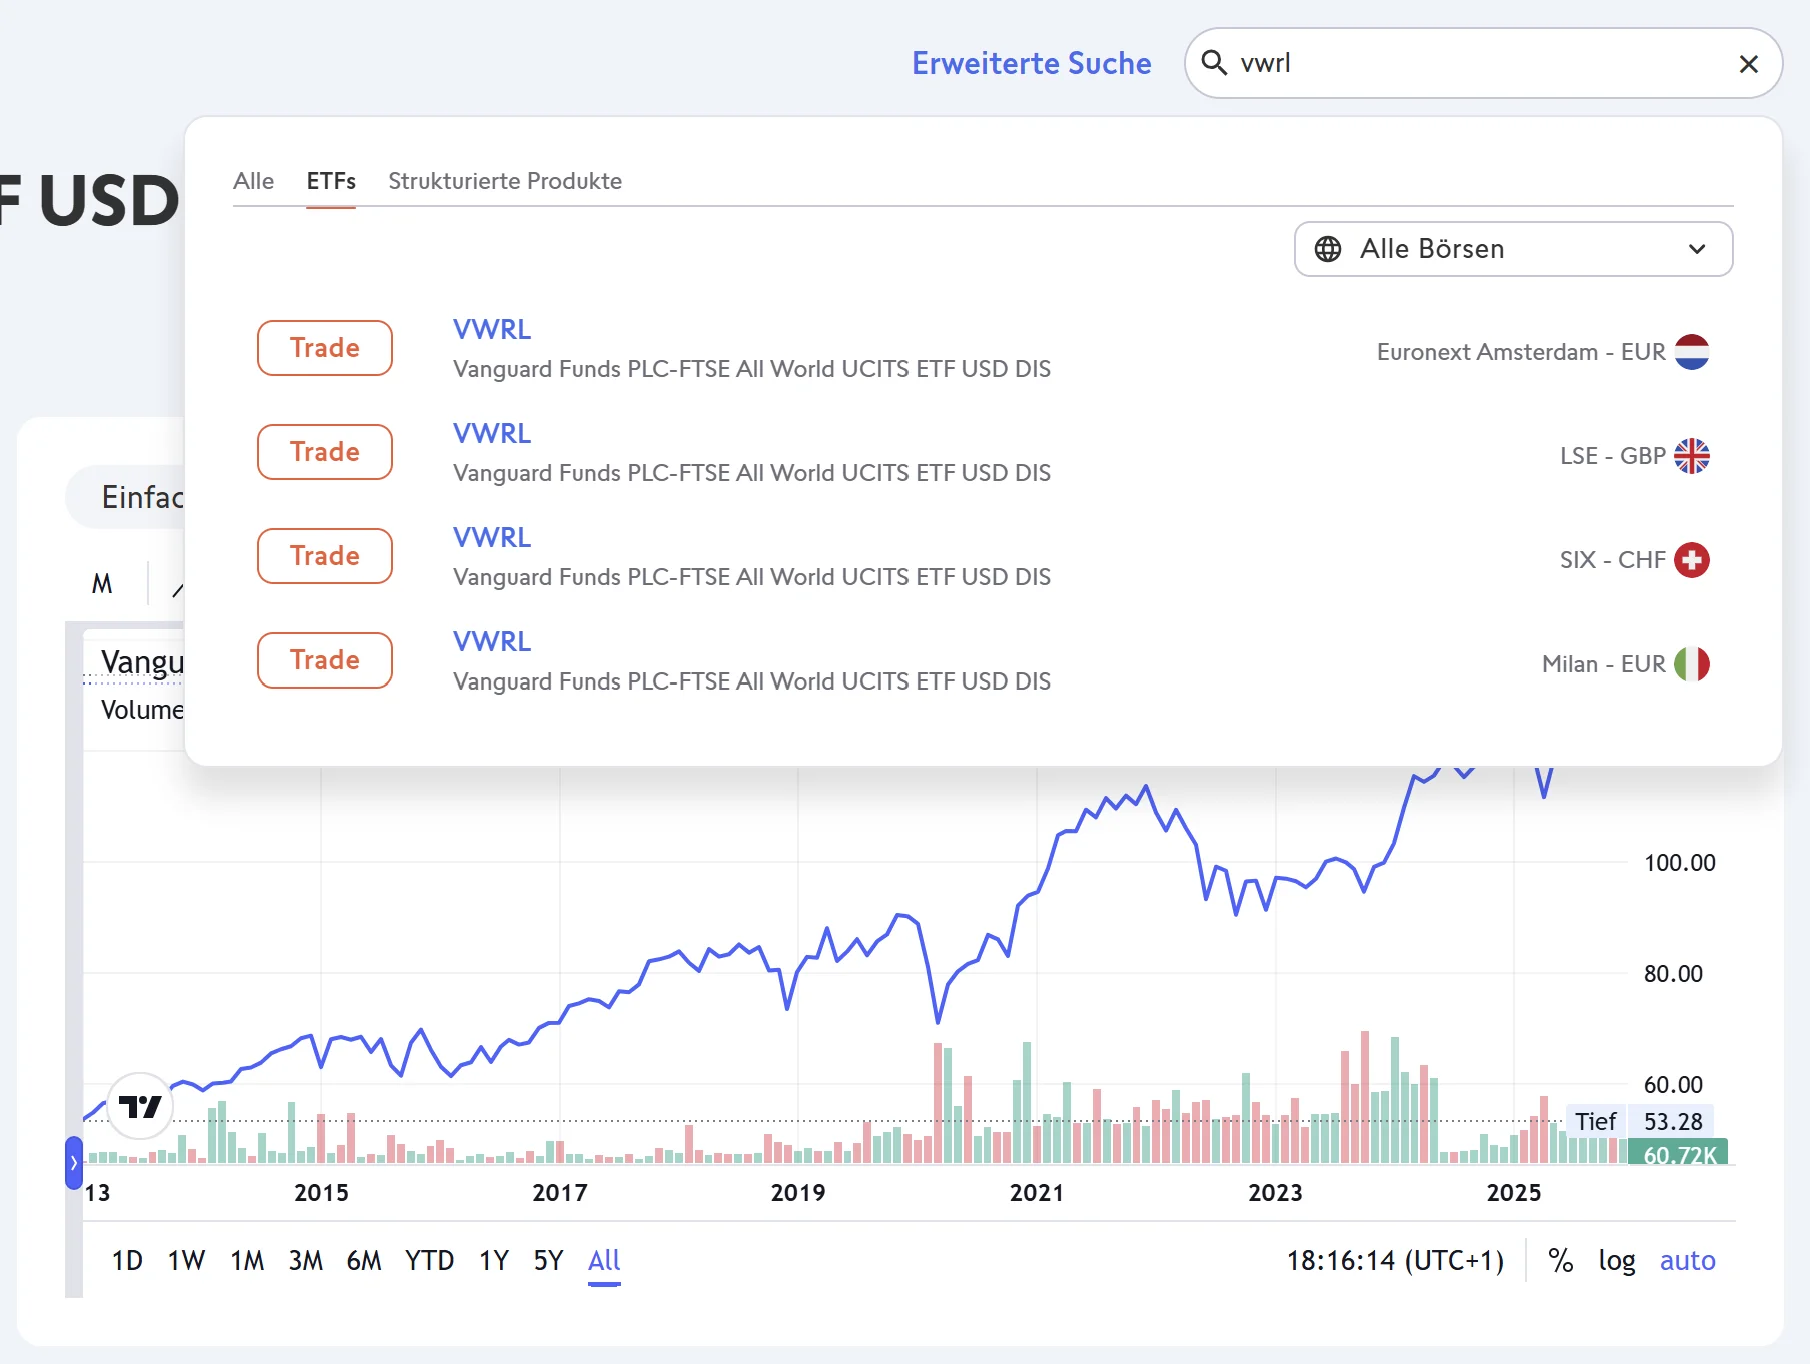
Swissquote lets you buy securities on virtually all major stock exchanges in the world. Well-known ETFs, such as the Vanguard FTSE All-World in the image below, are often traded on different exchanges and in several currencies. The country flags indicate where each exchange is based and help you choose the security you want.
Prices
Let’s get this out of the way: Swissquote can’t compete on price with foreign providers such as Interactive Brokers or DEGIRO. Within Switzerland, however, Swissquote stands out with genuinely attractive fees.
Fee highlights: ETF Leaders for a maximum of CHF 9, savings plans from CHF 3
We were particularly impressed by the fee model for the “ETF Leaders”, a Swissquote selection of more than 1,000 ETFs. On the Swiss stock exchange SIX, you pay CHF 3 to a maximum of CHF 9 per trade depending on order size – and the cap also applies to large amounts. So whether you trade CHF 2,000, CHF 20,000 or CHF 200,000, the commission stays at CHF 9.
If you want to invest smaller amounts regularly, Swissquote also offers savings plans – with commissions from CHF 3 per execution.
Custody fees
Custody fees are charged regardless of your trading activity. Swissquote charges them quarterly according to a tiered rate, and cash does not count towards the calculation basis. Per year, you pay between CHF 80 and a maximum of CHF 200. If your portfolio exceeds CHF 1 million, an additional 0.0075% per quarter applies.
The following comparison shows how strongly a cost cap limits fees on larger portfolios:
| Provider | 100’000 CHF | 500’000 CHF | 1 Mio. CHF |
|---|---|---|---|
| Swissquote | 100 (0,10%) | 200 (0,04%; Cap) | 200 (0,02%; Cap) |
| Migros Bank | 230 (0,23%) | 1’150 (0,23%) | 2’100 (0,21%) |
| Zürcher Kantonalbank | 300 (0,30%) | 1’500 (0,30%) | 3’000 (0,30%) |
| UBS | 350 (0,35%) | 1’750 (0,35%) | 3’500 (0,35%) |
Brokerage fees (transaction fees)
What stands out positively for us in this important fee item is the capped rate for the “ETF Leaders”. The brokerage fee depends on the order volume: CHF 3 up to CHF 500, CHF 5 up to CHF 1,000 and, from CHF 1,000, a flat rate of CHF 9 – no matter how much larger your order is. Swissquote calls the ETFs that benefit from this low rate “ETF Leaders”.
And these are by no means unattractive leftovers from unknown providers. On the contrary: this category includes hundreds of ETFs from the most renowned providers such as Vanguard or iShares (BlackRock). What they have in common: they are all traded on the Swiss stock exchange SIX.
Good news: our research also showed that all the winning ETFs we selected in our article Best ETFs for Switzerland and global through a strict, multi-stage selection process benefit from this low flat rate.
Here you can find all the ETFs that Swissquote offers at the “ETF Leaders” special rate.
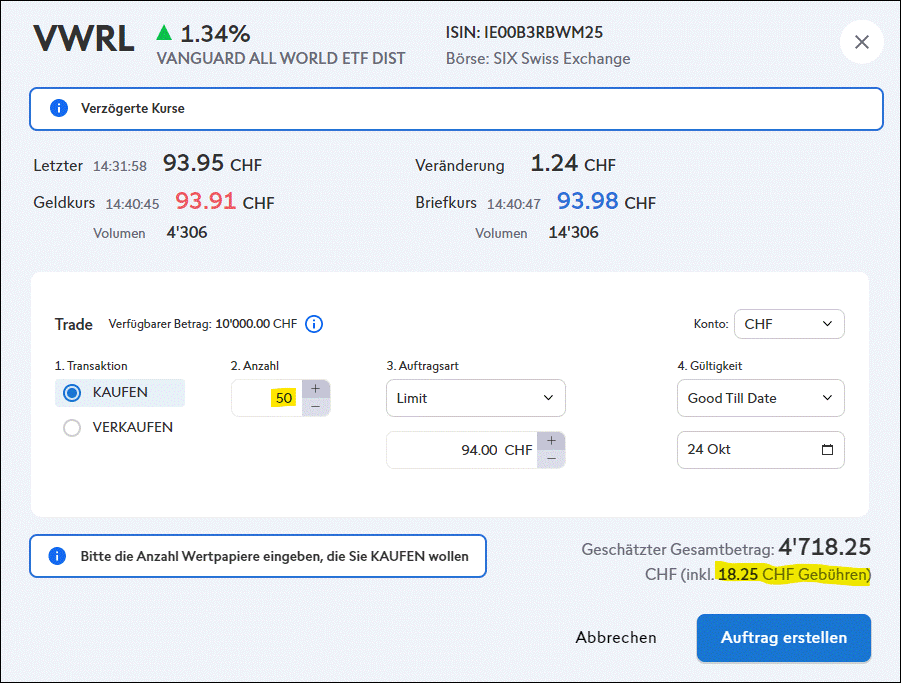
Back to costs: buying 50 units of the “ETF Leaders” Vanguard All World ETF (VWRL) at a unit price of CHF 94.00 cost us CHF 4,718.25, including fees of CHF 18.25. Below, we briefly break down these transaction-related costs:
| Swissquote brokerage fee: | 9.00 CHF |
| Stamp duty (0.15%): | 7.05 CHF |
| Exchange fees: | 2.20 CHF |
In other words, Swissquote’s own fees make up only about half of the costs of our test trade; the other half goes to the federal government and the stock exchange.
If none of these low-cost ETFs appeal to you, you’ll pay significantly higher brokerage fees on transaction amounts from CHF 2,000, as Swissquote’s price overview for shares and ETFs below shows:
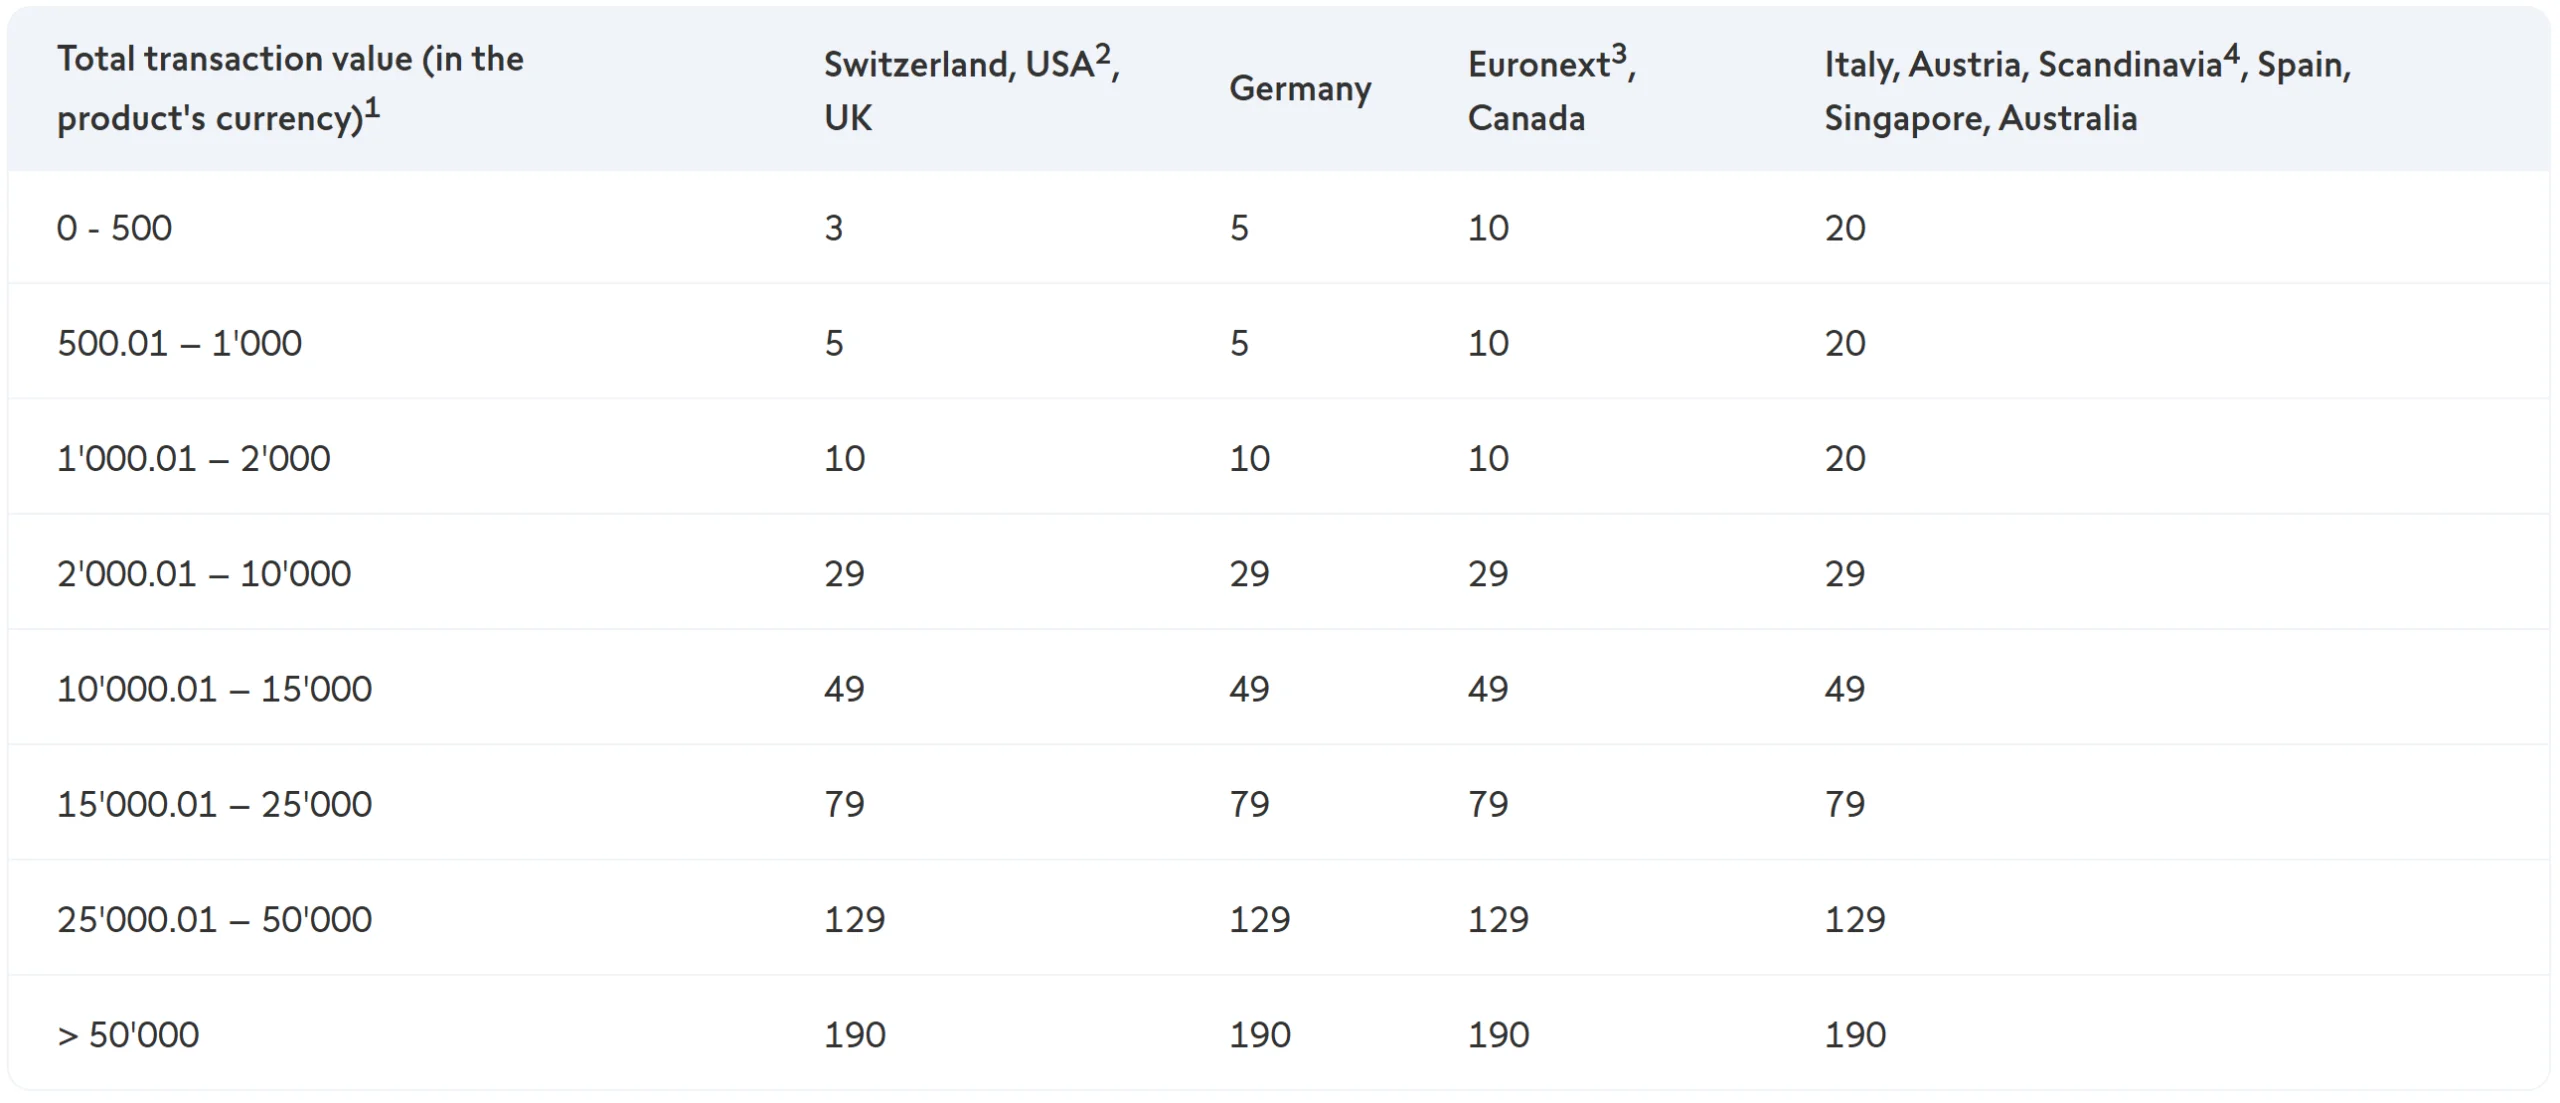
So it’s obvious: if you choose Swissquote as your broker and want to invest in ETFs, you should preferably go for “ETF Leaders” products with a brokerage fee of no more than CHF 9. The “normal” rates are reminiscent of Switzerland as a high-price island and are hardly an option for cost-conscious investors. With one exception: if you only invest smaller amounts of up to CHF 500 or CHF 1,000, for example regularly via a savings plan, the regular rates also come with only moderate fees of CHF 3 or CHF 5 respectively.
Stamp duty (transaction tax)
Since Swissquote is a Swiss broker, stamp duty is charged on every trade. It amounts to 0.075% for funds domiciled in Switzerland (recognizable by a Swiss ISIN starting with “CH…”) and 0.15% for funds domiciled abroad (foreign ISIN such as “IE…” for Ireland). You can find out more about the taxation of ETFs in our separate tax article ETF taxes in Switzerland: optimize your portfolio with these tax-saving tips.
Foreign currency fees
For currency exchange between major currencies – which, for Swissquote, include the Swiss franc, the euro, the US dollar, the British pound and the Japanese yen, among others – a fee of 0.95% applies. Higher rates apply to so-called minor currencies; you can find them here.
Swissquote lets you hold almost any number of foreign currency accounts. Foreign currency accounts are useful because they can help you save on the relatively high currency exchange fees. For example, if you already hold cash in EUR and want to invest in an ETF with EUR as its trading currency, you won’t pay any foreign currency fees. Incoming EUR transfers to your Swissquote trading account are also free of charge.
Account fees
At Swissquote, you can hold your cash in different currency accounts free of charge. Handy: when you open your account, you automatically get a CHF, a USD and a EUR bank account.
Transfer fees
Welcome, if overdue: since 1 January 2023, Swissquote no longer charges any fees for domestic payments. Previously, a flat fee of CHF 2 applied to outgoing transfers. For us, that was a no-go, which is why, when this article was first published, we advised against using Swissquote as your main bank. Now this option may be worth considering again for some investors. But watch out: if you regularly make international SEPA transfers in euros, you’ll still be charged fees of €2.
Costs for Lombard loans
If you’re willing to take more risk, you can leverage your investments with a securities-backed loan (Lombard loan). You can find Swissquote’s current interest rates here.
If Lombard loans are something you’re considering, it’s worth checking carefully what different providers offer. There are big differences in this niche market, as the following comparison shows.
| Provider | CHF | EUR | USD |
|---|---|---|---|
| DEGIRO | 2,5%* – 4% | 4,75%* – 6,25% | 5,25%* – 6,9% |
| Interactive Brokers | 1,5%** | 3,7%** | 5,13%** |
| Saxo Bank | 2%*** | 3,91%*** | 5,7%*** |
| Swissquote | 3% | 5,03% | 6,63% |
Fees for robo-advisory
If you want your entire portfolio – not just individual positions in a savings plan – to be managed automatically, Swissquote offers the optional “Invest Easy”. However, the relatively high total fees of up to 0.79% are likely to put off many private investors. The robo-advisors on our recommendations page show that it can be done much more cheaply.
Securities lending as an additional source of income
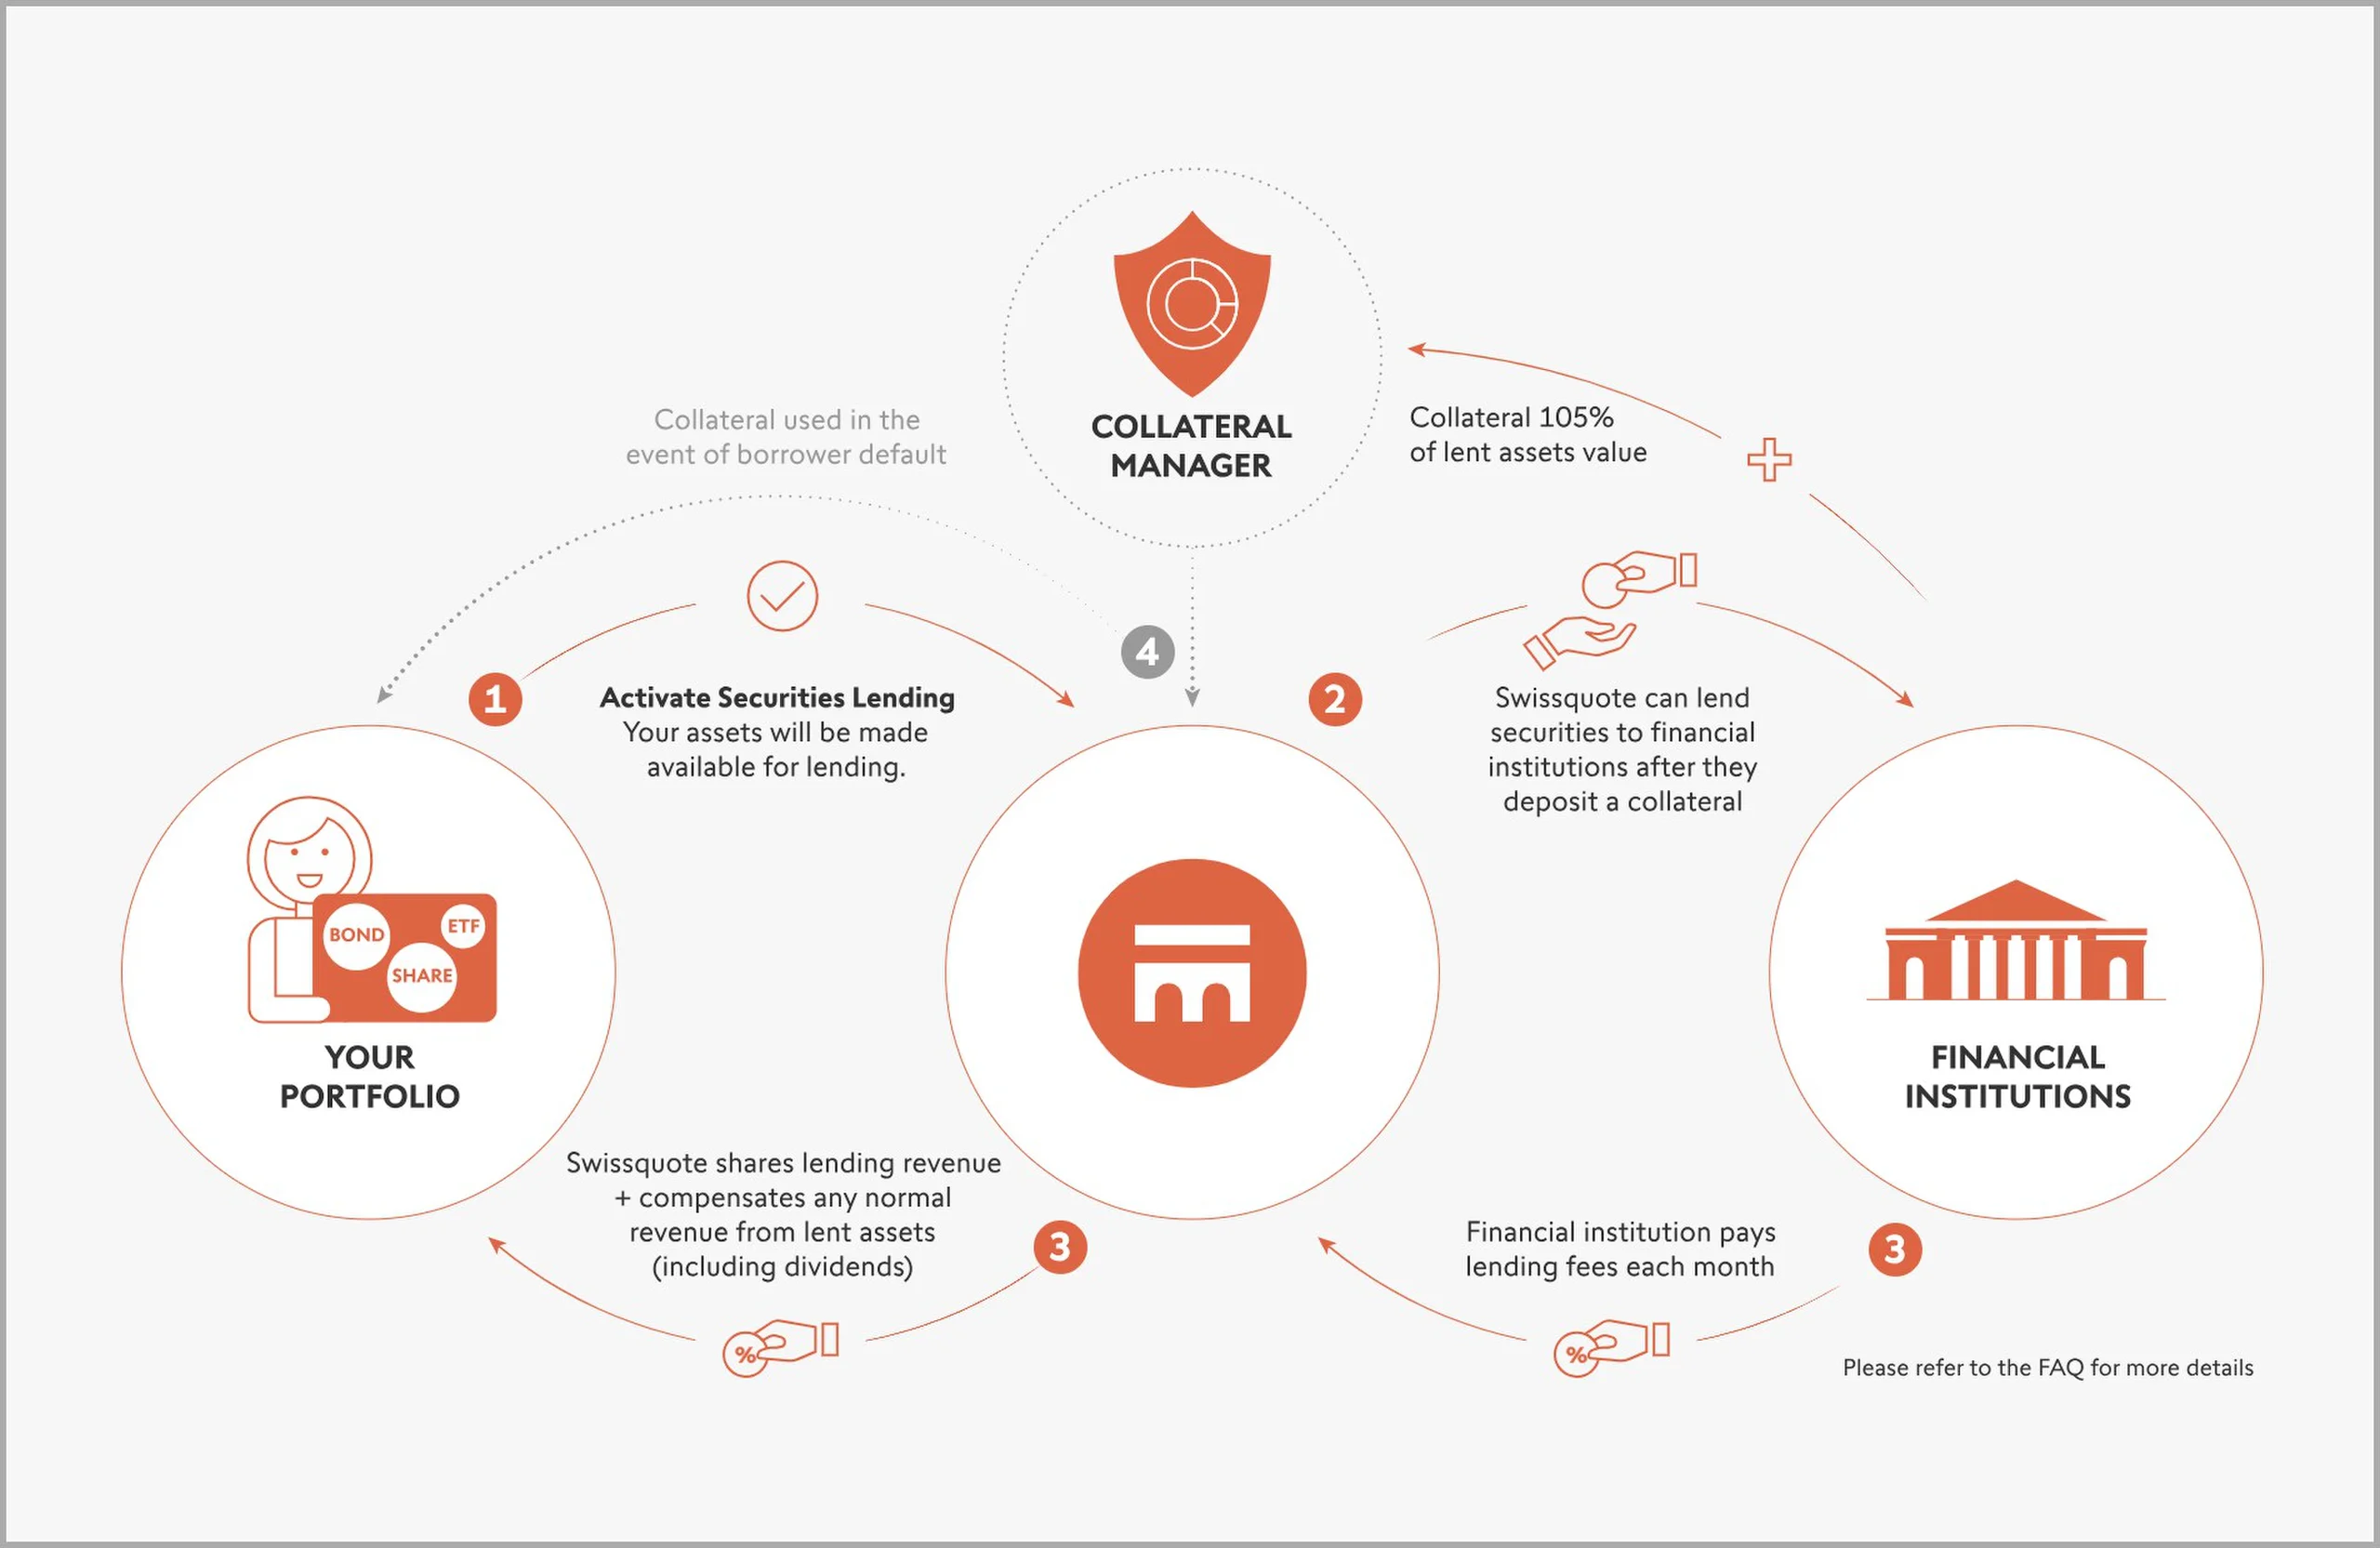
Securities lending is a free, optional service from Swissquote that gives you an additional way to generate passive income from your existing portfolio. Here’s how it works: on your behalf, Swissquote lends your securities to institutions that need them, and you receive a share of the resulting returns. This share can vary considerably: according to Swissquote, the gross return on lent securities ranges from 0.5% to over 4%, depending on the lending transaction. The income is credited monthly.
Swissquote assures that it only conducts securities lending with renowned, top-rated institutions and holds at least 105% in collateral.
Even when you lend out your securities, you remain their beneficial owner and continue to receive dividends.
Important: despite all of Swissquote’s safety precautions, securities lending means taking on an additional risk. Essentially, this is the risk that, in the event of a loss, the value of the collateral does not cover the value of the lent securities. You can find out more about Swissquote’s securities lending here.
Support
For us, one clear plus point of Swissquote is its support: competent, free of charge, multilingual and flexible via phone, email or chat.
Chat has proven particularly efficient for us (unlike phone enquiries, where we once spent 15 minutes on hold shortly before noon): while the bot handles standard questions well, the human support team answers more specific requests.
Once, phone support referred us to the contact form when we reported a bug in the demo version. (Some widgets in our workspace were no longer displayed correctly.) So we filled out the form and attached a screenshot of the faulty widgets as “evidence”. That same day, Swissquote let us know by email that fixing the problem would take two working days – which turned out to be true.
What many people probably don’t know is that, besides its headquarters in Gland (VD), the online bank Swissquote also runs a lounge in Zurich. Centrally located at Löwenstrasse 62, a five-minute walk from the main station, it’s where you can meet Swissquote in person. And not only, as mentioned above, for opening an account, but also to get stock market information & co. in a relaxed atmosphere or simply to enjoy a coffee.
As support in a broader sense, Swissquote offers a wide range of educational content in the form of free video courses, webinars and eBooks on all aspects of investing. These formats are primarily aimed at stock market beginners, as the following video on how the stock exchange works shows.
Suitability
Based on our Swissquote experience and the research we carried out for this review, we think the Swiss pioneer broker is particularly suitable for investors who value one or more of the following features when choosing a broker:
- Domestic broker with a Swiss banking license, Swiss deposit insurance of CHF 100,000 and 30 years of market experience
- Huge range with over 3 million products, including a wealth of (niche) ETFs, tradable on numerous exchanges around the world
- Attractive conditions for larger transaction amounts from CHF 1,000 thanks to the CHF 9 flat rate for “ETF Leaders” on the Swiss stock exchange SIX
- Automatic savings plan feature: regular investments of a fixed amount possible thanks to fractional trading, at moderate fees from CHF 3
- Separate foreign currency accounts, which let you save on currency exchange fees
- Competent, multilingual free support via email, phone or chat
- Flexible use: modern, customizable user interface and app for mobile devices
- All in one place: investing, transfers and saving, including cards
- Online courses for beginners
– Partner offer –
– – – – –
Interview with Romain Le Baud, Head of Marketing at Swissquote
As Head of Marketing, you shape Swissquote’s positioning. What are the most important challenges right now?
Romain Le Baud: Today’s market is more digital, faster and more price-sensitive than ever. For us, this results in three key challenges:
- Standing out in a market where everything looks the same
Many providers seem alike. Swissquote must remain clearly recognizable as an innovative, reliable and bold brand. - Balancing price sensitivity and value creation
Price pressure is rising. The key is to make visible the added value that comes with a regulated Swiss bank with a broad offering and stable infrastructure. - Keeping pace without diluting our long-term vision
The industry is accelerating – new technologies, new platforms, new asset classes. We want to stay agile without losing our direction or a consistent customer experience.
Ultimately, what matters is securing Swissquote’s leading position in an increasingly dynamic market – through a clear identity, innovation and reliability.
Swissquote is posting record results, yet custody fees are increasingly coming under criticism. Precisely because these fees are charged even when you don’t trade, many see them as a relic of traditional banking. What is your view on a possible fee cut and the opportunity to attract more price-sensitive investor segments?

It’s crucial to distinguish between a low-cost broker and a fully regulated digital bank. Swissquote is Switzerland’s leading digital bank – with Swiss regulation, customer service, in-house development and a broad investment universe of over 3 million products. This level of security, infrastructure and quality comes at a price, and we are convinced that the value we deliver clearly justifies it.
Our goal is not to be the cheapest provider but to offer the best value for money. For more price-sensitive customers who prefer a simpler, leaner offering, Yuh already provides a modern and competitive alternative with no custody fees.
Finally, a look into the crystal ball: what will banking and trading look like by 2030 – in terms of technology, regulation and customer behavior? And with which new features or products will Swissquote surprise us in the near future?
It’s hard to speculate reliably about future regulatory developments, and I hope you’ll understand that I only comment on specific new products once they’re ready to be announced. What is clear, however, is that two forces will shape the financial world until 2030: technology and customer behavior – and AI will strongly accelerate both.
- Technology: AI-based, seamless and highly personalized
By 2030, AI will be at the core of the trading and banking experience. Platforms will become smarter, more personal and more conversational – from analysis and risk control to almost invisible processes such as onboarding or compliance. Technology is thus evolving from an execution tool into the actual intelligence engine. - Customer behavior: from DIY trading to AI-assisted investing
Investors still want control, but less complexity. AI will simplify decisions and enable personalized, guided experiences. Banking, trading and digital assets will increasingly merge into one seamless user journey.
Many thanks, Romain, for these fascinating insights.
(The interview with Romain Le Baud was conducted in writing in English on 20 November 2025 and is reproduced here in slightly abridged form.)
Conclusion on our Swissquote experience
Our Swissquote experience has shown that the Swiss market leader offers an attractive overall package for anyone who values an online broker with a Swiss banking license.
This target group also benefits from a modern trading platform and efficient, multilingual customer support.
For us, however, the decisive reason to switch is the fees for the “ETF Leaders”: depending on order size, CHF 3 to a maximum of CHF 9 per trade on SIX. This makes Swissquote convincing on price, too, compared with other Swiss providers.
But even if you only want to invest smaller amounts, e.g. conveniently via an automated savings plan, Swissquote has made improvements and cut its entry-level prices significantly: CHF 3 for investment amounts up to CHF 500.
And one more thing: domestic payments at Swissquote are now free of charge. This change, overdue in our view, makes Swissquote interesting not only as an online broker but also as a traditional main bank – and therefore for anyone who wants banking and securities in one place.
You might also be interested in
Updates
2026-07-24: Modified fee model added.
2026-01-03: Various updates to text and images.
2025-12-16: New platform redesign presented.
2025-12-02: Bonus (trading credits) increased to CHF 200.
2025-11-21: New interview with Swissquote’s Head of Marketing Romain Le Baud added.
2025-10-06: Various minor updates made.
2025-07-15: Various minor updates made.
2025-01-13: New Swissquote vs. UBS share price chart added. Fee comparison updated. Various minor adjustments made.
2024-11-19: New savings plan offer with fees from CHF 3 explained and prices updated.
2024-04-11: Various links updated; the new “Invest Easy” tool for automated asset management and the new, purely virtual free “Light” debit card mentioned; note added that PostFinance has offered e-trading on the Swissquote platform since 2015.
2024-01-29: Clarified that Swissquote offers over 50 trading venues worldwide and more than 9,000 ETFs at the flat rate of CHF 9.
2023-12-08: Note on the demo account removed, as it was discontinued on 27 November 2023.
2023-10-05: New chapter on securities lending added.
2023-06-15: Comprehensive product range clarified and quantified.
2023-01-04: “In a nutshell” text block added.
2022-12-12: Text supplemented with the new investment plan for regular, automated investing.
2022-12-10: Fees updated: abolition of domestic payment fees as of 1 January 2023 included (previously a CHF 2 fee for outgoing payments).
Disclaimer
Disclaimer: Investing involves the risk of loss. You have to decide for yourself whether you want to bear these risks or not.
Errors excepted: We have written this article about our Swissquote experience to the best of our knowledge and belief. Our goal is to provide you as a private investor with finance information that is as objective and meaningful as possible. Should we nevertheless have made mistakes, or should important aspects have been forgotten and/or no longer be up to date, we would be grateful for your feedback.
Transparency note: We, Stefan and Toni, have extensive Swissquote experience, as for many years we have managed – and still manage – our securities accounts on Swissquote’s e-trading platform, including via PostFinance. In addition, for this review we opened a Swissquote demo account, executed trades with it and, based on that, tested Swissquote’s support through various channels.
About the authors
Stefan Huser
Stefan has been investing in the stock market himself since 2015. He has been shaped by Markowitz’s portfolio theory and Gerd Kommer’s book “Souverän investieren”. He follows a core-satellite strategy: a global equity portfolio of ETFs forms the core, complemented by alternative investments. At the blog, he mainly takes care of the writing. Stefan lives with his family in Zurich and is interested in literature, photography and financial freedom.
Antun Brcina
Antun (“Toni”) has been investing in the stock market since 2015. Financially, he has been particularly inspired by Gerd Kommer’s book “Souverän investieren” and the Fama-French five-factor model. His money is invested in a broadly diversified, long-term global equity portfolio of ETFs. At the blog, he mainly works on the calculators and the code. Toni lives with his family in the Zurich area and is interested in sports, technology and entrepreneurship.

27 Comments
Bei einem hohen Betrag in EUR z.B. 100k, lieber bereits vor dem Kauf in die benötigten Währungen über z.B. Wise wechseln und dann zu SQ senden?
Und kann man grundsätzlich sagen, dass man bevorzugt immer über die SIX und in CHF kaufen sollte? Wenn man langfristig in der Schweiz lebt und die Kosten für Transaktionen mindern möchte.
Ich habe vor 2-3 ETF und Edelmetalle (über ETF abgebildet) zu kaufen.
Wenn deine Referenzwährung CHF ist, sparst du bei ETFs in Handelswährung CHF natürlich die Wechselgebühren. In unserem umfassenden ETF-Review gibt es einige attraktive Exemplare in Heimwährung an der SIX, alle auch bei Swissquote handelbar. Wenn es dein Wunsch-ETF jedoch nicht in Handelswährung CHF gibt, kann sich vorgängig ein Währungswechsel bei einem günstigeren Drittanbieter und danach kostenlose SEPA Überweisung (nur in EUR) vor allem bei grösseren Beträgen durchaus lohnen.
Danke für die schnelle Antwort. Was sind Vorteile und Nachteile bei den anderen Währungen. In letzter Zeit ist der EUR ja abgewertet zum CHF
Vorteile:
– Auswahl an ETFs in Handelswährung EUR oder USD ist global betrachtet deutlich grösser
– Das Handelsvolumen ist oft grösser, was die Handelsspanne tief hält (Spread)
Nachteil:
– Währungswechselgebühren
Wichtig: Das Währungsrisiko (“Abwertung Euro”) hängt nicht mit der Handelswährung ab, sondern vom Domizil der im ETF/Index gelisteten Unternehmen.
Hallo
Erstmal vielen Dank für den super Blog!
Mich würde noch gerne etwas genauer interessieren ob eine Depot-Übertragung von IBKR beispielsweise zu Swissquote auch einfach funktioniert.
Ich spare schon regelmässig seit einigen Jahren in ETFs (Börse Schweiz, Euronext und Xetra). Mein Depot habe ich aktuell bei Degiro und da bin ich eigentlich zufrieden.
Da ich jetzt aber langsam etwas höre Beträge angespart habe, würde ich mich wohler fühlen wenn meine Einlagen von einem Broker welcher in der Schweiz reguliert ist, verwaltet werden.
Ich überlege mir also zu Swissquote zu wechseln, möchte aber nicht die hohen Handelsgebühren zahlen. Deswegen ist meine Idee, bei einem günstigen Broker (Degiro, IBKR) zu kaufen und dann sobald ein grösserer Betrag zusammengekommen ist die Position zu Swissquote zu übertragen.
Wäre das ein Ansatz? Was müsste ich dabei speziell bedenken?
FG, Cary
Hoi Cary
Merci für das Lob und deine unkonventionelle Idee. Positiv: Für Überträge von Wertschriften zu Swissquote gibt es aktuell ein bis Ende Mai 2025 befristetes Spezialangebot, wonach Swissquote die Übertragungskosten von bis zu 500 CHF übernimmt (vgl. auch https://www.swissquote.com/de-ch/500). Speziell bedenken würden wir, ob die zu übertragenden ETFs zu den sogenannten ETF Leaders (vgl. Swissquote Website) gehören, deren Courtagen, z.B. bei einem späteren Verkauf, bei 9 CHF gedeckelt sind. Wenn nicht, studiere doch mal die entsprechende Swissquote Preisliste für (spätere) Trades in der von dir gewünschten Höhe, sodass du bezüglich der vergleichsweise hohen Gebühren kein böses Erwachen hast.
Beste Grüsse
SFB
Hallo Schweizer Finanzblog
Ich bin in vertiefter Recherche zwecks Start meiner Fondssparpläne auf euren tollen Blog gestossen.
Thema Swissquote, ETF-Fondssparplan: Habt ihr den neusten Wurf, dieses Angeot ev. schon kritisch geprüft?
https://www.swissquote.com/de-ch/private/invest/products/saving-plan
Eure Konklusion und Meinung dazu würde mich sehr interessieren (Frei wählbare ETF’s/Palette; Gebühren Kauf/Depot; Handling; mehrere Fondssparpläne möglich…).
Und könnte ich hierbei die 200.- TradingCredits auch mitnehmen?
Danke für euer Feedback, Gruss Rolf
Hoi Rolf
Vielen Dank für den Hinweis. Wir haben die neuen Einstiegspreise von Swissquote ab 3 CHF im Artikel thematisiert. Mit dieser Preissenkung ist Swissquote nun endlich auch für kleinere Investitionsbeträge interessant geworden, insbesondere im Zusammenhang mit den von dir erwähnten neu lancierten Sparplänen, welches automatisiertes Investieren mit gleichbleibenden Beträgen (Fractional Trading) ermöglicht.
Und ja, gemäss Swissquote können unsere Trading Credits auch für die Sparplan-Gebühren verwendet werden. Es gelten jedoch Bedingungen, u.a. 3 Monate Gültigkeit (vgl. auch das Kleingedruckte in unserem Werbebanner).
Beste Grüsse
SFB
Ich plane, langfristig in einen ETF zu investieren. Da ich recht unerfahren bin, wollte ich mit einer kleinen Summe die Funktionalität der Plattform ausprobieren. Ich habe einen HBSC MSCI World in USD auf SIX gekauft. Mir wurden beim Kauf lediglich die Kaufgebühren angeziegt. Den TER kann ich nirgends finden und auch keine Info, ob meine Variante ausschüttend ist. Gibt es Aussiegskosten? Ich bin wie gesagt neu und habe vielleicht einiges noch nicht gefunden.
Die TER findest du auf dem Produkt-Factsheet des ETF-Anbieters, also in deinem Fall HSBC. Die TER wird dir direkt vom ETF-Anbieter abgezogen, ohne dass du dafür eine Abrechnung erhältst. Ebenfalls auf dem erwähnten Factsheet ist aufgeführt, ob es sich bei deinem ETF um eine ausschüttende oder thesaurierende Variante handelt. Nein, Ausstiegskosten gibt es bei ETFs nicht, sondern du bezahlst einfach beim Verkauf die entsprechenden Transaktionskosten, die bei Swissquote transparent ausgewiesen werden. In diesem Artikel findest du, worauf du beim ETF-Kauf achten solltest: ETFs: Worauf du bei der Wahl achten solltest
Vielen Dank!
Swissquote bietet wieder einmal ein exklusives Angebot zum Einführungspreis von CHF 9.- Spesen bis zum 30. Juni an.
So etwas habe ich vor einiger Zeit schon einmal erlebt: “Lake Diamond”, ein Unternehmen von angeblich hervorragender Qualität, von Swissquote geprüft und für gut befunden. Das Angebot bestand darin, dass pro gekauften Aktienanteil 10 % gratis dazugegeben wurden.
Und was ist passiert? Die seriöse Firma “Lake Diamond” ist kaputt gegangen und das Geld alles verloren. Und die ganze Swissquote-Crew wusch selbstverständlich die Hände in Unschuld. Der CEO teilte mir in einer eMail mit, dass die Verantwortung ja bei mir liegen würde.
Wenn ich mir die jetzt angebotenen Titel anschaue, sehe ich nicht eine bessere Qualität, als damals bei “Lake Diamond”. Also Leute passt auf!
Meine Mutter und ich haben jeweils ein Konto bei Saxo geöffnet. Wurden aber beide nach wenigen Tagen gesperrt. Obwohl ich “nur” 50k eingezahlt habe und es keine Schenkung ist, muss ich folgendes einreichen:
“Wir benötigen einige zusätzliche Finanznachweise von Ihnen. Bitte legen Sie die folgenden Unterlagen über die erhaltene Schenkung vor:
– Die Schenkungserklärung/den Brief des Schenkers mit Angabe des Schenkungsbetrags, des Eingangsdatums und des Grundes für die Schenkung.
– Ein Kontoauszug, welcher den geschenkten Betrag ausweist.
– Der Ausweis des Schenkers.
– Belege über die Herkunft der Mittel des Schenkers. ”
Meine Mutter muss auch 5 verschiedene Dokumente, inkl. Angaben des Arbeitgebers, Lohnausweis, etc. einschicken, obwohl sie pensioniert ist.
Ist das normal bei Schweizer Brokern, also ist Swissquote auch derart restriktiv? Weil Degiro ist es definitiv nicht.
In deinem Fall liegt ja offensichtlich ein Missverständnis vor. Kläre doch deinen Broker einfach über die korrekte Mittelherkunft auf und teile ihm mit, dass es sich nicht um eine Schenkung handelt, weshalb du auch nicht gewillt bist, die entsprechenden Unterlagen einzureichen.
Danke dir. Habe es versucht, aber sie halten daran fest. Jänu, dann schliesse ich halt mein Konto bei Sao, wechsle zu Degiro, kaufe dort einen ETF und führe dann einen Depotübertrag durch zurück zu Saxo.
Hallo Beat
Wie ist da jetzt mit den Gebühren? Ab welchem Betrag lohnt es sich monatlich (als Sparplan) bei SQ zu investieren z.B. in den ETF Vanguard FTSE all world? Pro Transaktion kostet es ja jetzt CHF 5.00. Es gibt doch eine Faustregel…?
Danke für dein höfliches Feedback 😉
Einen guten Rutsch und auf ein erfolgreiches neues Jahr!
Hallo SFB Team
Gibt es bei SQ einen globalen ETF auf FTSE oder MSCI, welcher in Euro gehandelt wird und günstig ist zu erwerben? Bei den Flatrate CHF 9 ETFs, finde ich nur ETFs in USD und CHF. Ich habe eine grössere Summe inEuro, welche ich in 5-10 Tranchen anlegen möchte.
…dieser nachhaltige ETF von iShares basierend auf dem MSCI World SRI ist in Handelswährung EUR und mit einer TER von 0.20% recht günstig: IE00BYX2JD69. Konventionelle ETFs zu einem vernünftigen Preis sind aber in der Tat Mangelware. Am besten recherchierst du direkt auf der SIX-Seite, wo du nach Handelswährung filtern kannst.
Wenn immer man ETFs/Aktien in Fremdwährungen kauft/verkauft, fallen Wechselgebühren an. Diese betragen bei Swissquote fast 1%! Bei Degiro sind es es nur 0.25%. Das ist drei-Viertel weniger!
Diese Wechselgebühren können sich schnell als grösster Kostenfaktor herausstellen. Beim Kauf der Fremdwährungen werden sie zudem nicht deklariert. Man muss sich zuerst durch lange Preislisten lesen…
Auch bei den meisten anderen Gebührenarten ist Degiro viel günstiger und kostet in der Regel eine Bruchteil…
Deine erste Aussage trifft auf DEGIRO zu, nicht aber auf Swissquote. Denn Swissquote bietet im Gegensatz zu DEGIRO Fremdwährungskonten an. Du bist bei Swissquote also nicht verpflichtet, den Geldwechsel über Swissquote abzuwickeln. Stattdessen kannst du beispielsweise die bei deiner Hausbank bereits vorhandenen Euro-Vermögen oder bei einem günstigen Drittanbieter deines Vertrauens gewechselten Euro-Bestände aufs Euro-Konto von Swissquote überweisen und sparst so die Wechselgebühren ganz oder teilweise. Ansonsten teilen wir deine Meinung natürlich: Wechselgebühren können ins Gewicht fallen und sollten deshalb im Auge behalten werden.
Und sollten transparent angezeigt werden. Das vermisse ich bei SQ schon noch!
Im Bericht vermisse ich alles was bei SQ neu wurde. Die neuen Gebühren gehören da rein. Auch vermisse ich Infos über die Investitionspläne, welche neu möglich sind bei SQ.
Aus meiner Sicht ist der Artikel auf einem Stand vor einem Jahr. Wurde der aus der Mottenkiste genommen?
Nein, natürlich nicht aus der Mottenkiste, Beat😉 Der Artikel ist taufrisch, enthält sogar bereits ein erstes Update, welches die Gratiszahlungen aufgreift, welche Swissquote neu per 1.1.2023 einführen will. Gegenfrage: Gibt es Informationen/Gebühren im Artikel, die für dich nicht mehr stimmen? Wenn ja, danke im Voraus für deinen entsprechenden Hinweis. Bezüglich der Investitonspläne: Damit meinst du wohl das automatisierte Investieren in einen bestimmten ETF & Co. mit einem fixen Betrag und vordefiniertem Intervall, oder? Diese Info haben wir in einem Kundenmailing von Swissquote erst am 29.11.2022 erhalten. Aber du hast recht: Diese Info könnte die eine oder der andere langfristig orientierte ETF-Anleger:in (Diese Zielgruppe wollten wir im Artikel ansprechen.) interessieren. Wir werden dieses Thema deshalb gerne noch im Artikel aufnehmen. Merci für diesen Hinweis/Reminder!
Beste Grüsse
SFB
Ihr rüde Art ist unangebracht und despektierlich. Ihre Hinweise als Gratiskonsument, so berechtigt diese sein mögen, lesen alle interessierten hier lieber in einem respektvollen und höflichen Ton.
Hallo Guido
Ich denke dies galt meinem Eintrag. Ich finde weder daran etwas rüde noch despektierlich. Aber ist bezeichnend für die heutige Zeit das man in den Kommentaren nur noch loben darf und nicht Kritik anbringen.
Und deshalb ein grosses Lob an das SFB Team, welche den Kommentar veröffentlicht hat und dazu Stellung nahm.
Ich weis nicht was für Sie respektvoll ist. Meine Schreibweise ist direkt ja. Aber diese als unhöflich zu titulieren, fragt sich dan was unhöflich ist. 🙂
Grüsse
Beat
Da ich von Sonderkonditionen bei einer Universalbank profitieren kann, lohnen sich für mich keine anderen Lösungen. Nichtsdestotrotz gratuliere ich zu diesem neuen Bericht. Well done! Jedoch habe ich überschlagsmässig den Eindruck, dass die PostFinance overall die attraktivere Alternative zu Swissquote für die meisten Anlegerprofile mit Domizil Schweiz darstellt.
Merci für das positive Feedback! Und ja, es mag gute Gründe für ein Depot bei Postfinance geben. So können je nach Vermögensgrösse die Depotgebühren bei PostFinance etwas tiefer liegen als bei Swissquote. Auf der anderen Seite kauft PostFinance Know-how und eTrading Plattform bei Swissquote ein. Diese Abhängigkeit erachten wir nicht unbedingt als Vorteil und schlägt sich auch in der diesbezüglich mässigen Kompetenz beim PostFinance Support nieder. Den grössten Trumpf von Swissquote gegenüber PostFinance sehen wir aber im vergleichsweise günstigen Pauschaltarif von 9 CHF bei Transaktionen mit “ETF Leaders” und anderen Produkten, welche an der SIX gehandelt werden.