
 Newsletter
If you want to build wealth over the long term, on your own terms and successfully, there is hardly any way around it: investing in ETFs is the smartest way to invest today. Exchange-traded index funds let you invest in thousands of companies worldwide with a single transaction, at low cost and transparently – without an expensive fund manager. In this sixth lesson of our finance guide, you will find out what is behind the acronym, why ETFs have revolutionised investing and why you can benefit from them too.
< Lesson 5 | Overview | Lesson 7 >

In a nutshell
- An ETF (exchange-traded fund) is an index fund traded on the stock exchange that tracks a stock index passively and according to fixed rules.
- Unlike actively managed funds, ETFs do without stock picking and expensive fund managers – which is why they cost only a fraction.
- Investing in ETFs means relying on a simple, low-cost and scientifically sound investment principle – with minimal effort and maximum diversification.
- Legally, ETFs are segregated assets: the money you invest is held separately from the assets of the ETF provider and the custodian bank. If one of these institutions goes bankrupt, your ETF units remain yours.
- Numerous studies show that most active funds fail to beat their benchmark index over the long term – the strongest argument for investing passively in ETFs.
Contents
What is an ETF?
ETF stands for exchange-traded fund – in other words, an index fund traded on the stock exchange. Those three words already contain the essentials.
Index fund means that an ETF tracks a specific stock market index – such as the MSCI World, with over 1,000 companies from 23 developed countries. The ETF buys the shares contained in the index and holds them in the same proportions. If the index rises by 2%, the ETF also rises by around 2%. If the index falls, the ETF falls. No fund manager decides which shares are bought or sold – the index rules take care of that. This makes ETFs passive and fundamentally different from traditional investment funds, where a management team actively tries to beat the market.
Exchange-traded means that you can buy and sell an ETF on the stock exchange at any time during trading hours – just like an individual share. Unlike traditional funds, which calculate a price once a day, an ETF shows you what it is worth in real time.
And the costs? Because no fund manager has to analyse and select shares, a large part of the fees charged by actively managed funds disappears. The annual costs (expressed as the TER, total expense ratio) of broadly diversified ETFs are typically between 0.1% and 0.3% of the invested capital – and still falling. Intense competition among ETF providers has caused fees to practically erode. What cost 0.5% ten years ago is available for a fraction of that today. By comparison, active funds often charge five to ten times as much – year after year. What makes it particularly bitter: the vast majority of these expensive funds do not even manage to beat the market. So you pay more and get less.
So much for the basic principle. To classify and assess an ETF, it is worth looking at three aspects: the underlying index, the name and what it means, and its legal structure as segregated assets.
The index at the heart of it all
The underlying index is the real heart of an ETF. Indices such as the MSCI World or the FTSE All-World are calculated by specialised, independent providers – in the case of these two examples, MSCI (Morgan Stanley Capital International) and FTSE (Financial Times Stock Exchange). Strict rules define which companies are included, how they are weighted and when the composition is reviewed.
For you as an investor, this means that the choice of index determines which countries, regions and sectors you invest in – and therefore a large part of your future return. We take a closer look at how to find the «right» index and ETF in Lesson 7.
What the name of an ETF tells you
Reading an ETF name for the first time can feel overwhelming. Let’s take an example: «Vanguard FTSE All-World UCITS ETF (USD) Accumulating». It sounds unwieldy, but it follows a clear logic:
- Vanguard – provider (the fund company that issues the ETF)
- FTSE All-World – underlying index (global stock index with over 4,000 companies from developed and emerging markets)
- UCITS – «Undertakings for Collective Investment in Transferable Securities»; signals that the ETF is subject to strict European investor protection rules (high transparency, diversification requirements, regulatory supervision). Practically all ETFs tradable in Europe carry this abbreviation.
- ETF – you know this one now
- (USD) – fund currency (the currency in which the fund assets are calculated)
- Accumulating – dividend treatment (here reinvesting, i.e. accumulating)
You do not have to memorise these abbreviations. But once you have figured them out, no ETF name will scare you any more. In our article Understanding ETF abbreviations: 1C, UCITS, MSCI & co. explained simply, you will find a complete overview of all common abbreviations.
Legally segregated assets
One point that is particularly reassuring for beginners: in Switzerland, ETFs are legally segregated assets (governed by the Collective Investment Schemes Act, CISA). This means that the money you invest is held separately from the assets of the ETF provider and the custodian bank. If one of these institutions goes bankrupt, your ETF units remain yours.
By the way, the same applies to your broker: your ETF units are held separately as securities and belong to you, not to the broker – whether you buy through Swissquote, a cantonal bank or a foreign provider. Even if your broker runs into financial difficulties, your securities are protected. You would simply have to transfer them to another broker. With broadly diversified, classic equity ETFs, a total loss is therefore practically impossible – both legally and economically.
A brief history of ETFs
The idea of not beating the market but simply replicating it is older than many people think. In 1975, John «Jack» Bogle founded the investment company Vanguard and shortly afterwards launched the first index fund for private investors – the «Vanguard 500 Index Fund». At the time, the idea was revolutionary and Wall Street laughed at it: a fund that does not even try to outperform the market? Bogle was proved right.
However, it took almost two more decades for the idea to take its next evolutionary step. On 22 January 1993, State Street Global Advisors launched the first exchange-traded index fund: the «SPDR S&P 500 ETF» (ticker symbol: SPY). The «Spider», as it is colloquially known, tracks the 500 largest listed US companies – and, with assets under management of around 700 billion US dollars, is now the largest ETF in the world. By comparison, it started out with 6.5 million US dollars.
Since the 2000s, growth has accelerated massively. Worldwide, more than 20 trillion US dollars are now invested in ETFs – a number with 13 zeros. The trend is not hype, but the logical consequence of a superior product innovation.
ETFs in Switzerland
The Swiss stock exchange SIX was one of the first in Europe to introduce an ETF segment – back in 2000. Since then, the range has grown rapidly: in 2026, over 2,000 ETFs are listed on SIX, spread across asset classes such as equities, bonds, commodities, real estate and – for some years now – cryptocurrencies. By comparison, in 2018 there were still around 1,300. Equity ETFs make up the lion’s share – around two thirds of the total range.
The Swiss market is dominated by the providers UBS and BlackRock (with the ETF label «iShares»). Globally, BlackRock and Vanguard are the undisputed market leaders.
Why ETFs are the best thing that could have happened to your money
Enough theory – now it gets personal. Before ETFs, the world looked like this for private investors: you could entrust your money to a fund manager who collected high fees and, in most cases, performed worse than the market. Or you could buy individual shares yourself – with the risk that one wrong bet would wreck half your portfolio. There was hardly a third option.
ETFs have fundamentally changed the game. They make possible something that was previously unthinkable. Investing in ETFs means owning a share of thousands of companies worldwide with a single transaction and no minimum amount – at costs so low that you hardly notice them.
A simple calculation shows how powerful this is. If you invest CHF 100,000 in an active fund with fees of 1.5% a year, you lose a six-figure sum in returns over 30 years – thanks to the compound interest effect, the damage grows far beyond the fees themselves. With an ETF costing 0.2%, that amount stays in your portfolio. That is why we say it openly: if you want to invest broadly diversified and for the long term, you will not find a better instrument than an ETF.
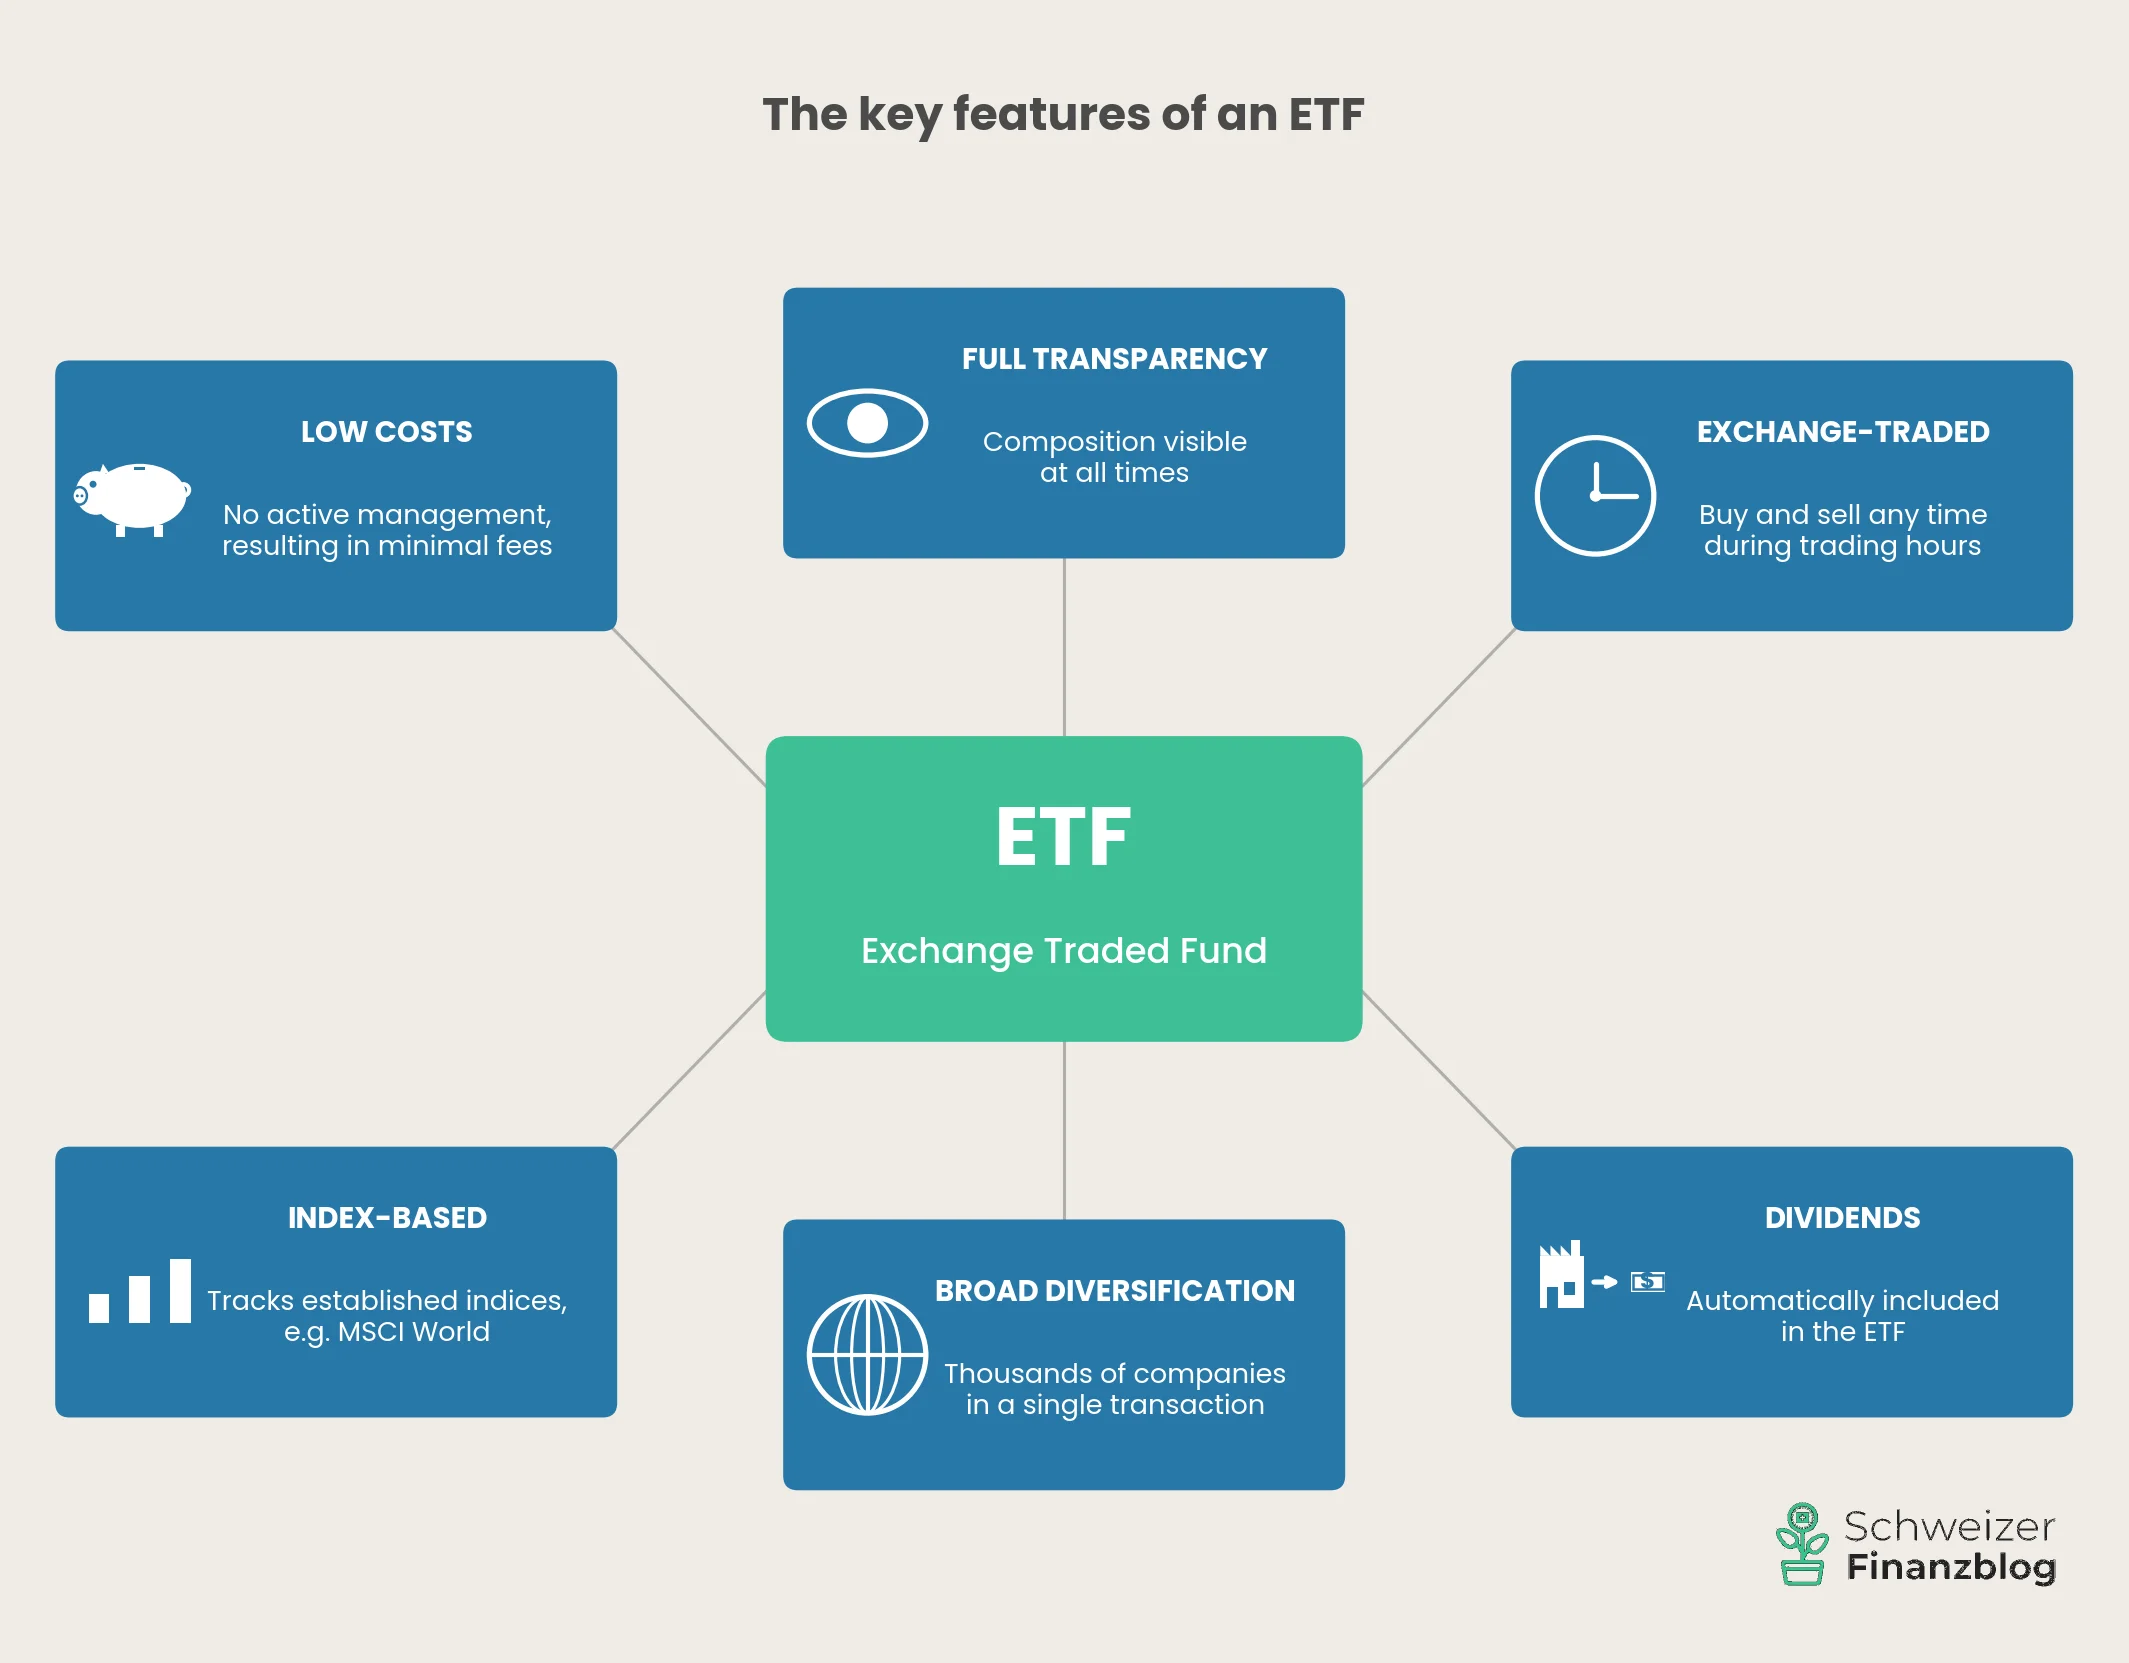
But it is not just about money. ETFs offer a combination of features that no other investment product brings together in this form: full transparency about the securities they hold, daily tradability on the stock exchange, entitlement to dividends and – as described in the previous chapter – legal protection as segregated assets.
Doubling your wealth every nine years with an ETF
And what does that mean in concrete terms? Anyone who has invested broadly in the global stock market over the past few decades has earned an average return of around 8% a year. That sounds unspectacular – until you factor in the compound interest effect : at 8%, your wealth doubles roughly every nine years (rule of thumb: 72 divided by the interest rate). In 30 years, CHF 100,000 turns into more than CHF 1,000,000. Of course, past returns are no guarantee of future results. But the historical evidence over more than a century is impressive.
Warren Buffett’s seal of approval
A remarkable scene from 2017 shows that ETFs and passive investing are not an idea dreamed up by outsiders, but a strategy recommended even by the most successful active investors. At the Berkshire Hathaway annual meeting – in front of 40,000 shareholders – Warren Buffett asked Jack Bogle, then almost 88 years old, to stand up. Bogle, the founder of Vanguard and inventor of the index fund, was sitting in the audience. Buffett said that no one had done more for American private investors than Bogle, and that his idea would save them hundreds of billions of dollars over time.
«If a statue is ever erected to the person who has done the most for investors, Jack Bogle is the clear choice.»
Warren Buffett
So when probably the most famous active investor in the world advises his followers to go for the passive counterpart, that says it all.
Why your bank does not recommend ETFs
Imagine you go to your Raiffeisen adviser and say: «I want to invest CHF 100,000 in a single global ETF.» The chances that he will nod enthusiastically are slim. Instead, he will probably recommend an in-house strategy fund – «Raiffeisen Futura» or similar – perhaps with currency hedging and a regular advisory meeting on top. All of this sounds sensible, but it can easily cost you 1.5% or more a year. With CHF 100,000 and an investment horizon of 30 years, we are talking about a difference of several tens of thousands of francs compared with a simple ETF solution.
The same goes for UBS, PostFinance or your cantonal bank. The business model of these institutions is based on fees for advice, management and in-house products. An ETF that costs 0.2% and needs no adviser simply does not fit this model. That does not mean your bank adviser is out to harm you – he recommends what is in his product range. But that range is not put together in your interest, but in the bank’s interest.
Stefan experienced this first-hand during his training as a financial adviser: structured products, options, strategy funds and life insurance were covered at great length – all of them high-margin products. ETFs? A footnote. The reason we put ETFs at the centre of this finance blog is simple: we are independent.
It gets particularly expensive with supposed protection: currency hedging, capital protection products or «dynamic» strategies that switch into bonds during turbulence. What sounds like safety at first glance mainly eats into returns over a long investment horizon. With these products, you pay twice – in the form of lower returns and hefty fees.
The rule of thumb is therefore uncomfortable, but honest:
«The most obvious route – simply going to your bank and letting them handle it – is often the most expensive.»
The honest downside
As convincing as the advantages are, if you want to inform honestly, you also have to show the other side. We see no relevant disadvantages of ETFs compared with active funds or individual shares. But there are risks and peculiarities you should know about.
Market risk
The biggest risk lies not in the ETF itself, but in the market. If global stock markets crash by 30%, your ETF falls by 30% too – because it tracks the market, no more and no less. The key difference from an individual share: a total loss is practically impossible with a broadly diversified ETF. And experience shows that global portfolios have always recovered, even after severe crashes – as we showed with historical data in Lesson 1.
No voting rights
If you own individual shares, you have a say at the annual general meeting. With an ETF, you do not: the voting rights are exercised by the fund company – i.e. by providers such as BlackRock or Vanguard. Hand on heart: when did you last attend an annual general meeting? For the vast majority of private investors, this is a theoretical disadvantage that plays no role in practice.
Deadly boring – and exactly right
An ETF on the MSCI World will never deliver the return of a Tesla share in its best year. But it will never crash like Credit Suisse either. ETFs are the opposite of a thrill – and that is not a bug, it is a feature. If you want to build wealth over the long term, you do not need adrenaline, you need discipline and patience. The fact that ETFs are «boring» may well be their greatest advantage.
Counterparty risk – mostly theoretical
One last point, for the sake of completeness: with so-called synthetic ETFs – which track an index not by buying the shares it contains, but through an exchange transaction (swap) – there is a counterparty risk. The same applies to ETFs that engage in securities lending. In practice, these risks are tightly limited and secured by regulation. Synthetic ETFs are also in sharp decline. If you want to play it safe, simply choose physically replicating ETFs – which is what we recommend anyway. You will find out exactly what «physically replicating» means in Lesson 7.
– Partner offers –
Still looking for the right financial solution? Our recommendations – with attractive sign-up bonuses.
– – – – –
Conclusion
ETFs have democratised investing. What used to be reserved for institutional investors with million-franc budgets – investing in global markets in a broadly diversified, low-cost and rule-based way – is now open to everyone. With a single transaction. And it keeps getting better: fees keep falling and the range keeps growing – investing in ETFs is more attractive today than ever before.
The idea is as simple as it is effective: instead of trusting an expensive fund manager who, in most cases, does not beat the market anyway, you simply replicate the market. You save fees, avoid unnecessary risks from individual stocks and benefit from the full breadth of the global economy. The fact that even Warren Buffett – probably the most successful stock picker of all time – recommends exactly this route for private investors speaks for itself.
Of course, ETFs are exposed to market risk – but that is not an argument against ETFs, it is an argument against unrealistic return expectations. If you have understood the basics from the previous lessons – think long term, diversify broadly, keep costs low – ETFs are the ideal tool for putting this strategy into practice.
That leaves the crucial question: which ETF should you buy? In Lesson 7, we take a closer look: What to look out for when choosing.
You can find an overview of all lessons here: Learning to invest – in eight lessons.
You might also be interested in

Updates
2026-06-13: Text revised in places.
2026-04-17: Article completely revised and updated.
Disclaimer
Exclusion of liability: Investing involves the risk of loss. You have to decide for yourself whether or not you want to take these risks.
Errors excepted: We have written this article «Investing in ETFs…» to the best of our knowledge and belief. Our aim is to provide you as a private investor with the most objective and meaningful information possible on the subject of finance. Should we nevertheless have made mistakes, forgotten important aspects and/or if information is no longer up to date, we would be grateful for any feedback.
About the authors

Stefan Huser
Stefan has been investing in the stock market himself since 2015. He has been shaped by Markowitz’s portfolio theory and Gerd Kommer’s book “Souverän investieren”. He follows a core-satellite strategy: a global equity portfolio of ETFs forms the core, complemented by alternative investments. At the blog, he mainly takes care of the writing. Stefan lives with his family in Zurich and is interested in literature, photography and financial freedom.

Antun Brcina
Antun (“Toni”) has been investing in the stock market since 2015. Financially, he has been particularly inspired by Gerd Kommer’s book “Souverän investieren” and the Fama-French five-factor model. His money is invested in a broadly diversified, long-term global equity portfolio of ETFs. At the blog, he mainly works on the calculators and the code. Toni lives with his family in the Zurich area and is interested in sports, technology and entrepreneurship.








12 Comments
Lieber Stefan, lieber Toni
Vielen, vielen Dank für eure tollen Beiträge! M.E. ist ein Besuch auf euren Blog für alle Privatinvestoren in der CH ein Muss!
Zum Thema Währungsrisiko hätte ich noch eine Frage:
Leider gibt es den IE00BK5BQT80 an der SIX in der thesaurierenden Variante nicht, so dass ich diesen ETF via Swissquote an der Xetra in € gekauft habe. Aufgrund des aktuell starken CHF gegenüber dem € habe ich hier aktuell eine Performanceeinbusse.
Ich überlege mir, sobald sich der Wechselkurs CHF|€ wieder stabilisiert hat (1:1), alle Anteile zu verkaufen und die Summe im ETF IE00B6R52259 an der SIX anzulegen, da dieser ETF auch global diversifiziert ist und die Handelswährung in CHF ist.
Würde ich somit besser fahren resp. das Handelswährungsrisiko komplett reduzieren?
Vielen dank für eure Unterstützung!
Beste Grüsse
Gia
Liebe Gia
Merci fürs Lob! Bitte beachte, dass das Währungsrisiko nicht mit der Handelswährung zusammenhängt, sondern mit der Währung der im Index abgebildeten Unternehmen. Wenn du also in einen ETF investierst, welcher zu einem grossen Teil US-Firmen enthält, dann hängt das Währungsrisiko primär von der Entwicklung vom USD im Verhältnis zu deiner Heimwährung ab, unabhängig davon, welches die Handels- oder Fondswährung ist. Mit der Handelswährung sind lediglich Währungswechselgebühren, welche je nach Broker unterschiedlich hoch ausfallen, verbunden. Wenn du diese vermeiden möchtest, solltest du vorzugsweise in ETFs mit Handelswährung CHF investieren.
Beste Grüsse
SFB
Vielen Dank!
Liebe Grüsse
Gia
Liebe Blogger,
Ich plane, 2/3 meines PK-Vermögens in ETF (Mix mit ESG) anzulegen; würdet ihr sagen, es ist eine gute Idee, auf ausschüttende ETF zu setzen, damit ich meine Rente aufbessern kann?
Gruss aus Basel
Hoi Christoph
Ja, dies dürfte in deiner Situation und wenn du einen längeren Anlagehorizont (ca. 10 Jahre) verfolgst eine gute Idee sein, da dieser Zustupf zu deiner Rente ohne zusätzliche Gebühren verbunden ist und automatisiert, d.h. bequem ohne dein aktives Zutun erfolgt (im Gegensatz zum Verkauf von ETF-Anteilen). Wenn du im grösseren Stil und systematisch Vermögen abbauen möchtest, ohne vorzeitig Pleite zu gehen, könnte dich dieser Artikel über Entnahmepläne interessieren.
Beste Grüsse
SFB
Noch eine Frage: wenn man z.B. 250 CHF montlich per ETF spart, lässt sich überhaupt ein Portfolio Allokation – 60% MSCI World, 30% MSCI Emerging Markets und 10% Immobilien ETF erreichen oder ähnlich?
Ich kenne die Preise für die einzlenen ETFs (noch) nicht, aber wenn jeder ETF 100 CHF kostet, lässt sich diese Allokation monatlich schwer mit den 250 CHF einhalten oder? Oder kann man von jedem ETF kleinere Tranchen kaufen, die weniger als z.B. 100 CHF kosten, um dann so die Allokation monatlich einzuhalten?
Ja klar, das lässt sich gut erreichen. Statt aber 250 CHF mühsam Monat für Monat für drei ETFs zu splitten und drei manuelle Trades zu machen, ist es doch viel einfacher, wenn du die 250 CHF in jeweils nur einen ETF investierst. Nach einigen Monaten wirst du dann deine Zielallokation ungefähr erreichen. Danach investierst du die 250 CHF jeweils in jenen ETF, welcher von der Zielallokation am stärksten abweicht. Du wirst feststellen, dass die prozentualen Abweichungen von der Zielallokation mit steigender Anlagesumme immer kleiner werden.
Super, vielen Dank!
Alles klar, danke. Ich schätze Eure Hilfe. Wenn ich es richtig sehe, dann sind bei Degiro der IShares MSCI World und der IShares MSCI Emerging Markets kostenlos. Dann spielt es keine Rolle wenn ich diese nehme statt den MSCI ACWI allein?
Bei DEGIRO wird auch eine fremdländischen Börsen Gebühr erhoben. Bei dieser spielt es aber keine Rolle wie viele ETFs man kauft und eine andere Gebühr, die von der Anzahl ETFs abhängt gibt es bei DEGIRO nicht oder?
Ist es ein Problem wenn man thresaurierende ETFs (MSCI World, MSCI Emerging Markets) mit Immobilien ETF (ausschütend) mischt? Das hat keine negativen Konsequenzen?
hier unsere Antworten zu deinen drei Fragen:
1) Was die Courtagen betrifft, so spielt es keine Rolle. Denn diese entfallen bei den DEGIRO Gratis-ETFs. Und die Wechselgebühren werden prozentual erhoben (d.h. 0,25% pro investierten Summe), was auch keinen Unterschied macht, ob du einen oder mehrere ETFs in Fremdwährung kaufst.
2) Auch bei der Gebühr für die “Einrichtung von Handelsmodalitäten” ist nicht die Anzahl ETFs entscheidend, sondern die Anzahl fremder Börsenplätze. (Bei Handel über die SIX erhebt DEGIRO für CH-Kunden keine Gebühr.) Wenn also die von dir gewünschten ETFs über den gleichen ausländischen Börsenplatz gehandelt werden, so fällt diese Gebühr nur einmal an.
3) Nein, wir sehen da kein Problem.
Beste Grüsse
SFB
Hallo Team, dürfte ich zwei Fragen stellen?
1) Wenn ich drei ETFs über DEGIRO kaufe für mein Portfolio (MSCI World, MSCI Emerging Markets, und ein Immobilien ETF) zahle ich dann 3 mal die Gebühren bei DEGIRO? Wäre es dann nicht besser ich würde nur in den MSCI ACWI investieren und einen Immobilien ETF um die Gebühren tief zu halten? Vor allem, da ich zu Beginn zw. 100 – 1000 investieren möchte.
2) Gibt es eine Fausregel zur Gewichtung von MSCI World und MSCI Emerging Markets? ZB. 70% World, 30% Emerging Markets?
Hoi Mirko
Ja klar, du kannst immer Fragen stellen, zu all unseren Artikeln, auch zu älteren Exemplaren, wie der vorliegende.
1) Bei den Gratis-ETFs von DEGIRO spielt die Anzahl ETFs bezüglich der Gebühren keine Rolle. Bei allen anderen ETFs kommt eine Pauschalgebühr pro Transaktion zur Anwendung. Das heisst, wir sehen es wie du. Gebührenmässig fährst du in diesen Fällen (d.h. bei nicht Gratis-ETFs) besser, wenn du dich auf einen einzigen ETF konzentrierst. Bei den von dir genannten Beträgen würden wir diese Variante klar vorziehen (d.h. einen globalen ETF basierend auf MSCI ACWI oder FTSE All-World). Vgl. bei Bedarf auch unseren Artikel über die besten ETFs.
2) Nein, eine Faustregel ist uns nicht bekannt. Wenn du eine “neutrale” Gewichtung anstrebst (d.h. schlicht nach Marktkapitalisierung, wie sie im MSCI ACWI oder FTSE All-World abgebildet wird), dann wäre das Verhältnis etwa 9:1. Manche Anleger gewichten die Emerging Markets jedoch bewusst etwas stärker (z.B. 8:2 oder gar 7:3, wie von dir erwähnt), weil sie damit bzw. durch die Faktorprämie “Political Risk” langfristig eine bessere Rendite erhoffen. Vgl. bei Bedarf auch unseren Artikel über Factor-Investing.
Beste Grüsse
SFB